English
This topic pulls the macroeconomics together: the goals a government has, how they clash, and how well its tools work.
A-Level 经济学 · 知识点 10
 7:13
政府宏观经济干预(A Level)
在这类大楼内部,一个小委员会开会并更改一个数字:利率。没有建设任何东西,也没有购买任何东西。然而几天内……
英语旁白 · 英中内嵌字幕
This topic pulls the macroeconomics together: the goals a government has, how they clash, and how well its tools work.
来源:Cambridge International 教学大纲
Governments aim at several macroeconomic objectives 宏观经济目标 at once:

| Objective | How it is measured |
|---|---|
| economic growth 经济增长 | the % change in real GDP |
| price stability 物价稳定 (low inflation 通货膨胀) | the % change in the consumer price index |
| full employment 充分就业 | the unemployment rate |
| balance of payments 国际收支 stability | the current account balance |
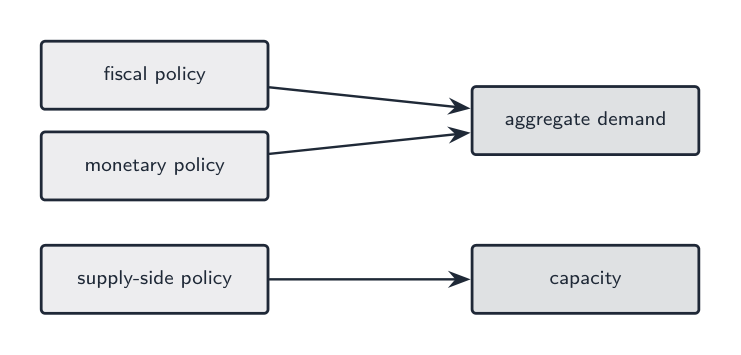
To reach these goals, the government uses three sets of tools:
Fiscal and monetary policy can change aggregate demand 总需求, with effects depending on timing, confidence and spare capacity. Supply-side measures aim to improve capacity and productivity, but their speed and effectiveness vary. Public investment can have both demand effects now and capacity effects later.

根据政策示例所针对的宏观经济目标对其进行分类。
| English | 中文 | 拼音 |
|---|---|---|
| macroeconomic objectives/ˌmækrəˌriːkəˈnɒmɪk ɒbˈdʒektɪvz/ | 宏观经济目标 | hóng guān jīng jì mù biāo |
| economic growth/ˌiːkəˈnɒmɪk ɡrəʊθ/ | 经济增长 | jīng jì zēng zhǎng |
| price stability/praɪs stəˈbɪlɪti/ | 物价稳定 | wù jià wěn dìng |
| inflation/ɪnˈfleɪʃn/ | 通货膨胀 | tōng huò péng zhàng |
| full employment/fʊl emˈplɔɪmənt/ | 充分就业 | chōng fèn jiù yè |
| balance of payments/ˈbæləns ɒv ˈpeɪmənts/ | 国际收支 | guó jì shōu zhī |
| fiscal policy/ˈfɪskl ˈpɒlɪsi/ | 财政政策 | cái zhèng zhèng cè |
| monetary policy/ˈmʌnɪtəri ˈpɒlɪsi/ | 货币政策 | huò bì zhèng cè |
| interest rate/ˈɪntrest reɪt/ | 利率 | lì lǜ |
| supply-side policy/səˈplaɪ saɪd ˈpɒlɪsi/ | 供给侧政策 | gōng jǐ cè zhèng cè |
| aggregate demand/ˈæɡrɪɡeɪt dɪˈmænd/ | 总需求 | zǒng xū qiú |

来源:Cambridge International 教学大纲
The objectives are interrelated — reaching one can move another. Often there is a trade-off 取舍, a conflict 冲突 where gaining on one goal costs you on another.
Because the goals are linked, a government must often accept "second best" on one aim to protect another. A clever policy mix tries to ease the trade-offs — for example, productive supply-side measures may raise capacity and ease inflation pressure. Demand expansion with ample spare capacity can also increase output without strong inflation pressure; neither result is guaranteed.
根据政策示例所针对的宏观经济目标对其进行分类。
| English | 中文 | 拼音 |
|---|---|---|
| trade-off/treɪd ɒf/ | 取舍 | qǔ shě |
| conflict/ˈkɒnflɪkt/ | 冲突 | chōng tū |
| Phillips curve/ˈfɪlɪps kɜːv/ | 菲利普斯曲线 | fēi lì pǔ sī qū xiàn |

来源:Cambridge International 教学大纲
Each tool has strengths and weaknesses.
Government purchases can directly add to demand and target particular groups or regions. Their effect depends on subsequent spending, private-sector responses and available resources.
Worked fiscal comparison. An illustrative economy has unused capacity and weak private spending. Government proposes an extra £10 billion of purchases, financed by borrowing. Use a multiplier $k=2.5$; hold taxes, exports and other spending changes constant. In Case A, private investment is unchanged. In Case B, higher interest rates reduce private investment by £4 billion. Let $\Delta A$ be the net autonomous spending change. All spending and income changes in these equations are in £ billions.
In this model, crowding out 挤出效应 reduces the income gain by £10 billion; income still rises. Partial crowding out does not mean each pound of government spending replaces a pound of private spending. The multiplier and private investment response are stated assumptions, not forecasts for every economy.
One mechanism is government borrowing increasing demand for loanable funds, raising interest rates and discouraging private investment, other things equal. Its size depends on the supply of finance, central-bank action, confidence and firms' responsiveness to rates. With idle resources or supportive monetary conditions, the interest-rate effect may be small. Productive public infrastructure may instead encourage some private investment. Near capacity, public projects may compete for workers and materials even without a large interest-rate rise; identify that resource constraint separately.
Timing and financing. Time lags 时滞 arise in diagnosis, approval, implementation and spending responses. A construction programme approved during a slump may arrive after recovery, when capacity constraints create more inflationary pressure and less extra real output. Tax cuts need not all be spent. Automatic changes in taxes and benefits can begin without a new budget decision.
A deficit is a flow over a period; the national debt 国债 is an outstanding stock. Additional borrowing tends to add to debt, holding other flows constant. Not every spending increase is borrowed, and public investment can improve future capacity.

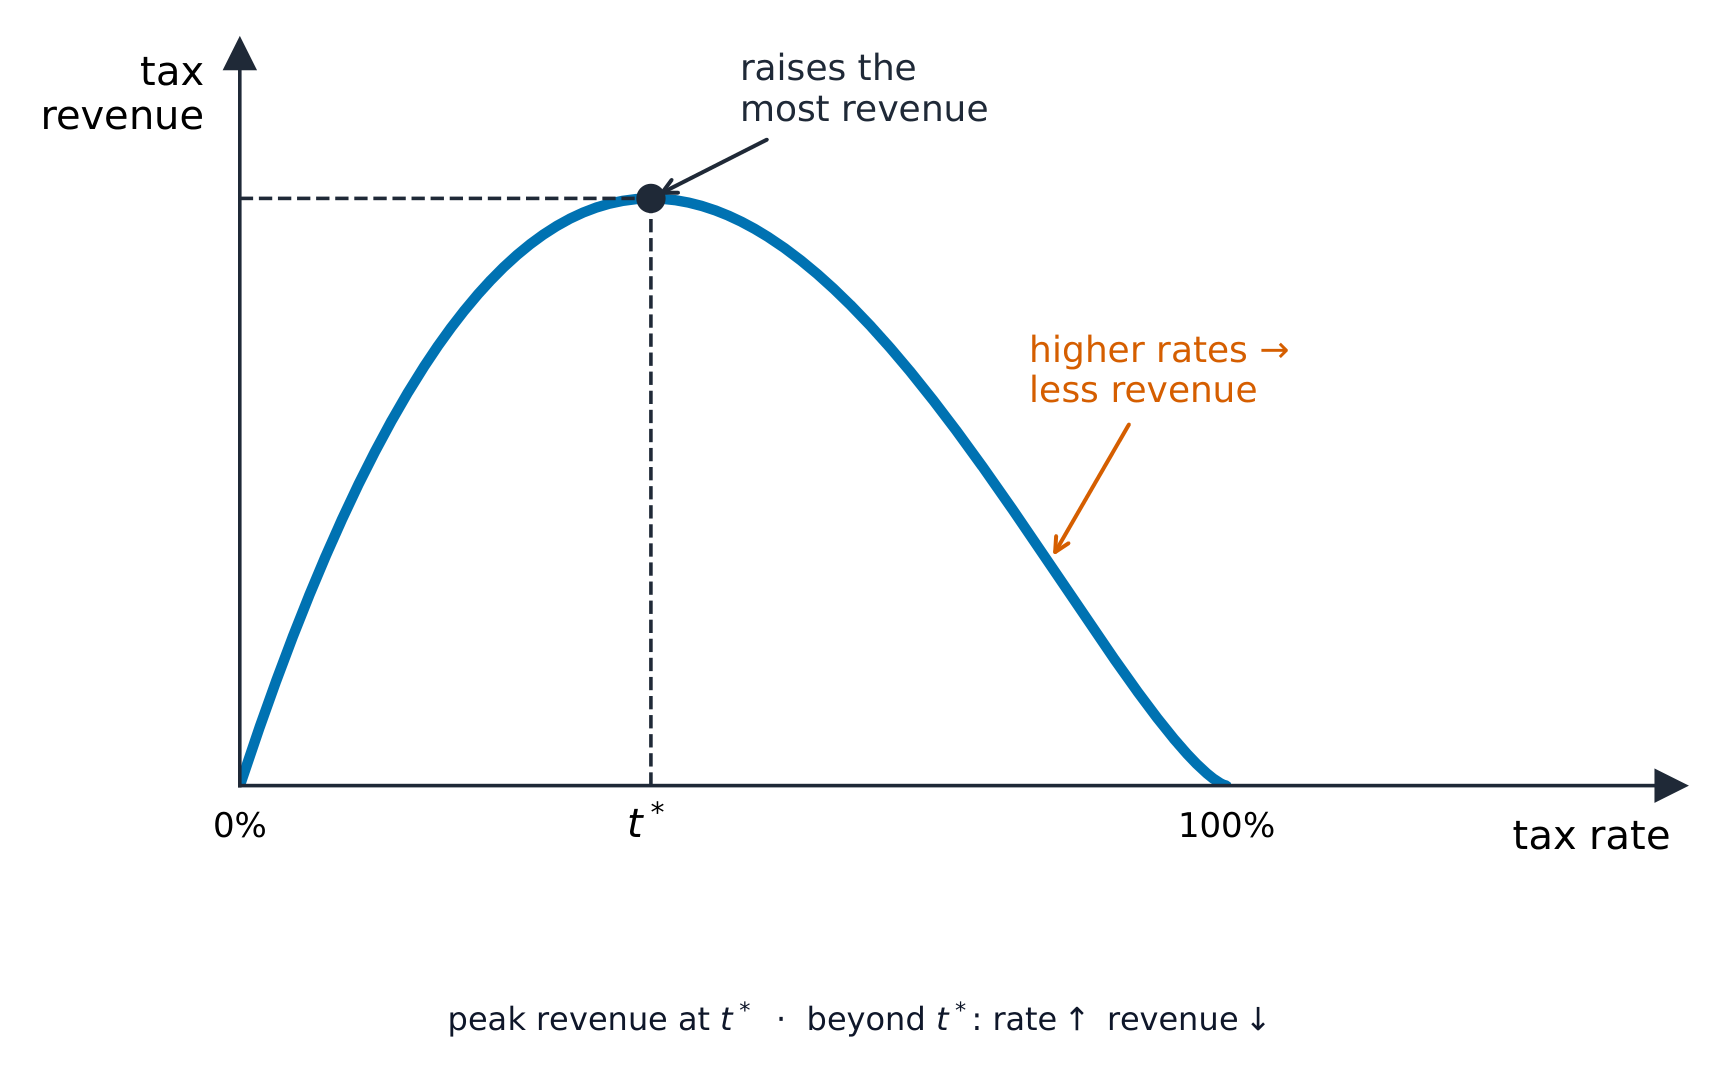
The Laffer curve 拉弗曲线 is a useful warning. It shows that as the tax rate rises, tax revenue 税收收入 first rises but then falls: very high rates discourage work and encourage tax avoidance, so revenue drops. There is a tax rate that raises the most revenue, and going above it is self-defeating.
It is flexible — the interest rate can be changed at any time. But it also works with a long time lag, and in a deep slump even very low rates may fail to make worried firms and households borrow.
The transmission mechanism 传导机制. A rise in the central bank's policy rate reaches the economy through several channels:
All five reduce aggregate demand or inflation, but they work with lags of roughly one to two years, so the bank must act on forecasts, not on today's inflation.
A real case. UK inflation reached 11.1 % in October 2022, mostly from energy and food prices. The Bank of England raised Bank Rate from 0.1 % in December 2021 to 5.25 % by August 2023. Inflation fell to the 2 % target in May 2024, and the Bank began cutting rates in August 2024. Economists still debate how much of the fall came from higher rates and how much from energy prices falling back: monetary policy cannot lower the world price of gas, so part of the inflation was outside its reach.
Limits. When rates are already close to zero, the central bank cannot cut much further (the zero lower bound). If households and firms are pessimistic, even very cheap credit may not raise spending, a situation called a liquidity trap 流动性陷阱. Central banks then used quantitative easing 量化宽松 (QE): creating money to buy government bonds, which lowers long-term interest rates. The Bank of England's purchases reached £895 billion by the end of 2021. QE can support demand, but it also raised the prices of assets owned mainly by richer households.
Productive measures can raise capacity and ease inflation pressure. They are not free of trade-offs: education and training take time and funding, some measures can widen inequality, and infrastructure can impose environmental costs. Outcomes depend on implementation and on which constraints actually limit production.
Supply-side policies come in two families:
| Market-based 以市场为基础 | Interventionist 干预主义 | |
|---|---|---|
| Idea | remove barriers so markets work better | the state invests where markets under-provide |
| Examples | lower income and corporate tax rates, privatisation, deregulation, weaker trade-union power, benefit reform | education and training, infrastructure, subsidies for research and development, regional policy |
| Main risk | inequality may widen; gains may be small if the barrier was not the real constraint | cost to the budget; the state may choose the wrong projects (government failure) |

The diagram shows why supply-side policy is the long-run way out of the conflict between growth and inflation. The timing matters: the capacity must arrive before or with the extra demand. Training and infrastructure take years, so they cannot fix inflation that is happening now.
No single policy can hit every target. The objectives conflict, the effects come with delays, and the future is uncertain. So governments usually combine demand-side policies 需求侧政策 (fiscal and monetary) for the short term with supply-side policy for the long term, and accept that some goals must be traded against others.
Worked policy judgement. A government cuts interest rates to reduce cyclical unemployment. If households and firms respond by borrowing and spending more, aggregate demand may rise. With spare capacity, firms can expand output and employment; near capacity, more of the response may be inflation. Weak confidence or already-low rates can reduce the response. Imports may rise with income, but the current account depends on exports and other influences too. State the transmission mechanism and conditions before judging the objective at risk. Capacity improvements may ease a conflict, but no policy label guarantees growth with lower inflation and no other cost.
根据所展示的经济学概念对真实案例进行分类。
| English | 中文 | 拼音 |
|---|---|---|
| time lags/taɪm læɡz/ | 时滞 | shí zhì |
| national debt/ˈnæʃənl det/ | 国债 | guó zhài |
| crowding out/ˈkraʊdɪŋ aʊt/ | 挤出效应 | jǐ chū xiào yìng |
| Laffer curve/ˈlæfə kɜːv/ | 拉弗曲线 | lā fú qū xiàn |
| tax revenue/tæks ˈrevənjuː/ | 税收收入 | shuì shōu shōu rù |
| transmission mechanism/trænˈsmɪʃn ˈmekənɪzəm/ | 传导机制 | chuán dǎo jī zhì |
| liquidity trap | 流动性陷阱 | liú dòng xìng xiàn jǐng |
| quantitative easing/ˈkwɒntɪteɪtɪv ˈiːzɪŋ/ | 量化宽松 | liàng huà kuān sōng |
| market-based/ˈmɑːkɪt beɪst/ | 以市场为基础 | yǐ shì chǎng wèi jī chǔ |
| interventionist/ˌɪntəˈvenʃənɪst/ | 干预主义 | gān yù zhǔ yì |
| demand-side policies/dɪˈmænd saɪd ˈpɒlɪsiz/ | 需求侧政策 | xū qiú cè zhèng cè |
来源:Cambridge International 教学大纲
"Supply-side policies are the most effective way for a government to achieve all its macroeconomic objectives." Evaluate this view.
A strong answer has four parts. Use this plan, then write it out in about 45 minutes.
What examiners reward: a diagram that is used in the argument, not just drawn; evaluation of each side; a judgement that answers the question ("most effective… for which objective, and over what time period?").
Vocabulary card meanings
macroeconomic objectives: The main aims for the whole economy, such as jobs and stable prices. tax revenue: Money a government collects through taxation.
逐步完成,配合即时检查练习。
正在加载学科…