Skip to content · ⁨본문 바로가기⁩

Operations management · ⁨운영 관리⁩

IGCSE Business Studies · ⁨IGCSE 비즈니스 연구⁩ · Topic 4 · ⁨주제 4⁩

Video lesson for this topic · ⁨이 주제용 영상 수업⁩ Open the video page · ⁨영상 페이지 열기⁩
9:48

운영 관리

자동차 공장을 들여다보십시오. 동일한 자동차가 반복적으로 생산되며, 하루에 수백 대씩, 각각 이전 것과 정확히 동일합니다. 누군가가 이를 모두 결정했습니다: 어떻게 만드는지, 무엇을…

English narration · English + 中文 subtitles burned in · ⁨영어 내레이션 · 영어 + 중국어 자막 burned-in⁩

4.1

Methods of production · ⁨생산 방식⁩

Syllabus
English
  1. describe the methods of production: job, batch and flow production, and their advantages/disadvantages
  2. explain productivity and how it can be increased
  3. explain lean production and just-in-time (JIT) inventory control and the management of inventory
  4. explain how technology has changed production
한국어
  1. 생산 방법(조별 생산, 배치 생산, 흐름 생산)과它们的利点及缺点을 서술하시오
  2. 생산성과 이를 높이는 방법을 설명하시오
  3. 린 생산(JIT) 재고 관리 및 재고 관리를 설명하시오
  4. 기술이 생산 방식을 어떻게 변화시켰는지 설명하시오

Source: Cambridge International syllabus · ⁨출처: Cambridge International syllabus⁩

English
Stock control: the sawtooth chart

Production 生产 means turning materials and labour 劳动力 into finished goods and services 服务. There are three main methods.

Method What it is Good for Drawback
job production 单件生产 making one item at a time, to order special, one-off items: a wedding cake, a ship slow and costly per item
batch production 批量生产 making a group of the same item, then switching to another group bakeries, clothes in different sizes machines stand idle while switching
flow production 流水线生产 making goods non-stop on a moving line mass-made goods: cars, drinks costly to set up; work can be boring

Productivity

Productivity 生产率 measures how much each worker or machine produces in a set time. Higher productivity lowers the cost per item. A business can raise productivity by:

  • training workers,
  • using better machines and technology 技术,
  • improving motivation 激励,
  • organising the work better.

Lean production and just-in-time

Lean production 精益生产 means cutting all waste — wasted time, materials, space and effort — while keeping quality.

One key method is just-in-time 准时制 (JIT). With JIT, materials arrive just as they are needed, and finished goods are sold quickly, so the business holds very little inventory 库存 (its stock of materials and goods). This saves storage cost, but one late delivery can stop production. Good management of inventory keeps enough stock to meet demand, but not so much that money is tied up or goods go out of date.

Technology in production

Technology has changed production. Automation 自动化 (machines and robots doing tasks), computer design and online ordering all make production faster, cheaper and more exact. But machines cost a lot to buy and can replace workers' jobs.

한국어
재고 관리: 톱니바퀴 차트

생산(Production) 은 자재와 노무(labour) 를 완제품 및 서비스로 전환하는 것입니다. 주요 방법은 세 가지입니다.

공장 내 자동차 조립 라인: 이동식 라인 위에서 순서대로 배치된 부분 조립된 자동차
자동차 조립 라인: 이동하는 라인에서 많은 동일한 제품을 만드는 모습
방법 내용 적합한 경우 단점
조립 생산(job production) 주문에 따라(item) 하나씩 제작 special, one-off items: 결혼 케이크, 선박 느리고 품당 비용 높음
배치 생산(batch production) 동일한 그룹의 제품을 먼저 만들고, 다른 그룹으로 전환 제빵 공장, 다양한 사이즈의 의류 전환 시 기계 가동 중단
연속 생산(flow production) 이동식 라인에서 중단 없이 상품 생산 대량 생산품: 자동차, 음료 설치 비용 높음; 작업이单调할 수 있음
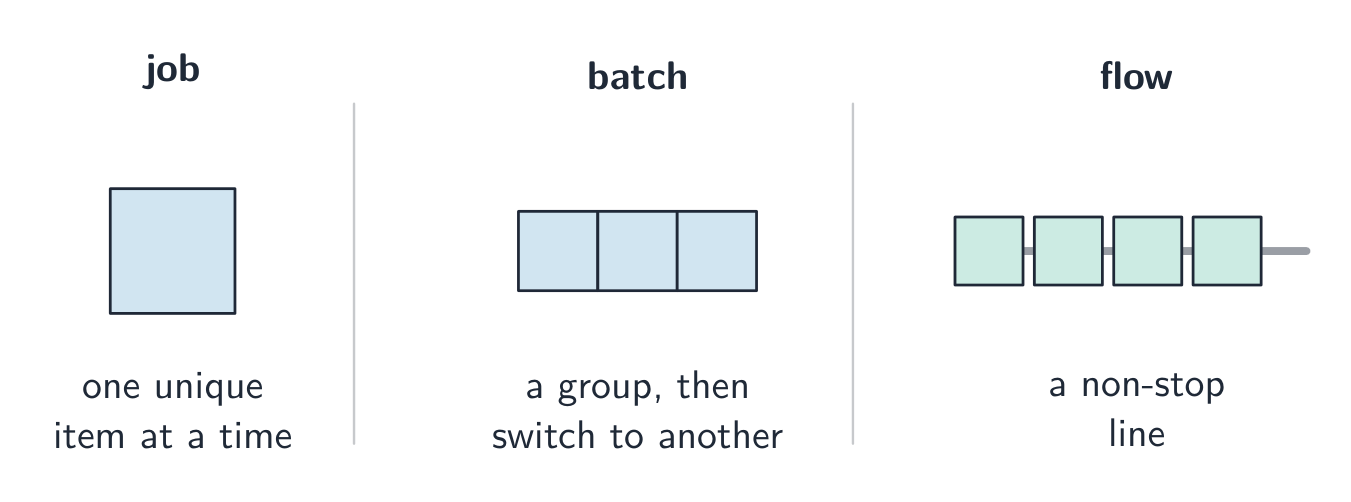
세 가지 생산 방식: 조업(유니크(item) 1개), 배치(일괄 생산 후 전환), 연속(라인에서 멈추지 않고 이동)
세 가지 생산 방식

생산성

생산성은 일정한 시간당 각 노동자 또는 기계가 생산하는 양을 측정합니다. 생산성이 높아지면 제품당 비용이 낮아집니다. 기업은 다음 방법을 통해 생산성을 높일 수 있습니다:

  • 노동자를 교육하고,
  • 더 나은 기계와 기술을 사용하고,
  • 동기부여를 개선하고,
  • 업무를 더 잘 조직화하는 것입니다.
생산성은 산출량을 노동자 수와 시간으로 나눈 값이며, 노동자 교육, 더 나은 기계, 동기부여 강화, 업무 조직화를 통해 생산성을 높이면 제품당 비용을 낮출 수 있습니다
생산성은 일정한 시간당 노동자별 산출량이며, 이를 높이면 제품당 비용이 낮아집니다

생산 및 Just-in-time

린(Lean) 생산은 품질을 유지하면서 모든 낭비—소모된 시간, 자재, 공간, 노력—를 줄이는 것을 의미합니다.

주요 방법 중 하나는 Just-in-time(JIT)입니다. JIT에서는 자재가 필요한 시점에 정확히 도착하며, 완제품은 빠르게 판매되므로 기업이 보유하는 **재고(자재와 제품의 재고)**가 매우 적습니다. 이는 보관 비용을 절감하지만, 한 번의 배송 지연만으로도 생산이 중단될 수 있습니다. 재고의 적절한 관리는 수요를 충족할 만큼의 재고를 유지하되, 자금이 묶이거나 제품이 유통기한을 넘지 않도록 합니다.

Just-in-time는 거의 재고를 보유하지 않고 빈번한 배송에 의존하여 보관 비용을 절감하지만 배송 지연 시 생산이 중단됩니다; Just-in-case는 소진되지 않는 안전 재고를 보유하지만 자금이 묶입니다
Just-in-time는 빈번한 배송으로 적은 재고를 보유합니다; Just-in-case는 안전 재고를 보유합니다

생산에서의 기술

기술은 생산 방식을 변화시켰습니다. 자동화(기계와 로봇이 작업을 수행), 컴퓨터 설계 및 온라인 주문은 모두 생산을 빠르고 저렴하며 정확하게 만듭니다. 그러나 기계 구매 비용이 많이 들며, 노동자의 일자리를 대체할 수 있습니다.

자동화 생산 라인에서 오렌지색 로봇 팔이裸露한 자동차 차체를 용접하고 있습니다
자동화: 산업용 로봇이 자동차 차체를 용접하고 조립합니다 — 손으로 하는 것보다 빠르고 정확하지만 비용이 많이 들고 일부 노동자의 일자리를 대체합니다
Explore · ⁨탐색하기⁩

Methods of production · ⁨생산 방식(methods of production)⁩

A business picks job, batch or flow production to suit its product and order size. · ⁨기업은 제품과 주문 크기에 맞춰 일인 작업, 배치生産 또는 흐름 생산을 선택합니다.⁩

Vocabulary · ⁨어휘⁩ Train · ⁨연습하기⁩
English 한국어
production/prəˈdʌkʃn/ 생산
labour/ˈleɪbə/ 노무
services/ˈsɜːvɪsɪz/ 서비스
job production/dʒɒb prəˈdʌkʃn/ 조립 작업 생산(job production)
batch production/bætʃ prəˈdʌkʃn/ 배치 생산(batch production)
flow production/fləʊ prəˈdʌkʃn/ 연속 생산(flow production)
productivity/ˌprɒdəkˈtɪvɪti/ 생산성
technology/tekˈnɒlədʒi/ 기술
motivation/ˌməʊtɪˈveɪʃn/ 동기부여
lean production/liːn prəˈdʌkʃn/ 린 생산
just-in-time/dʒʌst ɪn taɪm/ Just-in-time (Just-in-time 생산)
inventory/ˈɪnvəntri/ 재고(Inventory)
automation/ˌɔːtəˈmeɪʃn/ 자동화(Automation)
Watch lesson · ⁨수업 보기⁩
4.2

Costs, scale and break-even · ⁨비용, 규모 및 손익분기점⁩

Syllabus
English
  1. classify costs into fixed, variable, total and average costs
  2. construct and interpret break-even charts; identify the break-even level of output and the margin of safety
  3. calculate and use break-even output, total revenue, total cost and profit; explain limitations of break-even analysis
한국어
  1. 원가를 고정비, 변동비, 총비용, 평균 비용으로 분류하시오
  2. 손익분기점 차트를 그리고 해석하며, 손익분기점 생산 수준과 안전 여백을 식별하시오
  3. 손익분기점 생산량, 총수입, 총비용, 이익을 계산하고 사용하며, 손익분기점 분석의 한계를 설명하시오

Source: Cambridge International syllabus · ⁨출처: Cambridge International syllabus⁩

English
Economies of scale: average cost falls
Break-even analysis, built line by line

Types of cost

A business has different kinds of cost 成本.

  • fixed costs 固定成本 do not change with output — rent, salaries, insurance. You pay them even if you make nothing.
  • variable costs 可变成本 change with output 产量 — materials, and pay for each item made. More output means more variable cost.
  • total cost 总成本 is fixed costs plus variable costs.
  • average cost 平均成本 is the total cost divided by the number of items made.
$$\text{total cost} = \text{fixed costs} + \text{variable costs}$$
$$\text{average cost} = \frac{\text{total cost}}{\text{output}}$$

Worked example. A factory has fixed costs of £8,000 and variable costs of £2 per unit, and makes 1,000 units. Find the total cost and the average cost per unit.

$$\text{total cost} = \text{\pounds} 8\,000 + (1\,000 \times \text{\pounds} 2) = \text{\pounds} 10\,000$$
$$\text{average cost} = \frac{\text{\pounds} 10\,000}{1\,000} = \text{\pounds} 10 \text{ per unit}$$

Revenue and profit

Revenue 收入 is the money a business gets from selling its products.

$$\text{total revenue} = \text{price} \times \text{quantity sold}$$

Profit 利润 is what is left after all costs are paid.

$$\text{profit} = \text{total revenue} - \text{total cost}$$

Worked example. The same factory sells all 1,000 units at £15 each. Find its total revenue and its profit.

$$\text{total revenue} = \text{\pounds} 15 \times 1\,000 = \text{\pounds} 15\,000$$
$$\text{profit} = \text{\pounds} 15\,000 - \text{\pounds} 10\,000 = \text{\pounds} 5\,000$$

Break-even

The break-even 盈亏平衡 point is the level of output where total revenue exactly equals total cost: the business makes no profit and no loss. Below it the business makes a loss; above it, a profit.

Each item sold gives an amount towards covering the fixed costs. This amount is the selling price minus the variable cost of one item (sometimes called the contribution 贡献 per unit).

$$\text{break-even output} = \frac{\text{fixed costs}}{\text{selling price per unit} - \text{variable cost per unit}}$$

A break-even chart 盈亏平衡图 plots total cost and total revenue against output. The two lines cross at the break-even point 盈亏平衡点.

The margin of safety 安全边际 is how far the actual output is above the break-even output.

$$\text{margin of safety} = \text{actual output} - \text{break-even output}$$

Worked example. A product sells for £15 with a variable cost of £5 per unit, and the firm's fixed costs are £8,000. Find the break-even output, and the margin of safety if the firm actually makes 1,200 units.

The contribution per unit is $\text{\pounds} 15 - \text{\pounds} 5 = \text{\pounds} 10$, so

$$\text{break-even output} = \frac{\text{\pounds} 8\,000}{\text{\pounds} 10} = 800 \text{ units}$$
$$\text{margin of safety} = 1\,200 - 800 = 400 \text{ units}$$

A large margin of safety is safer, because sales can fall a long way before the business makes a loss.

Limits of break-even analysis. It assumes that all output is sold, and that the selling price and the costs stay the same at every level of output. In real life these often change, so break-even is only a guide.

한국어
규모의 경제: 평균 비용 감소
손익분기점 분석, 선별로 구축됨

비용의 종류

기업에는 다양한 종류의 비용이 있습니다.

  • 고정비는 산출량과 관계없이 변하지 않습니다 — 임대료, 급여, 보험 등. 아무것도 생산하지 않아도 이 비용은 지불해야 합니다.
  • 변동비는 산출량에 따라 변합니다 — 자재비 및 제품당 인건비 등. 산출량이 늘어나면 변동비도 증가합니다.
  • 총비용은 고정비와 변동비의 합계입니다.
  • 평균비용은 총비용을 생산된 제품 수로 나눈 값입니다.
$$\text{total cost} = \text{fixed costs} + \text{variable costs}$$
$$\text{average cost} = \frac{\text{total cost}}{\text{output}}$$

해설 예제. 한 공장의 고정비는 £8,000, 제품당 변동비는 £2이며, 1,000개의 제품을 생산합니다. 총비용과 제품당 평균비용을 구하십시오.

$$\text{total cost} = \text{\pounds} 8\,000 + (1\,000 \times \text{\pounds} 2) = \text{\pounds} 10\,000$$
$$\text{average cost} = \frac{\text{\pounds} 10\,000}{1\,000} = \text{\pounds} 10 \text{ per unit}$$
비용 변동 차트: 고정비는 일정한 수준을 유지하고, 가변비는 0에서 상승하며, 총비용은 고정비만큼 간격이 두고 가변비와 평행하게 증가합니다
총비용 = 고정비 + 가변비; 생산량 증가에 따라 변하는 것은 오직 가변비뿐입니다

매출액과 이익

매출액은 기업이 제품을 판매하여 얻는 돈입니다.

$$\text{total revenue} = \text{price} \times \text{quantity sold}$$

이익은 모든 비용을 뺀 후 남은 금액입니다.

$$\text{profit} = \text{total revenue} - \text{total cost}$$

해설 예제. 같은 공장이 1,000개 제품을 모두 £15에 판매했습니다. 총매출액과 이익을 구하십시오.

$$\text{total revenue} = \text{\pounds} 15 \times 1\,000 = \text{\pounds} 15\,000$$
$$\text{profit} = \text{\pounds} 15\,000 - \text{\pounds} 10\,000 = \text{\pounds} 5\,000$$

손익분기점

손익분기점은 총매출액이 총비용과 정확히 일치하는 산출량 수준으로, 기업은 이익도 손실도 내지 못합니다. 이 지점 미만에서는 손실을 보며, 초과에서는 이익을 냅니다.

판매되는 제품마다 고정비를 상쇄하는 데 기여하는 금액이 발생합니다. 이 금액은 판매 가격에서 제품 1개당 변동비를 뺀 값이며, 때로는 **단위 당 기여금(contribution per unit)**이라고도 합니다.

$$\text{break-even output} = \frac{\text{fixed costs}}{\text{selling price per unit} - \text{variable cost per unit}}$$

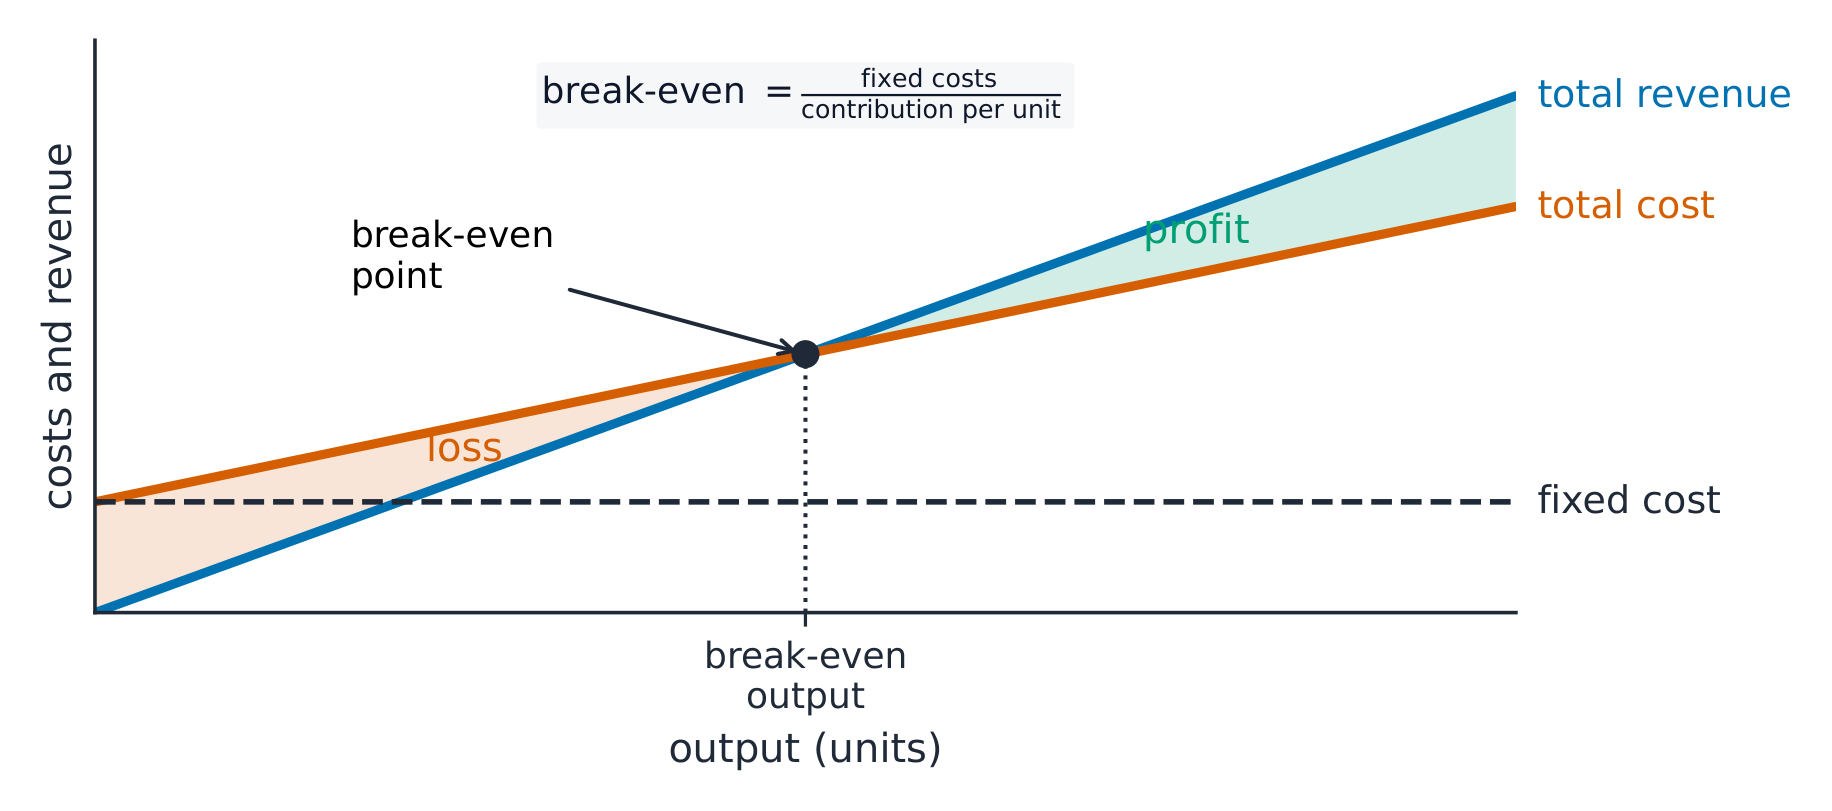
손익분기점 차트는 산출량에 따른 총비용과 총매출액을 나타냅니다. 두 선은 손익분기점에서 교차합니다.

손익분기점 차트: 총수입선이 손익분기점에서 총비용선을 교차하며, 고정비선 위쪽의 왼쪽 영역은 적자 구역, 오른쪽 영역은 이익 구역입니다
손익분기점은 총수입이 총비용과 일치하는 지점입니다—왼쪽은 적자, 오른쪽은 이익

안전마진은 실제 산출량이 손익분기점 산출량보다 얼마나 높은지를 나타냅니다.

$$\text{margin of safety} = \text{actual output} - \text{break-even output}$$

해설 예제. 한 제품의 판매 가격은 £15, 제품당 변동비는 £5이며, 기업의 고정비는 £8,000입니다. 손익분기점 산출량을 구하고, 실제 1,200개를 생산했을 때의 안전마진을 구하십시오.

단위 당 기여금은 $\text{\pounds} 15 - \text{\pounds} 5 = \text{\pounds} 10$이므로,

$$\text{break-even output} = \frac{\text{\pounds} 8\,000}{\text{\pounds} 10} = 800 \text{ units}$$
$$\text{margin of safety} = 1\,200 - 800 = 400 \text{ units}$$

안전마진이 크면 더 안전합니다. 매출이 크게 감소해도 기업이 손실을 보지 않기 때문입니다.

손익분기점 분석의 한계. 모든 산출물이 판매된다 가정하며, 모든 산출 수준에서 판매 가격과 비용이 동일하다고 가정합니다. 현실에서는 이러한 요소들이 자주 변하므로 손익분기점은 참고 자료일 뿐입니다.

Explore · ⁨탐색하기⁩

Break-even · ⁨손익 분기점(Break-even)⁩

Break-even is where total revenue crosses total cost. · ⁨손익분기점은 총 수익이 총 비용과 교차하는 지점입니다.⁩

Vocabulary · ⁨어휘⁩ Train · ⁨연습하기⁩
English 한국어
cost/kɒst/ 成本
fixed costs/fɪkst kɒsts/ 고정비(Fixed costs)
variable costs/ˈveərɪəbl kɒsts/ 변동비
output/ˈaʊtpʊt/ 输出
total cost/ˈtəʊtl kɒst/ 총원가
average cost/ˈævrɪdʒ kɒst/ 평균 비용
revenue/ˈrevənjuː/ 매출
profit/ˈprɒfɪt/ 이익
break-even/breɪk ˈiːvən/ 손익분기점
contribution/ˌkɒntrɪˈbjuːʃn/ 기여
break-even chart/breɪk ˈiːvən tʃɑːt/ 손익분기점 차트
break-even point/breɪk ˈiːvən pɔɪnt/ 손익분기점
margin of safety/ˈmɑːdʒɪn ɒv ˈseɪfti/ 안전 마진
Watch lesson · ⁨수업 보기⁩
4.3

Achieving quality · ⁨품질 달성⁩

Syllabus
English
  1. explain why quality is important to a business
  2. distinguish quality control and quality assurance and the methods used to achieve quality
한국어
  1. 품질이 기업에게 중요한 이유를 설명하시오
  2. 품질 관리(QC)와 품질 보증(QA)을 구분하고 품질 달성을 위한 방법을 서술하시오

Source: Cambridge International syllabus · ⁨출처: Cambridge International syllabus⁩

English

Why quality matters

Quality 质量 means a product is good enough for what customers 顾客 need. Good quality:

  • builds a strong brand 品牌 and customer loyalty 顾客忠诚度,
  • means fewer returns, complaints and wasted materials,
  • lets a business charge a higher price.

Poor quality loses customers and damages the brand.

Quality control and quality assurance

There are two main ways to manage quality: quality control 质量控制 and quality assurance 质量保证.

Quality control Quality assurance
When check at the end build in quality at every stage
Who inspectors check finished goods every worker is responsible
Idea find and remove faulty goods stop faults from happening at all
한국어

품질의 중요성

품질이란 제품이 고객의 요구에 충분히 부합함을 의미합니다. 좋은 품질은:

  • 강력한 브랜드와 고객 충성도를 형성하고,
  • 반품, 불만 및 자재 낭비가 줄어들며,
  • 기업이 더 높은 가격을 책정할 수 있게 합니다.

나쁜 품질은 고객을 잃고 브랜드를 손상시킵니다.

품질 관리 및 품질 보증

품질 관리를 위한 두 가지 주요 방법이 있습니다: 품질 관리(Quality Control) 와 품질 보증(Quality Assurance) 입니다.

품질 관리 품질 보증
시기 최종 검사 시 점검 모든 단계에 품질을 내장
담당자 검수원이 완제품을 점검 모든 노동자가 책임짐
개념 불량품을 찾아 제거함 결함이 발생하지 않도록 예방함
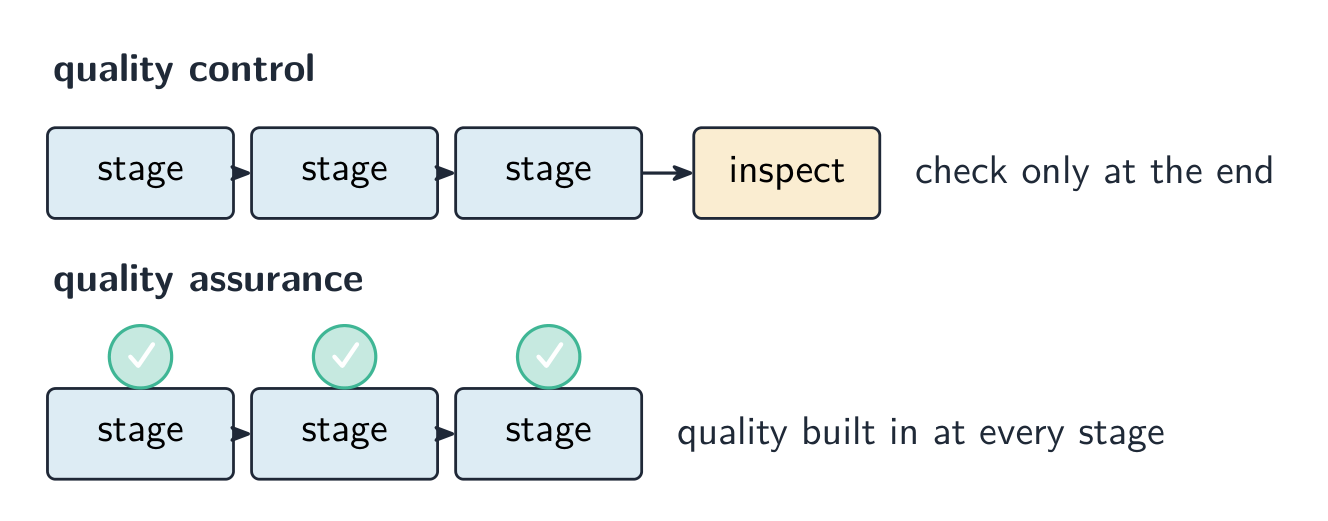
품질 통제는 검사원이 최종 단계에서 불량품만 확인하는 반면, 품질 보증은 모든 생산 단계를 통해 품질 검사를 내재화합니다
QC는 마지막 단계에서 검수함; QA는 모든 단계에 품질을 내재시킴
Explore · ⁨탐색하기⁩

Quality methods lab · ⁨품질 관리 실험실(QC Lab)⁩

Compare quality approaches by when they prevent or find faults. · ⁨결함을 예방하거나 발견하는 시점에 따라 품질 접근법을 비교하십시오.⁩

Vocabulary · ⁨어휘⁩ Train · ⁨연습하기⁩
English 한국어
quality/ˈkwɒlɪti/ 질(quality)
customers/ˈkʌstəməz/ 고객
brand/brænd/ 브랜드
customer loyalty/ˈkʌstəmə ˈlɔɪəlti/ 고객 충성도
quality control/ˈkwɒlɪti kənˈtrəʊl/ 품질 관리
quality assurance/ˈkwɒlɪti əˈʃʊərəns/ 품질 보증
manufacturing/ˌmænjuːˈfæktʃərɪŋ/ 제조업
raw materials/rɔː məˈtɪərɪəlz/ 원료 materials
market/ˈmɑːkɪt/ 시장
tariffs/ˈtærɪfs/ 관세
legal controls/ˈliːɡl kənˈtrəʊlz/ 법적 통제
4.4

Location decisions · ⁨입지 결정⁩

Syllabus
English
  1. explain the factors affecting the location decision of a manufacturing business and a service business
  2. explain the factors a business considers when locating in another country and the role of legal controls
한국어
  1. 제조 기업 및 서비스 기업의 입지 결정에 영향을 미치는 요인을 설명하시오
  2. 기업이 해외로 진출할 때 고려하는 요인과 법적 통제의 역할을 설명하시오

Source: Cambridge International syllabus · ⁨출처: Cambridge International syllabus⁩

English

Locating a business

Where a business sits affects its costs and its sales. A manufacturing 制造业 business (one that makes goods) looks at:

  • nearness to raw materials 原材料, because heavy or bulky materials cost a lot to move,
  • nearness to customers and the market 市场,
  • the cost and size of the land,
  • a supply of suitable labour,
  • good transport links,
  • government grants offered in some areas.

A service business (one that sells services, such as a shop or a hair salon) looks more at being close to customers, passing foot traffic, nearby shops, and the rent.

Locating in another country

A business may produce or sell abroad in order to reach new customers and bigger markets, pay lower wages or rent, get nearer to raw materials, or avoid tariffs 关税 (taxes on imports) by making goods inside the country. But it must then deal with different laws, languages and customs, and follow the legal controls 法律管制 of both countries.

한국어
대규모 유통 창고
企业的入址——例如本分销中心——会影响其成本和服务水平。

기업의 입지

기업의 위치는 비용과 매출에 영향을 미칩니다. 제조업 기업(제품을 만드는 기업)은 다음 사항을 고려합니다:

  • 원자재와의 근접성 (무겁거나 부피가 큰 자재는 운송비가 많이 들기 때문에),
  • 고객 및 시장과의 근접성,
  • 토지의 비용과 크기,
  • 적합한劳动力의 공급,
  • 우수한 교통망,
  • 특정 지역에서 제공되는 정부 보조금.

서비스 비즈니스(매장이나 이발소 등 서비스를 판매하는 기업)는 고객과의 근접성, 유동 인구, 인근 상권, 임대료 등을 더 중요하게 고려합니다.

해외 입지 선정

비즈니스는 새로운 고객을 확보하고 더 큰 시장을 개척하거나, 임금이나 임대료를 낮추거나, 원자재에更接近하거나, 국내 생산을 통해 관세(수입에 부과되는 세금)를 회피하기 위해 해외에서 생산하거나 판매할 수 있습니다. 하지만 이때는 다른 법제, 언어, 관습에 대응해야 하며, 양국의 법적 규제를 준수해야 합니다.

Explore · ⁨탐색하기⁩

Location factor lab · ⁨위치 요인 실험실⁩

Classify why a business chooses one site over another. · ⁨비즈니스가 한 부지를 다른 곳보다 선호하는 이유를 분류하십시오.⁩

4.4

Exam tips · ⁨시험 팁⁩

English
  • Match the production methods: job (one-off items to order), batch (a group, then switch to another), flow (non-stop mass production on a line).
  • Learn the formulas: total cost = fixed + variable; average cost = total cost ÷ output; total revenue = price × quantity; profit = total revenue − total cost.
  • Break-even output = fixed costs ÷ (selling price − variable cost per unit). How far actual output is above break-even is the margin of safety.
  • Break-even analysis assumes everything made is sold at one fixed price and cost, so it is only a guide.
  • Quality control checks finished goods at the end; quality assurance builds quality in at every stage.
한국어
  • 생산 방식을 매칭하세요: 조별/작업 방식(job) (주문에 따라 일회성 제품), 배치 방식(batch) (일단 한 무리를 만들고 다른 것으로 교체), 연속 흐름 방식(flow) (라인에서 중단 없는 대량 생산).
  • 공식을 암기하세요: 총비용 = 고정비 + 변동비; 평균원가 = 총비용 ÷ 산출량; 총매출 = 가격 × 수량; 이익 = 총매출 − 총비용.
  • 손익분기점 산출량 = 고정비 ÷ (판매가격 − 단위당 변동비). 실제 산출량이 손익분기점을 얼마나 초과하는지가 안전마진입니다.
  • 손익분기점 분석은 모든 제품이 단일 고정 가격과 비용으로 판매된다고 가정하므로, 참고 자료로만 활용됩니다.
  • 품질 관리는 완성 제품을 최종 단계에서 점검합니다; 품질 보증은 모든 단계에서 품질을 내재화합니다.

Interactive lessons on this topic · ⁨이 주제에 대한 인터랙티브 수업⁩

Work through it step by step, with instant-check exercises. · ⁨즉시 체크 기능 exercises를 통해 단계별로 진행하세요.⁩

Past Papers · ⁨과거 시험지⁩

More topics in IGCSE Business Studies · ⁨IGCSE 비즈니스 연구⁩ · ⁨IGCSE Business Studies · ⁨IGCSE 비즈니스 연구⁩ 내 추가 주제⁩

Log in or create account · ⁨로그인 또는 계정 만들기⁩

IGCSE, A-Level & AP