| English | 释义 | 拼音 |
|---|---|---|
| assets/ˈæsets/ | 资产 | zī chǎn |
| statement of financial position/ˈsteɪtmənt ɒv faɪˈnænʃl pəˈzɪʃn/ | 财务状况表 | cái wù zhuàng kuàng biǎo |
| balance sheet/ˈbæləns ʃiːt/ | 资产负债表 | zī chǎn fù zhài biǎo |
| liabilities/ˌlaɪəˈbɪlɪtiz/ | 负债 | fù zhài |
| equity/ˈekwɪti/ | 所有者权益 | suǒ yǒu zhě quán yì |
| non-current assets/nɒn ˈkʌrənt ˈæsets/ | 非流动资产 | fēi liú dòng zī chǎn |
| current assets/ˈkʌrənt ˈæsets/ | 流动资产 | liú dòng zī chǎn |
| debtors/ˈdetəz/ | 应收账款 | yīng shōu zhàng kuǎn |
| current liabilities/ˈkʌrənt ˌlaɪəˈbɪlɪtiz/ | 流动负债 | liú dòng fù zhài |
| non-current liabilities/nɒn ˈkʌrənt ˌlaɪəˈbɪlɪtiz/ | 非流动负债 | fēi liú dòng fù zhài |
Do £120,000 of assets all belong to the owner?
- A repair shop lists £120,000 of assets, but it also owes suppliers and a bank. The asset total alone cannot tell us the owners' stake or how much cash can be spent today.
- A statement of financial position 财务状况表, also called a balance sheet 资产负债表, shows assets, liabilities and equity at a named date. The income statement measures profit over a period; this statement is a snapshot on one day.
Identify current and non-current assets
- Assets 资产 are resources the business owns or controls. Non-current assets 非流动资产 are kept for continuing use, such as workshop machinery and buildings. They are not bought to sell in normal trading.
- Current assets 流动资产 include cash, stock held for sale and debtors 应收账款: customers who owe the business money. A bicycle held for sale is stock; a bicycle kept for making deliveries is a non-current asset. The business's use of an item matters.
哪一项是资产?
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
资产是企业拥有的;其他均为负债。
哪一项是流动资产?
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
现金是流动资产;建筑物和机器是非流动资产。
一家自行车零售商保留一辆自行车用于本地配送。该自行车属于哪一类分类?
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
分类取决于用途。配送用自行车是非流动资产;用于正常销售的自行车是存货,属于流动资产。
Classify what is owed
- Liabilities 负债 are amounts the business owes. Current liabilities 流动负债 are due within a year, such as amounts owed to suppliers or an overdraft. Non-current liabilities 非流动负债 are due after more than a year.
- Read the repayment dates. A loan can have £4,000 due within the next year and £16,000 due later: the first part is current and the rest is non-current. Money owed by customers is an asset; money owed to suppliers is a liability.
企业必须偿还的银行贷款是______的一个例子。
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
负债是企业所欠的款项。
一笔£24000的贷款中,有£6000需在下一年内偿还,其余部分在此之后到期。非流动负债(£)金额是多少?
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
£24000 − £6000 = £18000在超过一年后到期。一年内到期的£6000属于流动负债。
一家商店有客户欠款£7000,欠供应商£4000。哪项分类正确?
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
顾客欠商店:应收账款/债务人属于流动资产。商店欠供应商:这些债务属于流动负债。
Read how the assets are financed
- Equity 所有者权益 is the owners' stake: assets − liabilities. It includes owners' investment and profits kept in the business. The equation is assets = liabilities + equity; both sides describe the same resources and their financing.
- For the repair shop, assets £120,000 − liabilities £70,000 = equity £50,000. Liabilities £70,000 plus equity £50,000 return to assets £120,000. Equity is not an extra asset or an amount of cash in a separate box.
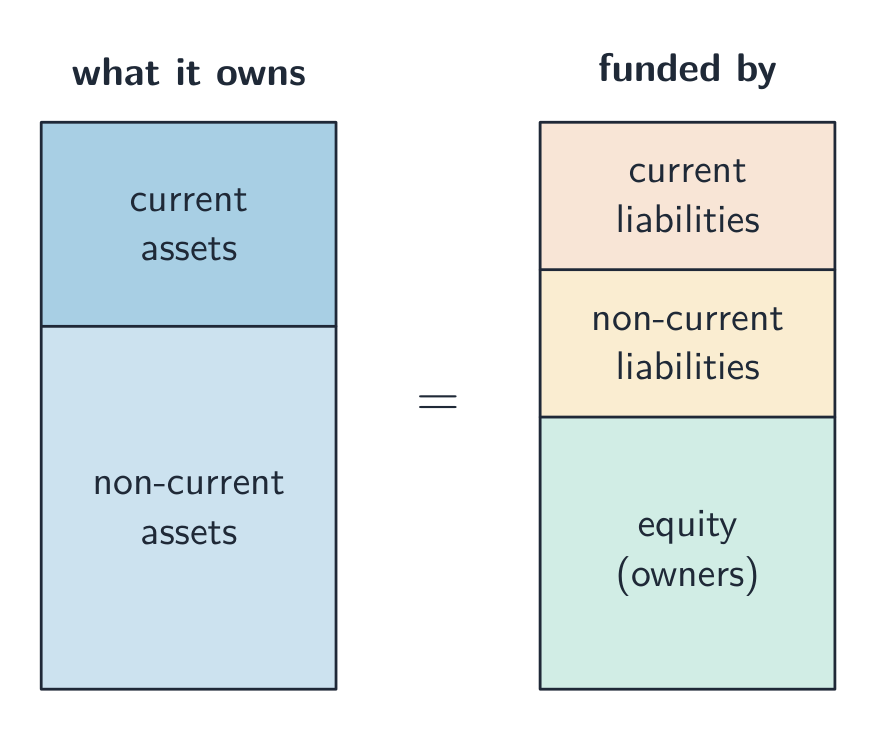
Equal totals do not mean every asset can be turned into cash immediately.
某企业拥有资产90,负债55。所有者权益是多少?
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
所有者权益 = 资产 − 负债 = 90 − 55 = 35。
在资产负债表中,资产始终大于负债加权益。
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
错误。资产始终等于负债加权益;这正是其被称为资产负债表的原因。
某企业拥有机器 £65000、存货 £14000、客户欠款 £9000 和现金 £2000。其总资产(£)是多少?
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
总资产 = £65000 + £14000 + £9000 + £2000 = £90000。不要将这些资源与权益相加。
Look inside the totals
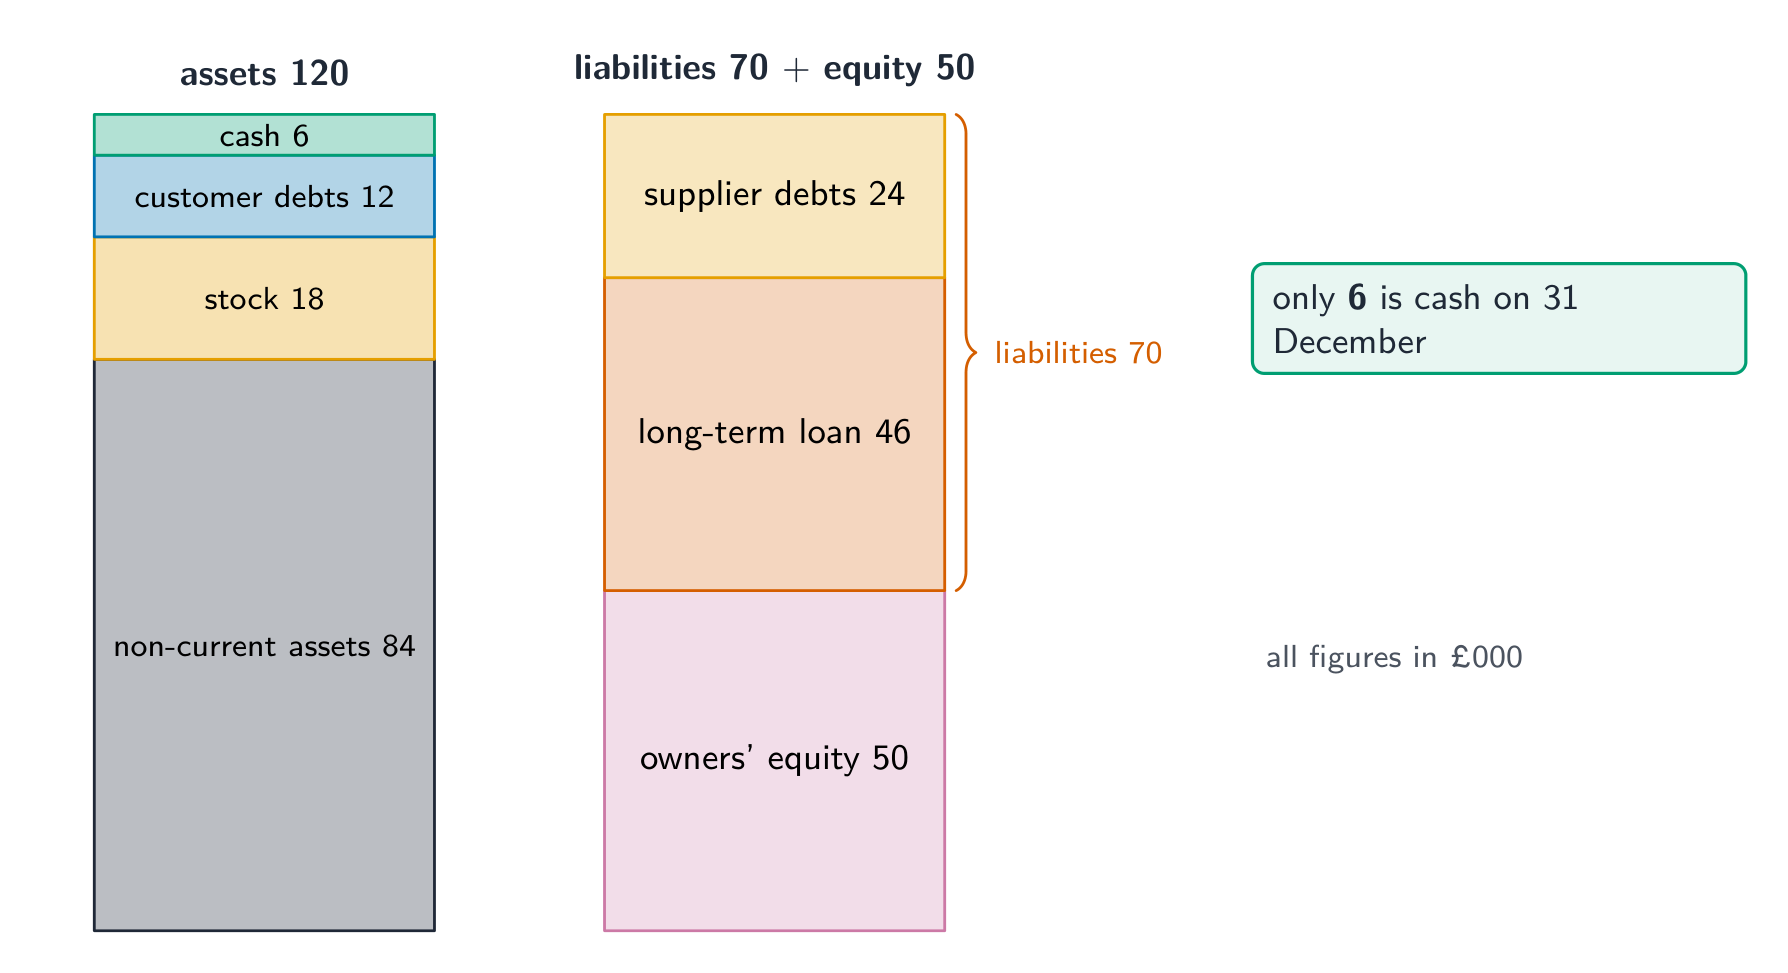
- The repair shop has £84,000 of non-current assets, £18,000 stock, £12,000 owed by customers and £6,000 cash. These total £120,000. Supplier debts of £24,000 plus a long-term loan of £46,000 make liabilities £70,000.
- It uses both borrowing/supplier credit and owners' funds. Cash £6,000 is below supplier debts £24,000. Stock sales and customer payments may help, but their timing matters; total assets of £120,000 do not prove it can pay £24,000 today.
某企业拥有总资产 £168000、流动负债 £31000 和非流动负债 £72000。所有者权益(£)是多少?
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
总负债 = £31000 + £72000 = £103000。权益 = £168000 − £103000 = £65000。
Explain why the snapshot changes
- If the shop receives a new £10,000 long-term loan, cash and total assets rise by £10,000, and liabilities rise by £10,000. Assets become £130,000 and liabilities £80,000; equity stays £50,000. Borrowing does not create profit.
- If stock recorded at £18,000 is sold for exactly £18,000 cash, stock becomes zero and cash becomes £24,000. Total assets do not change in this simplified transaction. It converts stock into cash, but no profit is made at that selling price.
某商店拥有资产 £95000 和负债 £40000。它收到一笔新的 £15000 长期贷款现金,无其他变动。此时权益(£)是多少?
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
资产变为 £110000,负债变为 £55000。权益仍为 £110000 − £55000 = £55000;借款不会增加所有者的权益份额。
某商店有 £4000 现金和账面价值 £9000 的存货。它将全部存货以恰好 £9000 的现金售出,无其他变动。请说明新的现金和存货余额,并解释对总资产和利润的影响。
使用给定的数字并将每个结论与该业务联系起来。写完自己的回答后检查模型答案。
Use the statement carefully
- Lenders examine existing debts and assets before deciding on another loan. Suppliers may use current assets and payment history before offering credit. Owners look at their stake and the mix of finance, alongside profit and future plans.
- Equity is a recorded stake, not a guaranteed selling price for the business. Stock may not sell at its recorded value and customers may pay late. One dated statement cannot by itself prove future payment ability or show the year's profit.
一份报表显示权益为 £80000。一位所有者声称这保证了他明天能以 £80000 出售该企业。请使用一个资产示例和另一项进一步证据来评估此说法。
使用给定的数字并将每个结论与该业务联系起来。写完自己的回答后检查模型答案。
Make deductions from a new statement
- Identify the date, units, asset uses and debt due dates. Add each category once, calculate equity and check that assets equal liabilities plus equity. You need to interpret a simple statement, rather than memorise how to construct one.
- Support a finance decision with both the amounts and their timing. Selling surplus stock may raise cash, but losing needed stock could interrupt trading; selling essential machinery could reduce future output.
某企业拥有资产120,负债为45。权益是多少?为什么次日该报表可能失效?
所有者权益等于资产减负债。会计恒等式确保资产始终等于负债加所有者权益。
回顾同一示例:资产为120,负债为45。所有者权益是多少?
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
120 减 45 得 75。负债 45 加所有者权益 75 等于资产。其他选项 — 35(用资产 90 减负债 55 得出的所有者权益);120(资产)。
某商店向供应商申请另外 £10000 的赊销额度。其报表(£000)列示了机器150、存货32、客户欠款20、现金8、流动负债60 和长期贷款90。计算总资产和权益。解释为何“资产超过负债”不足以批准该赊销,并建议核查哪些内容。
使用给定的数字并将每个结论与该业务联系起来。写完自己的回答后检查模型答案。