| English | 释义 | 拼音 |
|---|---|---|
| profitability/ˌprɒfɪtəˈbɪlɪti/ | 盈利能力 | yíng lì néng lì |
| liquidity/lɪˈkwɪdɪti/ | 流动性 | liú dòng xìng |
| gross profit margin/ɡrəʊs ˈprɒfɪt ˈmɑːdʒɪn/ | 毛利率 | máo lì lǜ |
| profit margin/ˈprɒfɪt ˈmɑːdʒɪn/ | 利润率 | lì rùn lǜ |
| net profit margin/net ˈprɒfɪt ˈmɑːdʒɪn/ | 净利率 | jìng lì lǜ |
| return on capital employed/rɪˈtɜːn ɒn ˈkæpɪtl emˈplɔɪd/ | 资本回报率 | zī běn huí bào lǜ |
| capital employed/ˈkæpɪtl emˈplɔɪd/ | 所用资本 | suǒ yòng zī běn |
| percentage points/pəˈsentɪdʒ pɔɪnts/ | 百分点 | bǎi fēn diǎn |
| current ratio/ˈkʌrənt ˈreɪʃɪəʊ/ | 流动比率 | liú dòng bǐ lǜ |
| acid test ratio/ˈæsɪd test ˈreɪʃɪəʊ/ | 速动比率 | sù dòng bǐ lǜ |
Which shop earns more from each pound of sales?
- Shop A earns £20,000 profit on £200,000 revenue. Shop B earns £15,000 on £100,000 revenue. A makes more total profit, but B keeps more profit from each pound of sales.
- Profitability 盈利能力 measures profit in relation to sales or capital. Liquidity 流动性 is the ability to pay short-term debts. A business can be profitable yet lack cash when a bill is due.
Calculate the two sales margins
- Gross profit margin 毛利率 = gross profit ÷ revenue × 100%. Profit margin 利润率 = profit for the year ÷ revenue × 100%. Some questions call this the net profit margin 净利率. Use the stated profit figure; do not use revenue as the numerator.
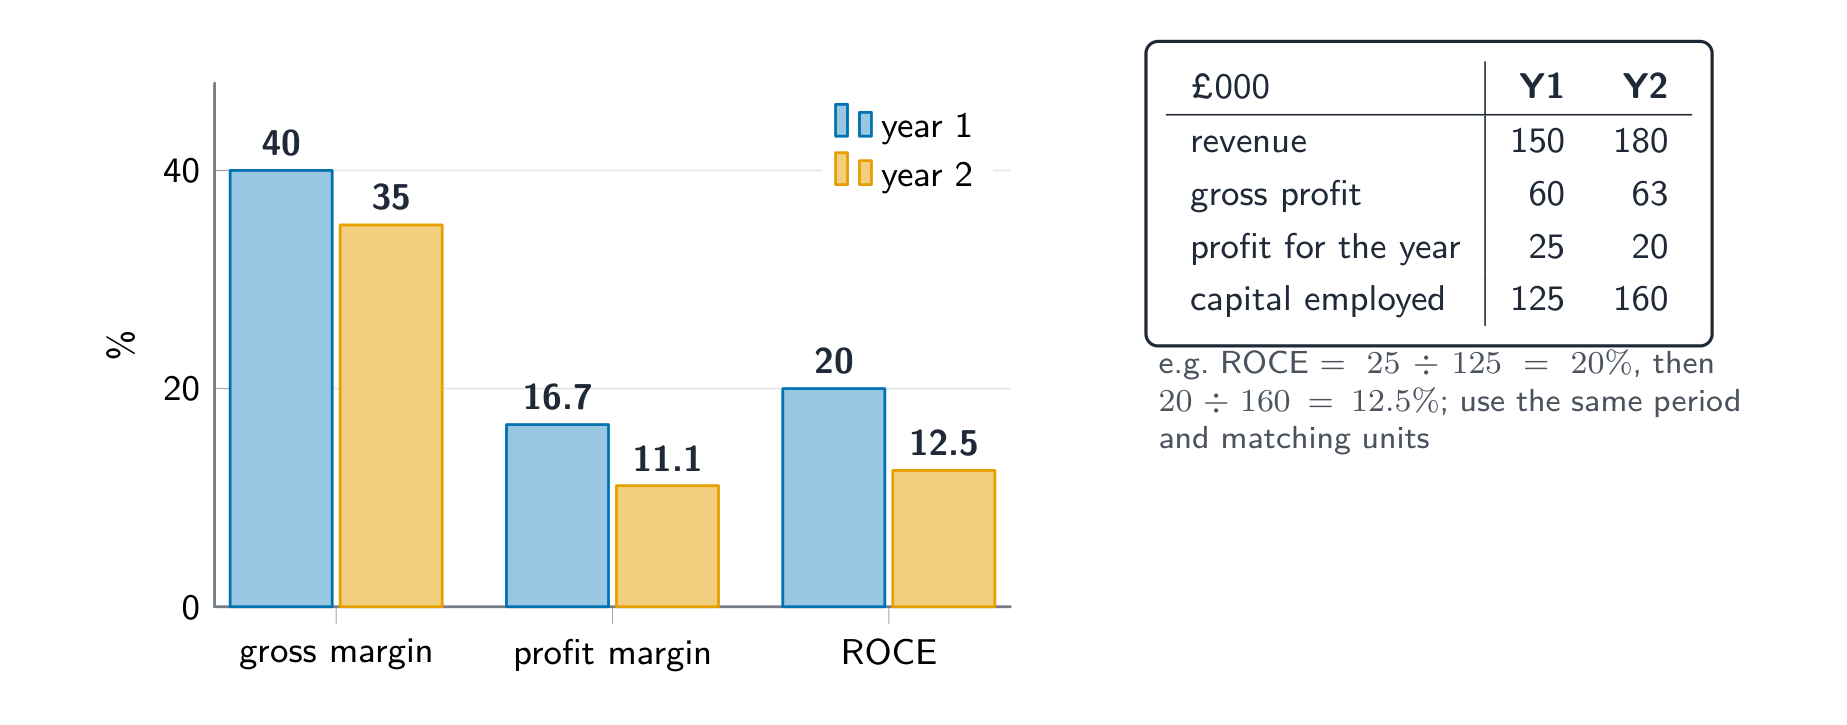
- For the worked cycle shop, revenue is £150,000, gross profit £60,000 and profit for the year £25,000. Gross margin = 60 ÷ 150 × 100 = 40%; profit margin = 25 ÷ 150 × 100 ≈ 16.7%. Each £1 of sales leaves 40p before other expenses and about 16.7p after them.
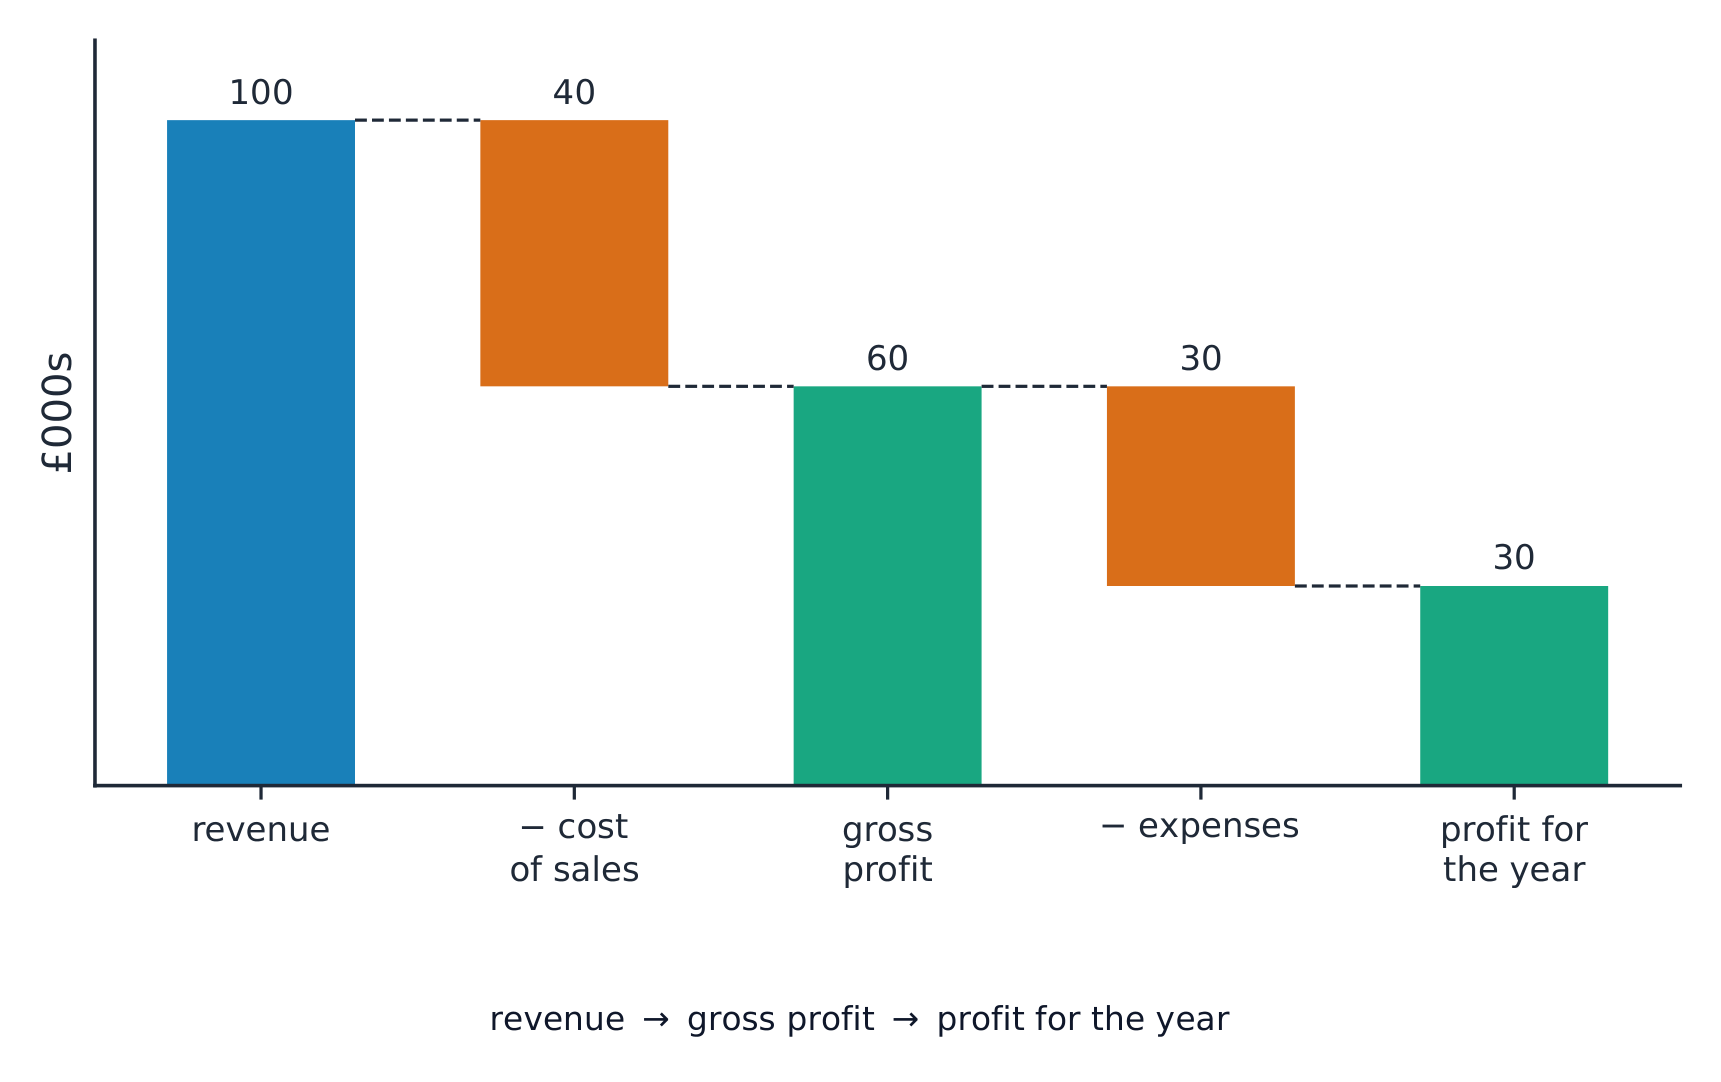
A separate example (£000): revenue 100, gross profit 60 and profit 30 give margins of 60% and 30%.
毛利润为80,收入为200。毛利率(%)是多少?
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
80 ÷ 200 × 100 = 40%.
本年度利润率计算如下:
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
利润率 = 年度利润 ÷ 收入 × 100。毛利润给出的是毛利率而非利润率。
收入为£240000,年度利润为£30000。计算利润率(%)。
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
£30000 ÷ £240000 × 100 = 12.5%。这是每£1销售额扣除费用后的利润。
Compare profit with the capital used
- Return on capital employed 资本回报率 (ROCE) = profit ÷ capital employed 所用资本 × 100%. Capital employed is the long-term funds used in the business: owners' equity + non-current liabilities, or total assets − current liabilities. Use the profit figure specified in the question.
- The cycle shop's £25,000 profit and £125,000 capital employed give ROCE = 25 ÷ 125 × 100 = 20%. That is 20p profit for each £1 of capital employed during the year. It is not a cash payment of 20p to every owner, or profit as a percentage of sales.
某企业总资产为£220000,流动负债为£70000。计算已使用资本(£)。
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
已使用资本 = 总资产 − 流动负债 = £220000 − £70000 = £150000。
利润为£48000,投入资本为£300000。计算ROCE(%)。
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
£48000 ÷ £300000 × 100 = 16%:每投入 £1 资本可获 £16p 利润。
Diagnose a change, rather than just name it
- In Year 2 the cycle shop has revenue £180,000, gross profit £63,000, profit £20,000 and capital employed £160,000. Gross margin is 35%, profit margin about 11.1%, and ROCE 12.5%. All three fell, despite higher revenue and a higher gross-profit amount.
- Gross margin falling from 40% to 35% is a fall of 5 percentage points 百分点. More of each sales pound goes to cost of sales. A lower selling price, changed product mix, higher buying costs or waste could explain it; investigate before choosing a remedy.
毛利率从42%降至36%。下降了多少个百分点?
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
42 − 36 = 6个百分点。这不是一个6%的相对降幅。
某企业收入为£120000,年度亏损为£6000。请填入其利润率(%),使用负号。
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
利润为−£6000,因此−6000 ÷ 120000 × 100 = −5%。
一家维修公司在A年以£100000已使用资本赚取£20000利润。在B年,利润增至£24000,已使用资本增至£160000。请计算两年的ROCE,并评估“利润越高意味着资本回报率越好”这一说法。
根据所给数据计算,解释商业含义,并结合相关证据对决策进行限定。
Read the current ratio as a ratio
- Current ratio 流动比率 = current assets ÷ current liabilities. Current assets of £36,000 and current liabilities of £24,000 give 1.5:1. There is £1.50 of current assets for each £1 of current liabilities; do not multiply by 100 or write 1.5%.
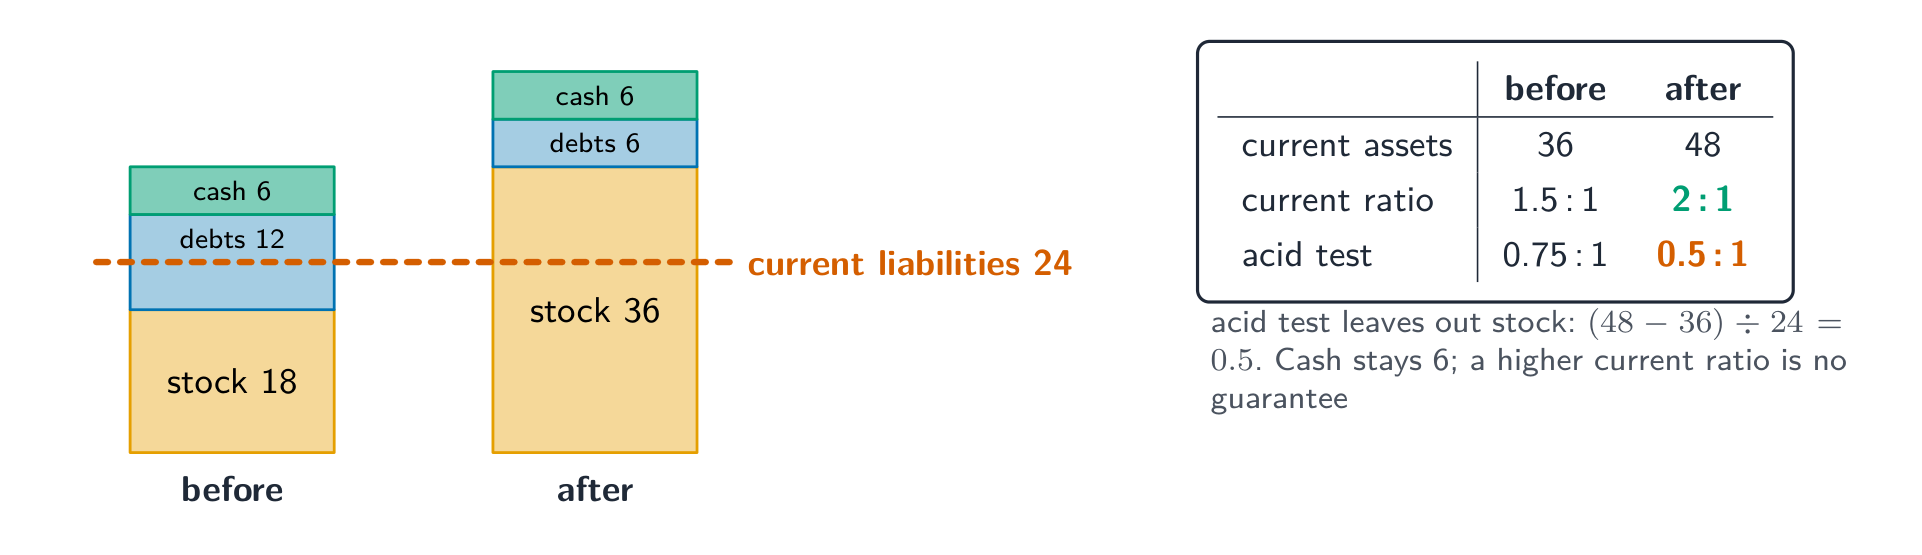
- In this example the assets are £18,000 stock, £12,000 owed by customers and £6,000 cash. Most are not cash now. The ratio is one sign of liquidity, but it does not prove that bills due today can be paid today.
流动资产为90,流动负债为45。流动比率是多少?
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
90 ÷ 45 = 2 (i.e. 2:1).
流动比率衡量企业的______(偿还短期债务的能力)。
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
流动性衡量偿还短期债务的能力。
流动资产为£54000,流动负债为£36000,得出比率为1.5。哪种解释是正确的?
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
1.5:1比较流动资产与流动负债。流动资产包括存货和应收账款,并非全部为即时可用的现金。
Apply the stricter acid test
- Acid test ratio 速动比率, also called the quick ratio, = (current assets − inventory) ÷ current liabilities. For the same business, (36 − 18) ÷ 24 = 0.75:1. Subtract stock from the numerator before dividing, not from the final ratio.
- Without selling stock, recorded current assets cover 75p for each £1 of current liabilities. Some of that 75p is still money owed by customers. Stock may sell slowly or below its recorded value; even a quick ratio above 1 does not guarantee payment on the due date.
流动资产为£84000,其中包括£36000存货。流动负债为£60000。请以数字形式填入速动比率,例如1.2。
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
(£84000 − £36000) ÷ £60000 = 0.8,或 0.8:1。
流动资产为£70000,流动负债为£40000。速动比率为1:1。存货金额是多少(£)?
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
扣除存货后的流动资产必须等于£40000。存货 = £70000 − £40000 = £30000。
Higher liquidity ratios are not always better
- At a later date current assets total £48,000: stock £36,000, customer debts £6,000 and cash £6,000. Current liabilities stay £24,000. Current ratio rises to 2:1, but acid test falls to (48 − 36) ÷ 24 = 0.5:1. More stock makes the first ratio look stronger while reducing cover without stock sales.
- A current ratio around 1.5–2 is a common guide, not a rule for every business. Fast cash sales, stock type, customer payment dates and supplier terms matter. Very high ratios may mean idle cash or excess stock, while very low cover may mean payment risk.
每个比率回答什么问题?
将五个IGCSE比率按盈利能力或流动性分类。
所有数值均为£000。A年流动资产为80,存货为40,流动负债为40。B年流动资产为100,存货为80,流动负债为40。业主称较高的流动比率证明流动性已改善。请分别计算两年的比率并评估该说法。
根据所给数据计算,解释商业含义,并结合相关证据对决策进行限定。
Link the ratio to the user's decision
- Owners and managers compare margins and ROCE with earlier years or similar businesses before setting prices, cutting waste or investing. A higher return may be attractive, but cutting essential maintenance or quality could harm future sales.
- A lender or supplier needs repayment dates, a cash-flow forecast and existing debts as well as liquidity ratios. Accounts describe past performance or one dated position. Different products, business sizes or unusual events can make comparisons misleading; customer loyalty and service quality also matter.
当与往年、竞争对手或目标进行比较时,比率最有意义。
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
比较有助于评估绩效,但也需检查业务背景、付款日期以及数据是否具有可比性。
A店在收入£200000上赚取利润£20000。B店在收入£100000上赚取£15000。业主必须选择一家企业进行投资调查。请计算利润率,区分两种可能的“更优”主张,并提出两项进一步检查建议。
根据所给数据计算,解释商业含义,并结合相关证据对决策进行限定。
Give a meaning, a comparison and a judgement
- Choose the correct numerator and denominator. Margins and ROCE are percentages; current and acid-test ratios are written as numbers or ratios to 1. Keep units consistent and round only the final answer as requested.
- A ratio has a meaning even on its own, but a sound judgement needs context. State what it shows, compare it, explain a possible cause and its effect, then name the evidence needed before recommending a decision.
毛利润为45,收入为150。流动资产为48,流动负债为32。计算毛利率和流动比率。解释每个指标的含义,并说明为何需要更多证据来评估绩效。
毛利率等于毛利润除以营业收入。流动比率等于流动资产除以流动负债。
回顾相同数据:毛利润45,收入150,流动资产48,流动负债32。毛利率是多少?
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
45 ÷ 150 × 100 = 30%。流动比率为1.5:1,不是百分比。
一家季节性商店要求额外获得£6000的供应商赊销额度。其流动比率为2:1,速动比率为0.6:1。大部分存货是上一季服装;大额账单在下个旺季到来前即需支付。仅凭这些比率就足以批准申请吗?请推荐所需证据及可能的回应。
根据所给数据计算,解释商业含义,并结合相关证据对决策进行限定。