IGCSE Business Studies (0450) has six topics: understanding business activity, people in business, marketing, operations management, financial information and decisions, and external influences. Both papers are built around short case studies.
The case study is the paper. An answer that defines a term correctly but never mentions the business in the stem earns the knowledge mark and stops. The same answer tied to that business — its size, its market, its cash position — earns application and analysis too.
Read the stem twice before writing; the details in it are the marks. The financial content — cash-flow forecasts, break-even, simple ratios — is the most reliably scorable part, because it is right or wrong rather than judged.
understand the purpose of business activity: combining factors of production (land, labour, capital, enterprise) to make goods and services that satisfy people's needs and wants
understand the economic problem: needs and wants are unlimited but resources are scarce, so choices must be made
understand opportunity cost: the next best alternative given up when a choice is made
explain the concept of added value (selling price minus cost of bought-in materials) and how a business can increase added value
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
A business 企业 is an organisation that makes goods 商品 or provides services 服务 for customers 顾客.
Goods are physical things you can touch — bread, phones, cars.
Services are useful actions done for you — a haircut, a bus ride, a doctor's visit.
The purpose of business activity is to use resources 资源 to make goods and services, so that people's needs 需要 and wants 欲望 are met.
Needs are things you must have to live: food, water, shelter, clothes.
Wants are things you would like but can live without: a holiday, a games console.
Factors of production
To produce anything, a business brings together four factors of production 生产要素 — the resources needed to make goods and services.
Factor
What it means
Example
land 土地
natural resources
farmland, water, oil, minerals
labour 劳动力
the work of people
workers, managers
capital 资本
money and the man-made tools bought with it
machines, factories, vehicles
enterprise 企业家才能
the skill to bring the other three together and take risks
the owner's idea and effort
The economic problem
People's needs and wants are unlimited. But resources are scarce 稀缺 — there are not enough of them for everything. This is the economic problem 经济问题.
Because resources are scarce, you must always choose. You cannot have everything.
Opportunity cost
When you choose one thing, you give up the next best thing. The opportunity cost 机会成本 is the next best choice you give up.
Example: a business has some money and spends it on a new machine. Now it cannot also spend that money on a bigger shop. The bigger shop is the opportunity cost.
Added value
Added value 增值 is the difference between the price a business sells a product for and the cost of the raw materials 原材料 bought in to make it.
$$\text{added value} = \text{selling price} - \text{cost of bought-in materials}$$
A business can increase added value by:
raising the price, often through a strong brand 品牌 or better design,
lowering the cost of materials, for example by finding cheaper suppliers,
improving the product so customers will pay more.
Worked example. A furniture maker buys the wood and fabric for a chair for £40 and sells the chair for £110. The factory rent is £6,000 a month. Find the added value per chair.
The rent is a deliberate distractor. Added value counts only the cost of the bought-in materials, so rent, wages and other running costs stay out of it - they matter for profit, not for added value. Subtract only what was bought in to make the product, and never treat added value as if it were profit.
Why businesses succeed or fail
A business is more likely to succeed when it has:
good management 管理 — skilled leaders who plan well,
enough finance 资金 — money to pay bills while it grows,
a product customers want, and an edge over the competition 竞争 (the other businesses selling similar things).
A business may fail and close down when it runs out of cash, manages money badly, or cannot compete. Weak management and poor cash control are the most common causes.
Change the bought-in cost, the selling price and other costs to see how business activity creates value added. · 仕入れ原価、販売価格および他のコストを変更して、事業活動がいかに付加価値を生み出すかを確認する。
classify business activity into primary, secondary and tertiary sectors with examples
understand the changing importance of business sectors (de-industrialisation) in developed and developing economies
distinguish the private sector and the public sector and give the features of each
日本語
一次産業、二次産業、三次産業に事業活動を分類し、具体例を示す
先進国および途上国の経済における各産業セクターの重要度の変化(去工業化)を理解する
民間部門と公的部門を区別し、それぞれの特徴を述べる
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
The three sectors
We sort all business activity into three groups, by how far the work is from the final customer.
Sector
What it does
Examples
primary sector 第一产业
takes natural resources from the earth
farming, fishing, mining, oil drilling
secondary sector 第二产业
makes goods from raw materials
building, manufacturing 制造业, food processing
tertiary sector 第三产业
provides services
shops, banks, transport, tourism
How the sectors change
The importance of each sector changes as a country grows richer.
In a developing economy 发展中经济体 (a poorer country building up its industry), the primary sector is often large — many people farm.
As the country grows, the secondary sector grows too.
In a developed economy 发达经济体 (a rich, industrialised country), most people work in the tertiary sector.
De-industrialisation 去工业化 is when the secondary sector shrinks and the tertiary sector grows. This has happened in many developed economies as factories move abroad.
Private sector and public sector
The private sector 私营部门 is made up of businesses owned by private people and groups. Most aim to make a profit 利润. The public sector 公共部门 is made up of organisations owned by the government, which aim to provide a service to the public.
Sort real firms by the sector they mainly belong to. · 実際の企業を主な所属セクターに基づいて分類せよ。
1.3
Enterprise, business growth and size · エンタープライズ、企業成長と規模
Syllabus · シラバス
English
describe the characteristics of a successful entrepreneur (risk-taker, hard-working, innovative, confident, organised)
explain the contents and purpose of a business plan and how it helps a business raise finance
explain why and how governments support business start-ups (grants, loans, training, advice)
measure the size of a business (number of employees, revenue/sales, capital employed) and the limitations of each measure
explain why some businesses remain small and why/how businesses grow (internal/organic growth and external growth: mergers and takeovers, horizontal, vertical and conglomerate integration)
explain economies and diseconomies of scale (purchasing, financial, managerial, technical, marketing)
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
The entrepreneur
An entrepreneur 企业家 is a person who sets up a business and takes the risk of running it. Successful entrepreneurs usually:
are willing to take risk 风险 — to risk their own money on a new idea,
work hard and do not give up,
are innovative 创新 — full of new ideas,
are confident and good at making decisions,
are well organised, able to manage time, money and people.
The business plan
A business plan 商业计划书 is a document that describes the business and its future. It usually contains the business idea and objectives, the product, the market 市场 it will sell to, who will run it, and a plan for the money.
A business plan has two main uses:
it makes the owner think carefully and plan ahead,
it helps the business raise finance 筹集资金 — banks and investors want to see a plan before they lend or invest.
Government support for start-ups
A start-up 初创企业 is a brand-new business. New businesses create jobs and help the economy grow, so governments often support them with:
grants 补助金 — money given that does not have to be paid back,
low-interest loans 贷款 — money lent on easy terms,
training and advice for new owners,
lower taxes in the first years.
Measuring the size of a business
You can measure how big a business is in several ways. Each one has a weakness.
Measure
How it works
Limitation
number of employees 员工
count the staff
a high-tech firm can have few staff but large output 产量
revenue 收入 (sales)
the value of everything sold
a firm selling cheap goods may sell a lot yet be small
capital employed 所用资本
the total money invested in the business
hard to compare between different industries
Staying small or growing
Some businesses stay small on purpose: the owner wants to keep control, the market is small, or the product is specialised.
Businesses that want to grow bigger — to achieve growth 增长 — can do it in two ways.
Internal growth 内部增长 (also called organic growth): the business grows by itself, by selling more, opening new branches, or adding new products. It is slower but lower-risk.
External growth 外部增长: the business joins with another business. This is faster. It happens through a merger 合并 (two businesses agree to join into one) or a takeover 收购 (one business buys control of another).
External growth is classified by the kind of business that is joined.
Type
What joins
Example
horizontal integration 横向一体化
two firms at the same stage of the same business
two car makers join
vertical integration 纵向一体化
two firms at different stages of the same business
a car maker buys a tyre maker
conglomerate integration 混合一体化
two firms in completely different businesses
a car maker buys a food company
Economies and diseconomies of scale
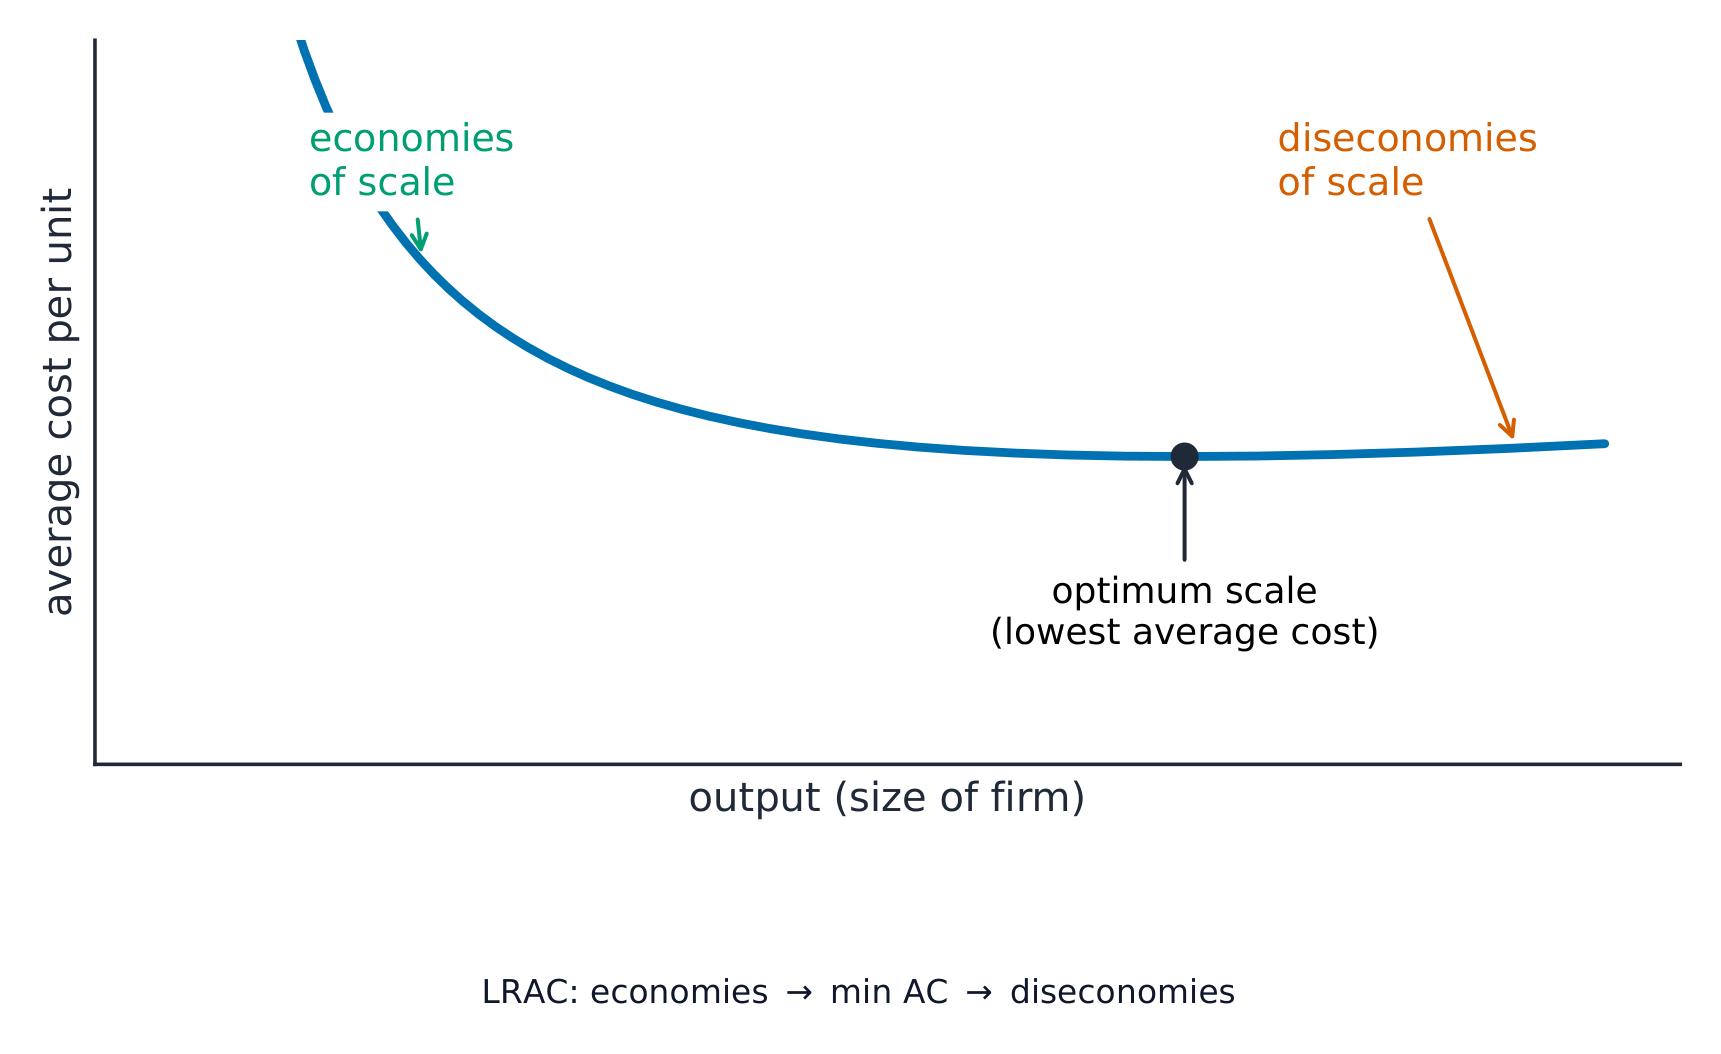
As a business grows, its cost per unit can fall. These savings are called economies of scale 规模经济.
Type
How the cost per unit falls
purchasing
buying large amounts of materials brings a lower price
financial
large firms can borrow money more cheaply
managerial
the firm can afford expert managers
technical
the firm can use large, efficient machines
marketing 营销
the cost of advertising 广告 is spread over more goods
If a business grows too big, the cost per unit can start to rise again. These are diseconomies of scale 规模不经济. They happen because communication 沟通 in a huge firm gets worse, workers feel less important and work less hard, and managers find the firm hard to control.
describe the features, advantages and disadvantages of sole traders, partnerships, private limited companies and public limited companies
explain the difference between unlimited and limited liability and between incorporated and unincorporated businesses
describe franchises, joint ventures and social enterprises and their advantages and disadvantages
explain the features of public sector business organisations (public corporations)
日本語
個人事業主、合名会社、非公開有限会社、公開有限会社の特徴、利点、欠点を記述する
無限責任と有限責任の違い、設立法人と未設立法人の違いを説明する
フランチャイズ、ジョイントベンチャー、社会企業を記述し、その利点と欠点を述べる
公的部門の企業組織(公営企業)の特徴を説明する
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
Liability
Liability 责任 means who must pay the debts 债务 if a business cannot pay them itself.
With unlimited liability 无限责任, the owner is personally responsible for all the debts. If the business fails, the owner may lose personal things, like a house or car, to pay them.
With limited liability 有限责任, the owner can only lose the money they put into the business. Their personal things are safe.
Incorporated and unincorporated
An incorporated 法人 business has a separate legal identity from its owners. The business itself can own things and be taken to court. Its owners get limited liability. Companies are incorporated.
An unincorporated 非法人 business is not separate from its owner in law. Sole traders and partnerships are unincorporated.
The four main types
A sole trader 独资企业 is a business owned by one person.
Advantages
Disadvantages
easy and cheap to set up
unlimited liability
the owner keeps all the profit
hard to raise finance
the owner makes all decisions
long hours, no one to share the work
private (accounts stay secret)
the business ends if the owner stops
A partnership 合伙企业 is owned by two or more people who share the work, the decisions and the profit. They usually sign a written agreement.
Advantages
Disadvantages
more owners bring more capital
unlimited liability (in most cases)
work and ideas are shared
the profit is shared
easy to set up
partners can disagree
one partner's mistake affects everyone
A private limited company 私人有限公司 (often "Ltd") is owned by shareholders 股东, but its shares cannot be sold to the public. The owners are often family and friends.
Advantages
Disadvantages
limited liability
more legal rules and paperwork
easier to raise capital than a sole trader
shares cannot be sold to the public
control stays in a small group
accounts must be shared with the government
A public limited company 公众有限公司 (often "plc") is a large company whose shares 股份 can be bought by the public on the stock exchange 证券交易所.
Advantages
Disadvantages
can raise very large amounts of capital
expensive and complex to set up
limited liability
accounts are fully public
well known, so easy to borrow
anyone can buy shares, so there is a risk of takeover
the original owners may lose control
Shareholders may receive a share of the profit, called a dividend 股息.
Other forms of organisation
Franchise 特许经营: a person (the franchisee 加盟商) pays to use the name, products and methods of an existing successful business (the franchisor 授权商). The franchisee gets a known brand, training and lower risk, but must pay fees and a share of the profit and has less freedom. Many fast-food chains work this way.
Joint venture 合资企业: two businesses agree to share the cost, risk and profit of one project, while staying separate companies.
Social enterprise 社会企业: a business that trades to help society or the environment, not only to make profit. Most of its profit is put back into its social aims.
Public sector organisation
A public corporation 国有企业 is a business owned and run by the government, such as a national rail or postal service. Its aims include giving an important service to everyone, not only making a profit.
Added value = selling price − cost of bought-in materials. A business raises it with a strong brand, better design, or cheaper materials.
Know the three sectors: primary (extracts raw materials), secondary (makes goods), tertiary (services). As a country develops, employment shifts from primary towards tertiary.
Unlimited liability (sole traders, partnerships) puts the owner's personal things at risk; limited liability (Ltd, plc) limits any loss to the money invested.
A stakeholder is anyone affected by the business, and their objectives often conflict — owners want profit, workers want higher pay, the community wants less pollution.
Economies of scale cut the cost per unit as a firm grows; growing too big brings diseconomies of scale (cost per unit rises).
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
Motivation 激励 is the drive that makes people want to work hard. A well-motivated workforce 员工队伍 — all the employees 员工 in a business — brings real benefits:
higher productivity 生产率 — each worker produces more,
lower absenteeism 缺勤 — fewer workers stay away from work,
lower labour turnover 员工流动率 — fewer workers leave, so the business spends less time and money hiring and training new staff.
Motivation theories
Three thinkers explain what makes workers work hard.
Thinker
Main idea
Taylor
Workers are mainly motivated by pay. Pay them more for more work (piece rate) and they work harder.
Maslow
People have a hierarchy of needs 需求层次: five levels, from basic pay and safety up to respect and reaching your full potential. You must meet the lower needs before the higher ones can motivate.
Herzberg
Two groups of factors. Hygiene factors 保健因素 (pay, conditions, rules) do not motivate, but poor ones cause unhappiness. Motivators 激励因素 (achievement and responsibility) truly drive people to work harder.
Financial methods of motivation
These reward workers with money.
Method
What it means
wage 工资
regular pay, often by the hour or week
time rate 计时工资
pay for each hour worked
piece rate 计件工资
pay for each item made
salary 薪金
a fixed yearly amount, paid monthly
commission 佣金
pay based on how much you sell
bonus 奖金
an extra payment for good work
profit sharing 利润分享
workers get a share of the company's profit
fringe benefits 额外福利
extras like a company car, free meals or health care
Worked example. A factory pays a piece rate of £3 per item. Anya makes 210 items in a week. Ben is on a time rate of £12 per hour for a 40-hour week. Who earns more, and what risk does the piece rate carry? Anya earns 210 × £3 = £630. Ben earns 40 × £12 = £480, so Anya earns £150 more. But paying for each item made tempts workers to rush, so quality may fall and more items are rejected - which is why a piece rate usually has to be paired with quality checks. Show the calculation, then judge it: a question that asks who earns more and for an evaluation gives marks for the number and for the drawback.
Non-financial methods of motivation
These motivate without extra money.
job rotation 工作轮换 — workers switch between different tasks, so work is less boring.
job enlargement 工作扩大化 — adding more tasks at the same level.
job enrichment 工作丰富化 — giving more challenging tasks and more responsibility.
autonomy 自主权 — letting workers make some of their own decisions.
teamworking 团队合作 — working in small groups.
training 培训 and chances for promotion 晋升 — helping workers improve and move up.
日本語
Maslow's hierarchy of needs, with workplace examples at each level.Motivated workers work harder, raising output
Motivation 激励 is the drive that makes people want to work hard. A well-motivated workforce 员工队伍 — all the employees 员工 in a business — brings real benefits:
higher productivity 生产率 — each worker produces more,
lower absenteeism 缺勤 — fewer workers stay away from work,
lower labour turnover 员工流动率 — fewer workers leave, so the business spends less time and money hiring and training new staff.
Motivation theories
Three thinkers explain what makes workers work hard.
Thinker
Main idea
Taylor
Workers are mainly motivated by pay. Pay them more for more work (piece rate) and they work harder.
Maslow
People have a hierarchy of needs 需求层次: five levels, from basic pay and safety up to respect and reaching your full potential. You must meet the lower needs before the higher ones can motivate.
Herzberg
Two groups of factors. Hygiene factors 保健因素 (pay, conditions, rules) do not motivate, but poor ones cause unhappiness. Motivators 激励因素 (achievement and responsibility) truly drive people to work harder.
Maslow's hierarchy: people meet lower needs before higher ones
Financial methods of motivation
These reward workers with money.
Method
What it means
wage 工资
regular pay, often by the hour or week
time rate 计时工资
pay for each hour worked
piece rate 计件工资
pay for each item made
salary 薪金
a fixed yearly amount, paid monthly
commission 佣金
pay based on how much you sell
bonus 奖金
an extra payment for good work
profit sharing 利润分享
workers get a share of the company's profit
fringe benefits 额外福利
extras like a company car, free meals or health care
Worked example. A factory pays a piece rate of £3 per item. Anya makes 210 items in a week. Ben is on a time rate of £12 per hour for a 40-hour week. Who earns more, and what risk does the piece rate carry? Anya earns 210 × £3 = £630. Ben earns 40 × £12 = £480, so Anya earns £150 more. But paying for each item made tempts workers to rush, so quality may fall and more items are rejected - which is why a piece rate usually has to be paired with quality checks. Show the calculation, then judge it: a question that asks who earns more and for an evaluation gives marks for the number and for the drawback.
Non-financial methods of motivation
These motivate without extra money.
job rotation 工作轮换 — workers switch between different tasks, so work is less boring.
job enlargement 工作扩大化 — adding more tasks at the same level.
job enrichment 工作丰富化 — giving more challenging tasks and more responsibility.
autonomy 自主权 — letting workers make some of their own decisions.
teamworking 团队合作 — working in small groups.
training 培训 and chances for promotion 晋升 — helping workers improve and move up.
Explore · 探索
Maslow's hierarchy of needs · マ斯洛の欲求階層説
People are motivated by a ladder of needs — a business motivates staff by helping them up it. · 人間はニーズの階段によって動機付けられ、企業はスタッフがそれを登れるよう支援することで staff を動機付ける。
draw and interpret simple organisational charts; explain hierarchy, chain of command, span of control and delayering
explain the role and functions of management (planning, organising, coordinating, commanding, controlling)
describe leadership styles: autocratic, democratic and laissez-faire, and when each is appropriate
explain the role of trade unions in business
日本語
簡単な組織図を描き解釈し、階層構造、指揮系統、管理範囲、デレイヤリングについて説明する
経営の役割と機能(計画、組織化、調整、指導、統制)について説明する
リーダーシップスタイル(権威主義、民主主義、放任主義)とその適切な使用場面を説明する
企業の労働組合の役割について説明する
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
Organisational charts
An organisational chart 组织结构图 is a diagram that shows how a business is organised — who reports to whom. It shows several ideas:
hierarchy 层级 — the levels of staff, from the top down.
chain of command 指挥链 — the line along which orders pass down from managers to workers.
span of control 管理幅度 — the number of subordinates 下属 (people directly below) that one manager controls.
delayering 扁平化 — removing one or more levels to cut costs and speed up messages.
A long chain of command (a "tall" structure) slows messages down. A wide span of control gives one manager many people to watch.
Functions of management
The five main jobs (functions) of management 管理 are:
planning 计划 — setting aims and deciding how to reach them,
organising 组织 — arranging people and resources,
coordinating 协调 — making different parts work together,
commanding 指挥 — giving instructions and guiding staff,
controlling 控制 — checking that targets are met.
Leadership styles
A leadership style 领导风格 is the way a manager leads people.
Style
How it works
Best when
autocratic 专制型
the leader decides alone and gives orders
a crisis, or with new and untrained staff
democratic 民主型
the leader asks staff for ideas before deciding
staff are skilled and want a say
laissez-faire 放任型
the leader sets goals, then lets staff work freely
creative, expert teams
Trade unions
A trade union 工会 is a group of workers who join together to protect their shared interests. A union can bargain for better pay and conditions, support a worker in a dispute, and push for safer work.
日本語
Managers organise and lead the workforce so the business meets its objectives.
Organisational charts
An organisational chart 组织结构图 is a diagram that shows how a business is organised — who reports to whom. It shows several ideas:
hierarchy 层级 — the levels of staff, from the top down.
chain of command 指挥链 — the line along which orders pass down from managers to workers.
span of control 管理幅度 — the number of subordinates 下属 (people directly below) that one manager controls.
delayering 扁平化 — removing one or more levels to cut costs and speed up messages.
A long chain of command (a "tall" structure) slows messages down. A wide span of control gives one manager many people to watch.
An organisation chart shows the chain of command and each manager's span of control
Functions of management
The five main jobs (functions) of management 管理 are:
planning 计划 — setting aims and deciding how to reach them,
organising 组织 — arranging people and resources,
coordinating 协调 — making different parts work together,
commanding 指挥 — giving instructions and guiding staff,
controlling 控制 — checking that targets are met.
Leadership styles
A leadership style 领导风格 is the way a manager leads people.
Style
How it works
Best when
autocratic 专制型
the leader decides alone and gives orders
a crisis, or with new and untrained staff
democratic 民主型
the leader asks staff for ideas before deciding
staff are skilled and want a say
laissez-faire 放任型
the leader sets goals, then lets staff work freely
creative, expert teams
Trade unions
A trade union 工会 is a group of workers who join together to protect their shared interests. A union can bargain for better pay and conditions, support a worker in a dispute, and push for safer work.
Explore · 探索
Choose the ownership form · 所有形態を選択する
Compare ownership, control and liability in real business types. · 実際のビジネスタイプにおける所有、管理、責任を比較せよ。
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
The recruitment process
Recruitment 招聘 is finding and attracting people to apply for a job. Selection 选拔 is choosing the best person from those who apply. The process starts with three documents:
job analysis 工作分析 — studying what the job involves,
job description 工作描述 — a list of the duties and tasks of the job,
person specification 人员规格 — the skills, qualities and qualifications the right person needs.
Internal and external recruitment
Internal recruitment 内部招聘 fills the job with someone already in the business. It is cheaper and quicker, and the person is already known, but it brings in no new ideas.
External recruitment 外部招聘 fills the job from outside. It brings new ideas and skills, but it costs more and takes longer.
Common selection methods include the application form 申请表, the CV 简历 (a short summary of a person's education and work history), the interview 面试, and skills tests 测试.
Training
Training improves workers' skills. There are three main types.
induction training 入职培训 — given to new workers, to learn about the business and their role.
on-the-job training 在职培训 — learning while doing the job, beside an experienced worker.
off-the-job training 脱产培训 — learning away from the workplace, for example at a college.
Type
Benefits
Limitations
on-the-job
cheap; uses real tasks
the trainer stops their own work; bad habits can pass on
off-the-job
expert teaching; no work distractions
costs more; the skills may not fit the exact job
Reducing the workforce
Sometimes a business must cut staff numbers.
Redundancy 裁员 — the job is no longer needed, for example because a machine now does it. It is not the worker's fault.
Dismissal 解雇 — the worker is removed for a good reason, such as breaking rules or poor work.
Most countries have employment laws 劳动法 that protect workers. They cover a fair contract of employment 雇佣合同, safe conditions, fair pay, and protection from being sacked unfairly.
日本語
A business must recruit, train and motivate enough people with the right skills.
The recruitment process
Recruitment 招聘 is finding and attracting people to apply for a job. Selection 选拔 is choosing the best person from those who apply. The process starts with three documents:
job analysis 工作分析 — studying what the job involves,
job description 工作描述 — a list of the duties and tasks of the job,
person specification 人员规格 — the skills, qualities and qualifications the right person needs.
The steps of recruitment and selection, from analysing the job to choosing the best person
Internal and external recruitment
Internal recruitment 内部招聘 fills the job with someone already in the business. It is cheaper and quicker, and the person is already known, but it brings in no new ideas.
External recruitment 外部招聘 fills the job from outside. It brings new ideas and skills, but it costs more and takes longer.
Common selection methods include the application form 申请表, the CV 简历 (a short summary of a person's education and work history), the interview 面试, and skills tests 测试.
Training
Training improves workers' skills. There are three main types.
induction training 入职培训 — given to new workers, to learn about the business and their role.
on-the-job training 在职培训 — learning while doing the job, beside an experienced worker.
off-the-job training 脱产培训 — learning away from the workplace, for example at a college.
Type
Benefits
Limitations
on-the-job
cheap; uses real tasks
the trainer stops their own work; bad habits can pass on
off-the-job
expert teaching; no work distractions
costs more; the skills may not fit the exact job
Reducing the workforce
Sometimes a business must cut staff numbers.
Redundancy 裁员 — the job is no longer needed, for example because a machine now does it. It is not the worker's fault.
Dismissal 解雇 — the worker is removed for a good reason, such as breaking rules or poor work.
Most countries have employment laws 劳动法 that protect workers. They cover a fair contract of employment 雇佣合同, safe conditions, fair pay, and protection from being sacked unfairly.
Explore · 探索
Human resources decision lab · 人事判断ラベル
Classify HR actions by the job they do inside the workforce. · workforce(労働力)内の役割に基づき、HR行動を分類せよ。
explain the importance of effective communication and the features of good communication
compare one-way and two-way communication and internal and external communication
describe communication methods and barriers to effective communication and how to reduce them
日本語
効果的なコミュニケーションの重要性と良好なコミュニケーションの特徴について説明する
一方向性と双方向性のコミュニケーション、および内部・外部コミュニケーションを比較する
コミュニケーションの方法、効果的なコミュニケーションの障壁、およびそれらを減少させる方法を説明する
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
Why communication matters
Good communication 沟通 means information is sent, received and understood correctly. It helps workers know what to do, cuts mistakes, and makes people feel valued.
The communication process has five parts: a sender 发送者, a message 信息, a medium 媒介 (the way it is sent), a receiver 接收者, and feedback 反馈 (the receiver's reply, which shows the message was understood).
Types of communication
One-way communication 单向沟通 — information flows in one direction only, with no reply (for example, a public notice).
Two-way communication 双向沟通 — the receiver can reply and give feedback. It is usually better, because it checks understanding.
Internal communication 内部沟通 — between people inside the business.
External communication 外部沟通 — between the business and outside people, like customers 顾客 or suppliers 供应商.
Barriers to communication
A communication barrier 沟通障碍 is anything that stops a message getting through clearly. Common barriers include:
a message that is too long or unclear,
a poor medium, such as a weak phone line,
language differences between sender and receiver,
a receiver who is not paying attention.
To reduce barriers: keep messages short and clear, choose the right medium, and ask for feedback to check the message was understood.
日本語
Why communication matters
Good communication 沟通 means information is sent, received and understood correctly. It helps workers know what to do, cuts mistakes, and makes people feel valued.
The communication process has five parts: a sender 发送者, a message 信息, a medium 媒介 (the way it is sent), a receiver 接收者, and feedback 反馈 (the receiver's reply, which shows the message was understood).
The message flows from sender to receiver, and feedback confirms it was understood
Types of communication
One-way communication 单向沟通 — information flows in one direction only, with no reply (for example, a public notice).
Two-way communication 双向沟通 — the receiver can reply and give feedback. It is usually better, because it checks understanding.
Internal communication 内部沟通 — between people inside the business.
External communication 外部沟通 — between the business and outside people, like customers 顾客 or suppliers 供应商.
Barriers to communication
A communication barrier 沟通障碍 is anything that stops a message getting through clearly. Common barriers include:
a message that is too long or unclear,
a poor medium, such as a weak phone line,
language differences between sender and receiver,
a receiver who is not paying attention.
To reduce barriers: keep messages short and clear, choose the right medium, and ask for feedback to check the message was understood.
Explore · 探索
Communication route lab · コミュニケーションルート実験
Watch a message move from sender to feedback and see where noise can enter. · メッセージが送信者からフィードバックまで移動する様子を見、ノイズが入り得る箇所を確認する。
Link motivation to its benefits: higher productivity, lower absenteeism, and lower labour turnover.
Match each theory: Taylor (pay / piece rate), Maslow (a hierarchy of needs — lower needs before higher), Herzberg (hygiene factors stop unhappiness; motivators drive real effort).
Separate financial methods (wage, piece rate, salary, commission, bonus) from non-financial ones (job rotation, job enlargement, job enrichment, autonomy).
On an organisation chart, know the chain of command (the line orders travel down) and the span of control (how many people report to one manager).
Distinguish redundancy (the job is no longer needed — not the worker's fault) from dismissal (the worker is removed for a reason such as breaking rules).
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
Marketing 营销 is the work of finding out what customers 顾客 want, then making, pricing, selling and promoting products to meet those wants at a profit.
Marketing has several roles:
find out and satisfy what customers want,
keep and increase sales 销售额 and market share 市场份额,
build customer loyalty 顾客忠诚度 so buyers come back again.
Why customers matter
Customers bring in the money, so keeping them is vital. Losing customers is costly: the business loses their future spending, and it must spend a lot on advertising 广告 to win new ones. It is usually far cheaper to keep a customer than to find a new one.
Niche and mass markets
A market 市场 is all the buyers and sellers of a product.
A niche market 利基市场 is a small part of a market with special needs, for example left-handed tools.
A mass market 大众市场 is a large market with many similar buyers, for example soft drinks.
Market segmentation
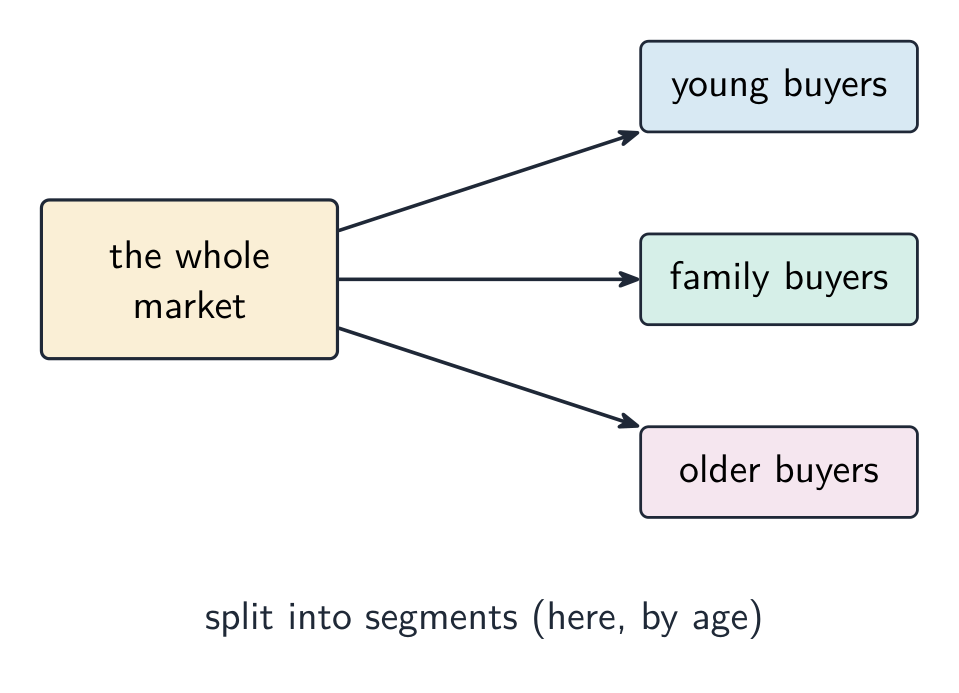
Market segmentation 市场细分 means splitting a market into groups of buyers who share something, such as age, income, gender or location. Its benefits:
the business can design a product to fit each group,
distinguish primary (field) and secondary (desk) market research and their methods
explain sampling and the need for accurate, reliable data
present and interpret market research data (tables, charts, graphs) to support decisions
日本語
一次調査(フィールド調査)と二次調査(デスク調査)を区別し、それぞれの研究方法を説明する
サンプル抽出と、正確で信頼性の高いデータの必要性について説明する
意思決定を裏付けるための市場調査データの提示と解釈(表、グラフ、チャート)を行う
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
Market research 市场调研 is collecting information about customers, rivals and the market, to help make good decisions.
Primary and secondary research
Primary research 一手调研 (also called field research) collects new information directly, for the first time. Methods include questionnaires 问卷, interviews, surveys and tests. It is up to date and fits the exact need, but costs time and money.
Secondary research 二手调研 (also called desk research) uses information that already exists, such as government reports, websites and past sales records. It is cheap and quick, but may be old or may not fit the need.
Sampling and reliable data
A business cannot ask everyone, so it asks a small group, called a sample. Sampling 抽样 must be done with care. If the sample is too small or not typical, the data 数据 will not be reliable, and decisions based on it may be wrong.
Using research data
Research results are shown in tables, charts and graphs. You should be able to read them — for example, find the most popular product, or see how sales change over time — and use them to support a decision.
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
The product life cycle
The marketing mix 营销组合 is the four main choices a business makes about a product. They are often called the four Ps: product, price, place and promotion.
Product
The product 产品 must meet customers' needs. Two ideas matter here.
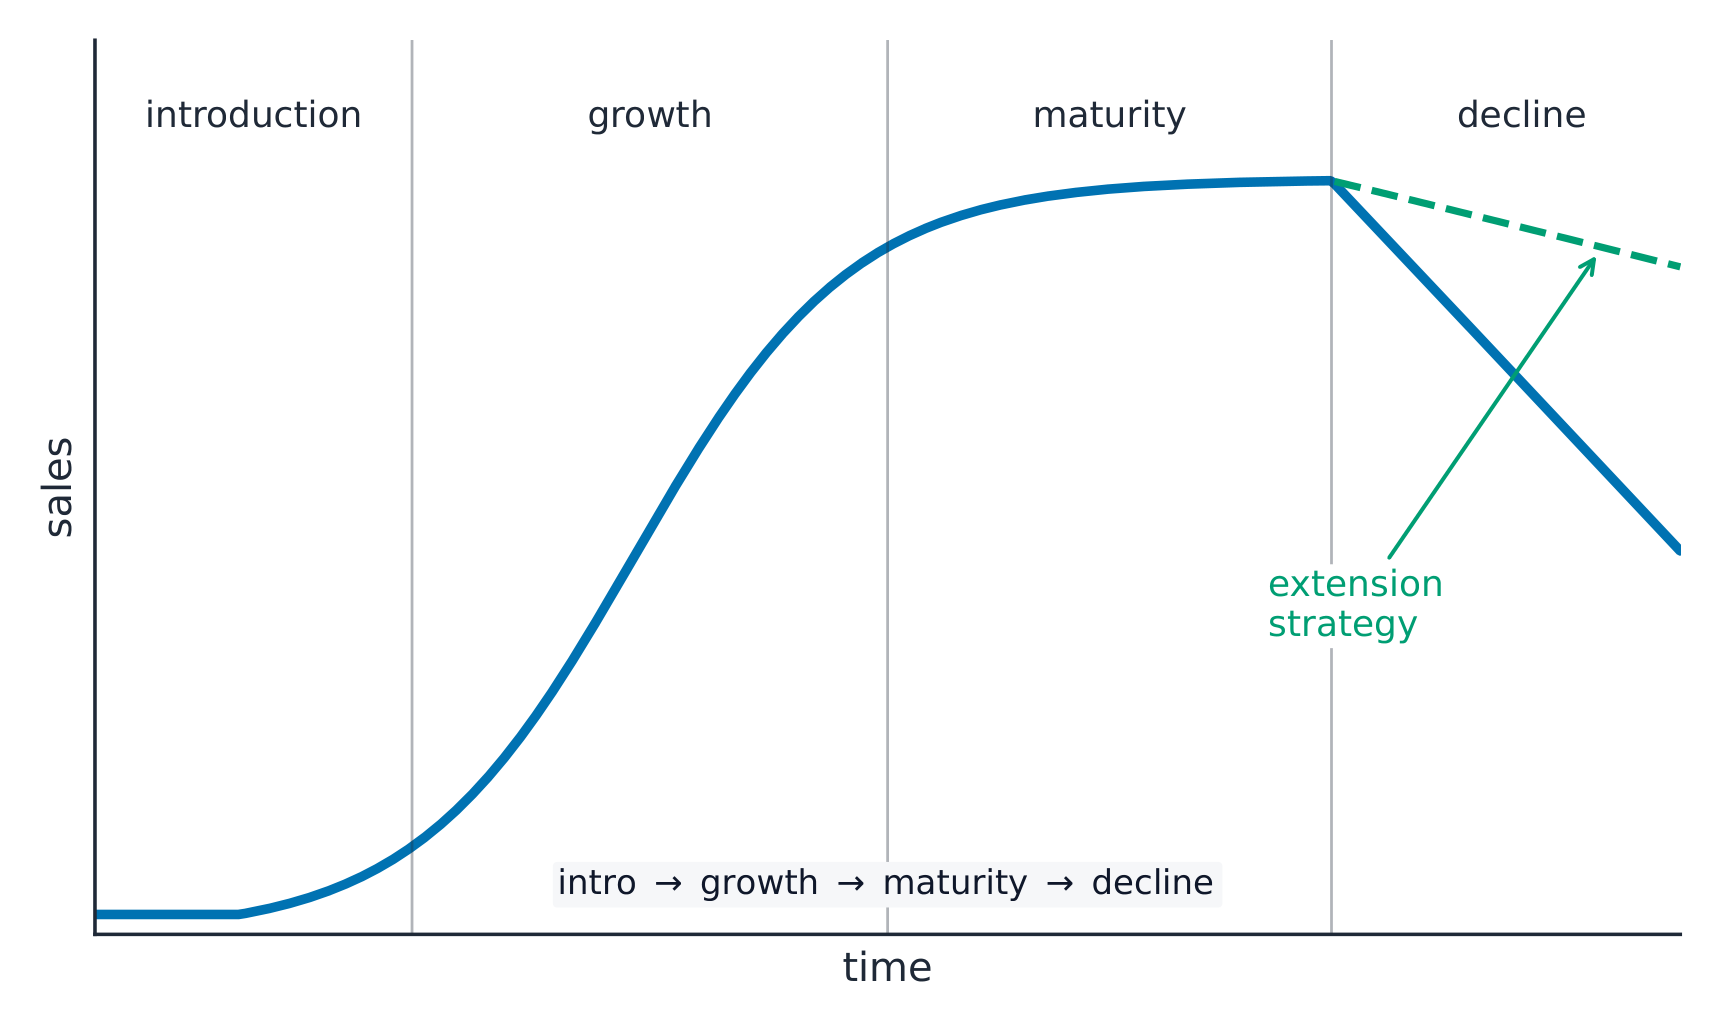
The product life cycle 产品生命周期 describes the sales of a product over time, in four stages: introduction, growth, maturity and decline. When sales begin to fall, a business can use an extension strategy 延长策略 — such as a new design, a new advert, or selling in a new market — to keep the product selling.
A strong brand 品牌 (a name, logo and image that customers recognise) and good packaging 包装 (the wrapping that protects the product and attracts buyers) both help a product sell. Building a brand is called branding.
Price
The price 价格 is what the customer pays. A business can choose from several pricing methods.
Method
How it works
cost-plus pricing 成本加成定价
add a fixed share of profit on top of the cost of making the item
penetration pricing 渗透定价
set a low price to enter a market and win customers fast
price skimming 撇脂定价
set a high price at first for a new, special product
competitive pricing 竞争定价
set a price close to rivals' prices
promotional pricing 促销定价
cut the price for a short time to lift sales
dynamic pricing 动态定价
change the price automatically as demand changes, as airlines do
The right price also depends on the cost of making the product, on what customers will pay, on rivals' prices, and on the product's stage in its life cycle.
Worked example. One firm launches a smartphone using technology no rival has. Another enters a crowded soft-drinks market. Which pricing method suits each, and why? The smartphone is new and special with no direct competition, so use price skimming: charge a high price at first to recover the development cost from customers who must have it, then lower it as rivals catch up. The soft drink faces many established rivals, so use penetration pricing: a low price wins customers quickly and buys market share, and it can be raised later. Match the method to the market conditions - a pricing strategy is only right or wrong relative to the competition and the product's stage in its life cycle.
Place
Place 地点 is about how and where the product is sold, so it reaches the customer at the right time. The route a product takes from maker to customer is called a channel of distribution 分销渠道.
Many channels use a wholesaler 批发商 (buys large amounts from makers and sells smaller amounts to shops) and a retailer 零售商 (a shop that sells to the final customer). A business can also sell directly 直销 to customers, or online through e-commerce 电子商务.
Promotion
Promotion 推广 means telling customers about a product and persuading them to buy it. It includes:
advertising — paid messages on TV, online, on posters and so on,
sales promotion 促销 — short-term offers like discounts, free gifts, or "buy one get one free".
Technology now plays a big part. The internet 互联网 and social media 社交媒体 let a business reach many people cheaply, target the right customers, and sell all over the world.
explain how a marketing mix can be used to achieve marketing objectives
explain legal controls related to marketing (consumer protection, misleading promotion)
explain the opportunities and problems of entering new markets in other countries
日本語
マーケティングミックスを用いてマーケティング目標を達成する方法について説明する
マーケティングに関連する法的規制(消費者保護、誤認誘導)について説明する
他国への新規参入における機会と課題について説明する
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
A marketing strategy 营销策略 is a plan that uses the four Ps together to reach the business's objectives 目标. The four Ps must fit each other and fit the target customers. For example, a high-price luxury product needs high-quality packaging, expensive shops and image-based adverts.
Legal controls on marketing
Many countries have legal controls 法律管制 that protect buyers:
consumer protection 消费者保护 laws stop the sale of unsafe or faulty goods,
rules ban misleading 误导 promotion — adverts that lie about what a product can do.
Selling in other countries
A business can grow by entering an international market 国际市场 in another country.
Opportunities: many more customers, higher sales, and spreading risk across markets.
Problems: different languages and tastes, higher transport costs, foreign laws and tariffs 关税 (taxes on imports), and strong local competition 竞争.
Learn the four Ps of the marketing mix — product, price, place, promotion — and remember they must fit each other and the target customer.
Primary research collects new data (surveys, questionnaires; up to date but costly); secondary research uses existing data (cheap and quick but may be out of date).
Know the product life cycle (introduction, growth, maturity, decline) and that an extension strategy revives falling sales.
Match the pricing methods: penetration (low, to enter a market), skimming (high, for a new product), plus cost-plus, competitive, promotional and dynamic pricing.
A niche market is small and specialised; a mass market is large, with many similar buyers.
describe the methods of production: job, batch and flow production, and their advantages/disadvantages
explain productivity and how it can be increased
explain lean production and just-in-time (JIT) inventory control and the management of inventory
explain how technology has changed production
日本語
製造方法(ジョブ、バッチ、フロー生産)とそのメリット・デメリットを説明する
生産性とそれを向上させる方法について説明する
リーン生産方式とジャストインタイム(JIT)在庫管理、および在庫管理について説明する
技術が製造に与えた変化について説明する
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
Stock control: the sawtooth chart
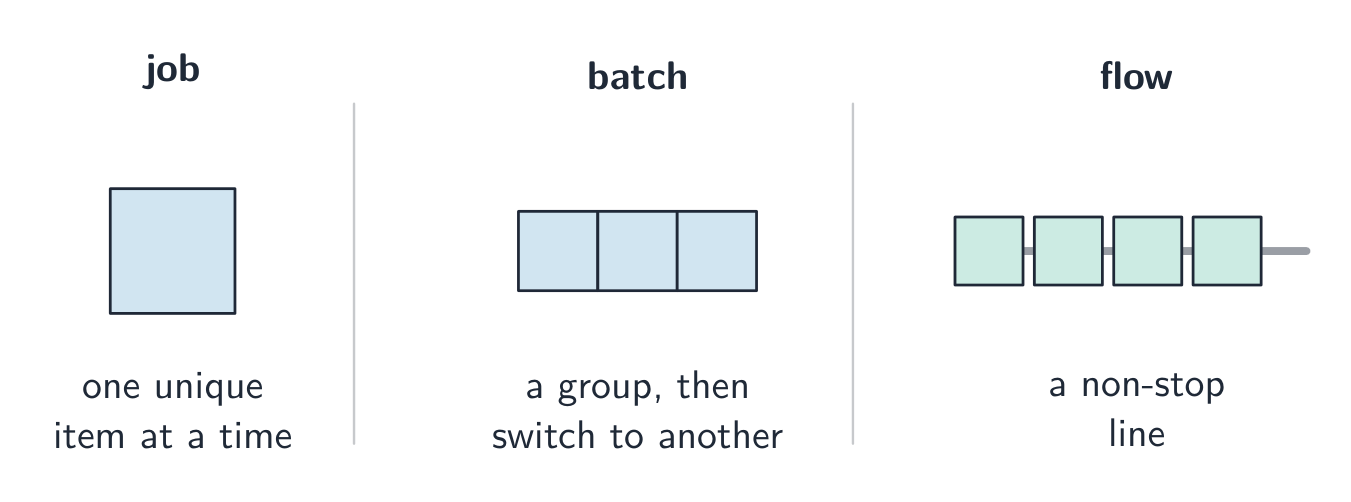
Production 生产 means turning materials and labour 劳动力 into finished goods and services 服务. There are three main methods.
Method
What it is
Good for
Drawback
job production 单件生产
making one item at a time, to order
special, one-off items: a wedding cake, a ship
slow and costly per item
batch production 批量生产
making a group of the same item, then switching to another group
bakeries, clothes in different sizes
machines stand idle while switching
flow production 流水线生产
making goods non-stop on a moving line
mass-made goods: cars, drinks
costly to set up; work can be boring
Productivity
Productivity 生产率 measures how much each worker or machine produces in a set time. Higher productivity lowers the cost per item. A business can raise productivity by:
training workers,
using better machines and technology 技术,
improving motivation 激励,
organising the work better.
Lean production and just-in-time
Lean production 精益生产 means cutting all waste — wasted time, materials, space and effort — while keeping quality.
One key method is just-in-time 准时制 (JIT). With JIT, materials arrive just as they are needed, and finished goods are sold quickly, so the business holds very little inventory 库存 (its stock of materials and goods). This saves storage cost, but one late delivery can stop production. Good management of inventory keeps enough stock to meet demand, but not so much that money is tied up or goods go out of date.
Technology in production
Technology has changed production. Automation 自动化 (machines and robots doing tasks), computer design and online ordering all make production faster, cheaper and more exact. But machines cost a lot to buy and can replace workers' jobs.
日本語
Stock control: the sawtooth chart
Production 生产 means turning materials and labour 劳动力 into finished goods and services 服务. There are three main methods.
A car assembly line: making many identical products on a moving line
Method
What it is
Good for
Drawback
job production 单件生产
making one item at a time, to order
special, one-off items: a wedding cake, a ship
slow and costly per item
batch production 批量生产
making a group of the same item, then switching to another group
bakeries, clothes in different sizes
machines stand idle while switching
flow production 流水线生产
making goods non-stop on a moving line
mass-made goods: cars, drinks
costly to set up; work can be boring
The three methods of production
Productivity
Productivity 生产率 measures how much each worker or machine produces in a set time. Higher productivity lowers the cost per item. A business can raise productivity by:
training workers,
using better machines and technology 技术,
improving motivation 激励,
organising the work better.
Productivity is output per worker in a set time; raising it lowers the cost per item
Lean production and just-in-time
Lean production 精益生产 means cutting all waste — wasted time, materials, space and effort — while keeping quality.
One key method is just-in-time 准时制 (JIT). With JIT, materials arrive just as they are needed, and finished goods are sold quickly, so the business holds very little inventory 库存 (its stock of materials and goods). This saves storage cost, but one late delivery can stop production. Good management of inventory keeps enough stock to meet demand, but not so much that money is tied up or goods go out of date.
Just-in-time holds little stock with frequent deliveries; just-in-case holds a buffer of stock
Technology in production
Technology has changed production. Automation 自动化 (machines and robots doing tasks), computer design and online ordering all make production faster, cheaper and more exact. But machines cost a lot to buy and can replace workers' jobs.
Automation: industrial robots weld and assemble car bodies — faster and more exact than by hand, but they cost a lot and replace some workers
Explore · 探索
Methods of production · 生産方法
A business picks job, batch or flow production to suit its product and order size. · 企業は製品や注文量に応じて、ジョブ、バッチ、フロー生産のいずれを選択します。
Worked example. A factory has fixed costs of £8,000 and variable costs of £2 per unit, and makes 1,000 units. Find the total cost and the average cost per unit.
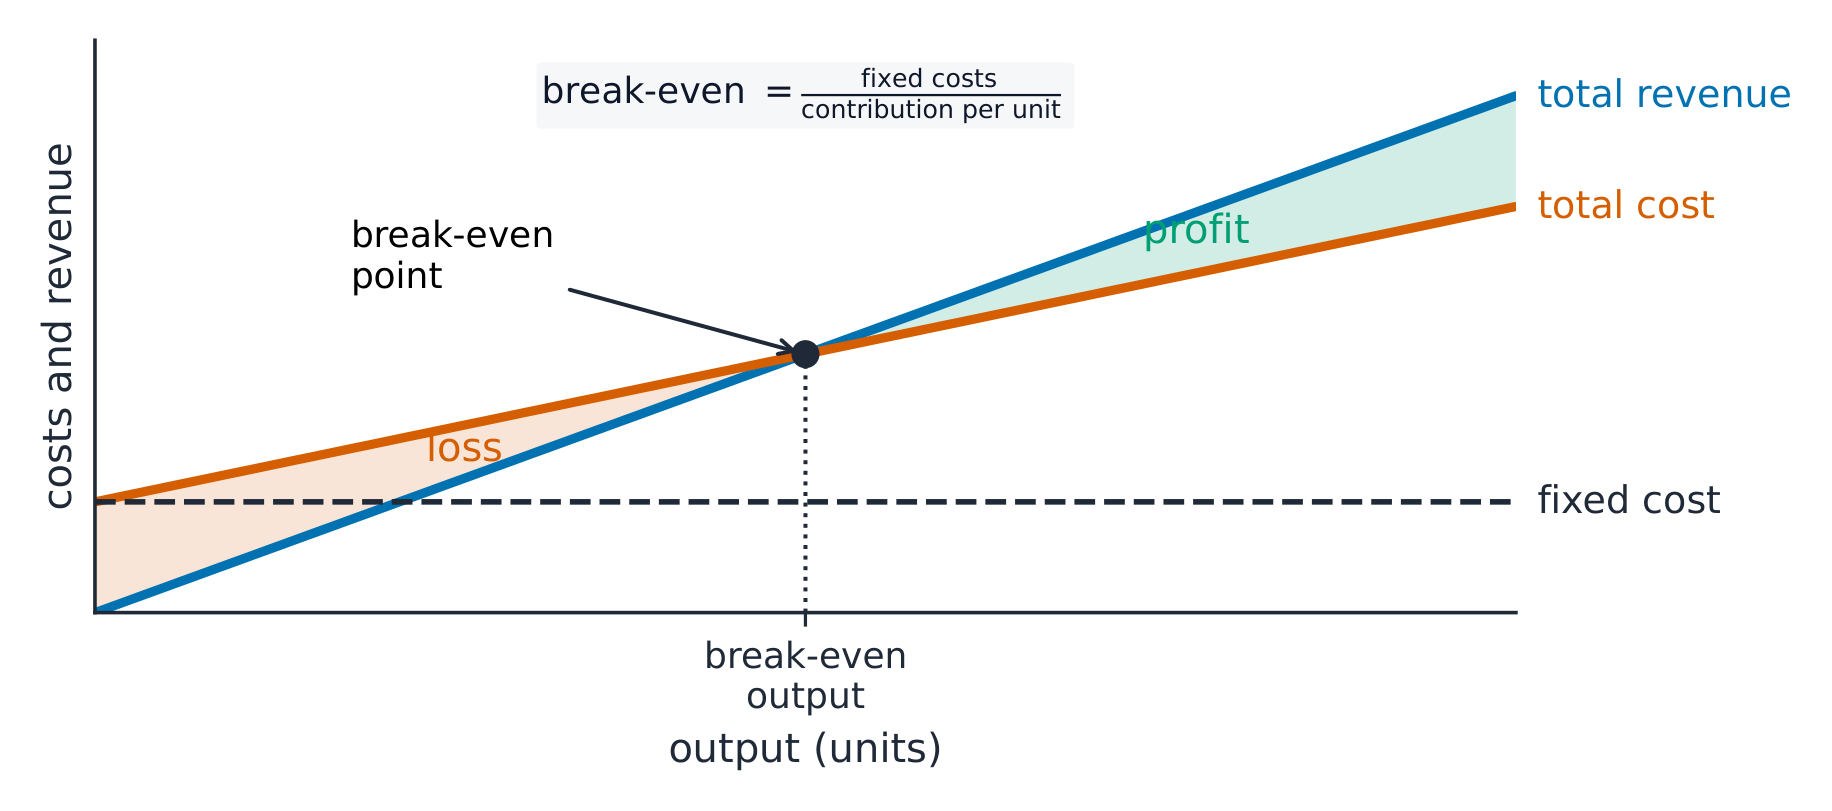
The break-even 盈亏平衡 point is the level of output where total revenue exactly equals total cost: the business makes no profit and no loss. Below it the business makes a loss; above it, a profit.
Each item sold gives an amount towards covering the fixed costs. This amount is the selling price minus the variable cost of one item (sometimes called the contribution 贡献 per unit).
$$\text{break-even output} = \frac{\text{fixed costs}}{\text{selling price per unit} - \text{variable cost per unit}}$$
A break-even chart 盈亏平衡图 plots total cost and total revenue against output. The two lines cross at the break-even point 盈亏平衡点.
The margin of safety 安全边际 is how far the actual output is above the break-even output.
$$\text{margin of safety} = \text{actual output} - \text{break-even output}$$
Worked example. A product sells for £15 with a variable cost of £5 per unit, and the firm's fixed costs are £8,000. Find the break-even output, and the margin of safety if the firm actually makes 1,200 units.
The contribution per unit is $\text{\pounds} 15 - \text{\pounds} 5 = \text{\pounds} 10$, so
A large margin of safety is safer, because sales can fall a long way before the business makes a loss.
Limits of break-even analysis. It assumes that all output is sold, and that the selling price and the costs stay the same at every level of output. In real life these often change, so break-even is only a guide.
日本語
Economies of scale: average cost fallsBreak-even analysis, built line by line
Types of cost
A business has different kinds of cost 成本.
fixed costs 固定成本 do not change with output — rent, salaries, insurance. You pay them even if you make nothing.
variable costs 可变成本 change with output 产量 — materials, and pay for each item made. More output means more variable cost.
total cost 总成本 is fixed costs plus variable costs.
average cost 平均成本 is the total cost divided by the number of items made.
Worked example. A factory has fixed costs of £8,000 and variable costs of £2 per unit, and makes 1,000 units. Find the total cost and the average cost per unit.
The break-even 盈亏平衡 point is the level of output where total revenue exactly equals total cost: the business makes no profit and no loss. Below it the business makes a loss; above it, a profit.
Each item sold gives an amount towards covering the fixed costs. This amount is the selling price minus the variable cost of one item (sometimes called the contribution 贡献 per unit).
$$\text{break-even output} = \frac{\text{fixed costs}}{\text{selling price per unit} - \text{variable cost per unit}}$$
A break-even chart 盈亏平衡图 plots total cost and total revenue against output. The two lines cross at the break-even point 盈亏平衡点.
The break-even point is where total revenue equals total cost — left of it is loss, right of it is profit
The margin of safety 安全边际 is how far the actual output is above the break-even output.
$$\text{margin of safety} = \text{actual output} - \text{break-even output}$$
Worked example. A product sells for £15 with a variable cost of £5 per unit, and the firm's fixed costs are £8,000. Find the break-even output, and the margin of safety if the firm actually makes 1,200 units.
The contribution per unit is $\text{\pounds} 15 - \text{\pounds} 5 = \text{\pounds} 10$, so
A large margin of safety is safer, because sales can fall a long way before the business makes a loss.
Limits of break-even analysis. It assumes that all output is sold, and that the selling price and the costs stay the same at every level of output. In real life these often change, so break-even is only a guide.
Explore · 探索
Break-even · 損益分岐点(Breakeven)
Break-even is where total revenue crosses total cost. · 損益分岐点とは、総収益が総原価と交差する地点である。
explain the factors affecting the location decision of a manufacturing business and a service business
explain the factors a business considers when locating in another country and the role of legal controls
日本語
製造業およびサービス企業の立地決定に影響を与える要因について説明する
他国への立地時に企業が検討する要因と法的規制の役割について説明する
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
Locating a business
Where a business sits affects its costs and its sales. A manufacturing 制造业 business (one that makes goods) looks at:
nearness to raw materials 原材料, because heavy or bulky materials cost a lot to move,
nearness to customers and the market 市场,
the cost and size of the land,
a supply of suitable labour,
good transport links,
government grants offered in some areas.
A service business (one that sells services, such as a shop or a hair salon) looks more at being close to customers, passing foot traffic, nearby shops, and the rent.
Locating in another country
A business may produce or sell abroad in order to reach new customers and bigger markets, pay lower wages or rent, get nearer to raw materials, or avoid tariffs 关税 (taxes on imports) by making goods inside the country. But it must then deal with different laws, languages and customs, and follow the legal controls 法律管制 of both countries.
日本語
Where a business locates — like this distribution centre — affects its costs and service.
Locating a business
Where a business sits affects its costs and its sales. A manufacturing 制造业 business (one that makes goods) looks at:
nearness to raw materials 原材料, because heavy or bulky materials cost a lot to move,
nearness to customers and the market 市场,
the cost and size of the land,
a supply of suitable labour,
good transport links,
government grants offered in some areas.
A service business (one that sells services, such as a shop or a hair salon) looks more at being close to customers, passing foot traffic, nearby shops, and the rent.
Locating in another country
A business may produce or sell abroad in order to reach new customers and bigger markets, pay lower wages or rent, get nearer to raw materials, or avoid tariffs 关税 (taxes on imports) by making goods inside the country. But it must then deal with different laws, languages and customs, and follow the legal controls 法律管制 of both countries.
Explore · 探索
Location factor lab · 立地要因ラボ
Classify why a business chooses one site over another. · ビジネスがなぜある立地を選好するのかを分類してください。
Match the production methods: job (one-off items to order), batch (a group, then switch to another), flow (non-stop mass production on a line).
Learn the formulas: total cost = fixed + variable; average cost = total cost ÷ output; total revenue = price × quantity; profit = total revenue − total cost.
Break-even output = fixed costs ÷ (selling price − variable cost per unit). How far actual output is above break-even is the margin of safety.
Break-even analysis assumes everything made is sold at one fixed price and cost, so it is only a guide.
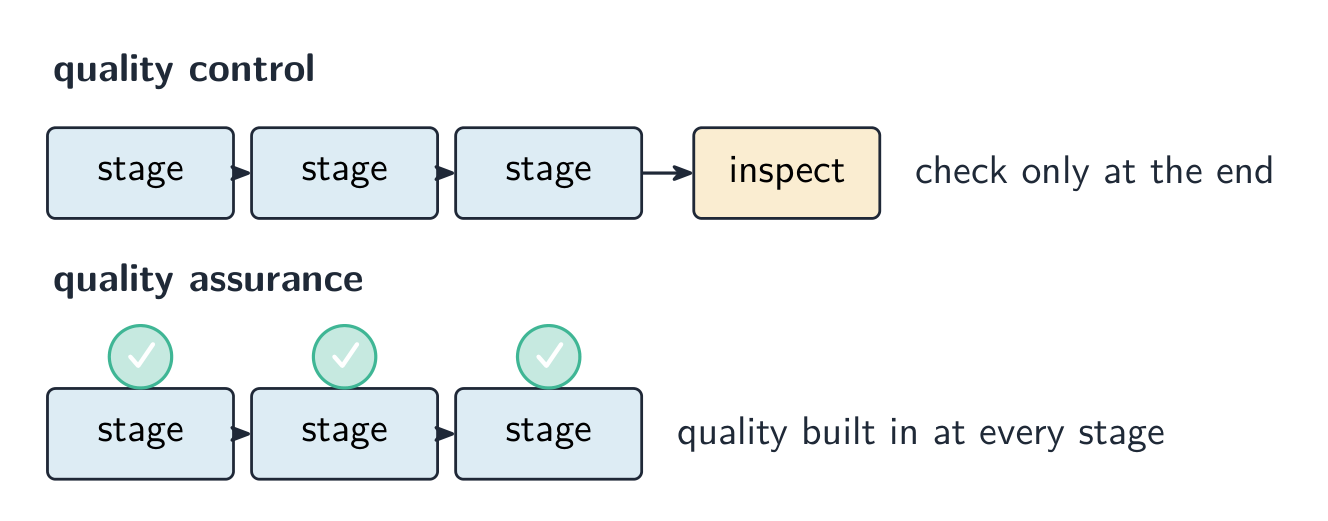
Quality control checks finished goods at the end; quality assurance builds quality in at every stage.
explain why businesses need finance (start-up capital, expansion, working capital, cash-flow problems)
distinguish short-term and long-term finance and internal and external sources of finance
describe sources of finance (retained profit, sale of assets, owners' savings, bank loan/overdraft, share issue, debentures, leasing, hire purchase, trade credit, microfinance, crowdfunding, government grants)
explain the factors that influence the choice of source of finance
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
Finance 资金 means the money a business needs. A business needs finance to:
start up — start-up capital 启动资金 to buy equipment and stock before it earns anything,
grow — money for expansion 扩张, such as new shops or machines,
run day to day — working capital 营运资金 to pay wages and suppliers while waiting for customers to pay,
survive a cash-flow 现金流 problem, when more money is going out than is coming in.
Sources of finance
Finance can be short-term 短期 (paid back within a year) or long-term 长期 (over several years). It can come from inside the business (internal) or from outside (external).
Source
Internal / external
Notes
retained profit 留存利润
internal
profit kept in the business, not paid out
sale of assets 资产
internal
selling things the business no longer needs
owners' savings
internal
the owners' own money
bank loan 贷款
external
borrowed money, repaid with interest 利息 over time
bank overdraft 透支
external
the bank lets the account go below zero, for short-term needs
issuing new shares 股份
external
only for limited companies; raises money but shares out control
debentures 债券
external
long-term loans to a company that pay interest
leasing 租赁
external
renting equipment instead of buying it
hire purchase 分期付款
external
buy now and pay in monthly parts
trade credit 贸易信贷
external
pay suppliers later, for example after 30 days
microfinance 小额信贷
external
small loans for tiny businesses in poorer areas
crowdfunding 众筹
external
many people each give a small amount, often online
government grants 补助金
external
money from the government that need not be repaid
Choosing a source
The best source depends on how much money is needed and for how long, the cost (interest and fees), the size and legal type of the business (only companies can sell shares), and how much risk and control the owners will accept.
日本語
Banks are a key external source of business finance, through loans and overdrafts.Finance is needed to start up, to run day-to-day, and to grow
Finance 资金 means the money a business needs. A business needs finance to:
start up — start-up capital 启动资金 to buy equipment and stock before it earns anything,
grow — money for expansion 扩张, such as new shops or machines,
run day to day — working capital 营运资金 to pay wages and suppliers while waiting for customers to pay,
survive a cash-flow 现金流 problem, when more money is going out than is coming in.
Sources of finance
Finance can be short-term 短期 (paid back within a year) or long-term 长期 (over several years). It can come from inside the business (internal) or from outside (external).
Source
Internal / external
Notes
retained profit 留存利润
internal
profit kept in the business, not paid out
sale of assets 资产
internal
selling things the business no longer needs
owners' savings
internal
the owners' own money
bank loan 贷款
external
borrowed money, repaid with interest 利息 over time
bank overdraft 透支
external
the bank lets the account go below zero, for short-term needs
issuing new shares 股份
external
only for limited companies; raises money but shares out control
debentures 债券
external
long-term loans to a company that pay interest
leasing 租赁
external
renting equipment instead of buying it
hire purchase 分期付款
external
buy now and pay in monthly parts
trade credit 贸易信贷
external
pay suppliers later, for example after 30 days
microfinance 小额信贷
external
small loans for tiny businesses in poorer areas
crowdfunding 众筹
external
many people each give a small amount, often online
government grants 补助金
external
money from the government that need not be repaid
Sources of finance come from inside the business (internal) or outside it (external)
Choosing a source
The best source depends on how much money is needed and for how long, the cost (interest and fees), the size and legal type of the business (only companies can sell shares), and how much risk and control the owners will accept.
Explore · 探索
Sources of finance lab
Choose the best type of finance by time, risk and ownership.
explain the importance of cash and the difference between cash and profit
construct, complete and interpret a cash-flow forecast (inflows, outflows, net cash flow, opening/closing balance)
explain working capital and how a business can overcome cash-flow problems
日本語
現金の重要性と、現金と利益の違いについて説明する
キャッシュフロー予測(収入、支出、正味キャッシュフロー、期首・期末残高)を作成・完成・解釈する
運転資金とは何か、および企業がキャッシュフロー問題を解決する方法について説明する
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
Cash-flow forecast
Cash is not the same as profit
Cash 现金 is the money a business can use right now. Profit 利润 is revenue 收入 minus costs over a period. A business can be making a profit yet still run out of cash — for example, if customers have not paid yet. Running out of cash can force even a profitable business to close.
The cash-flow forecast
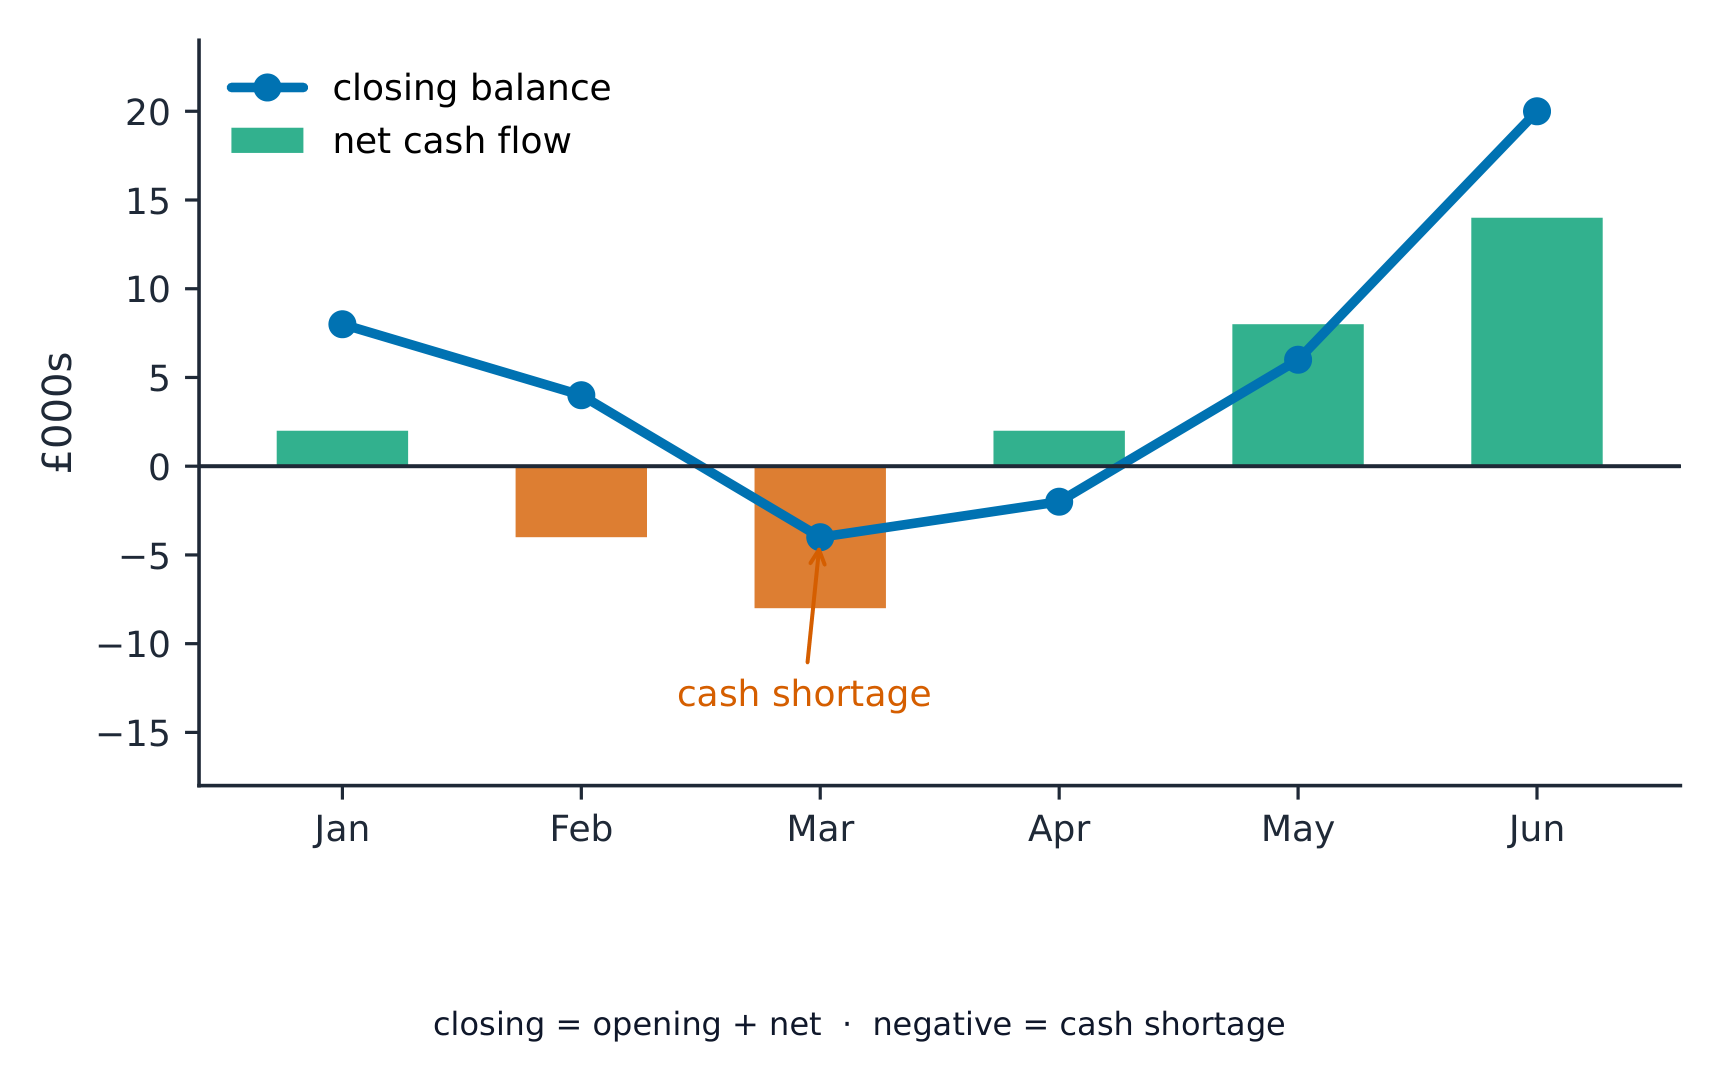
A cash-flow forecast 现金流预测 predicts the money coming in and going out each month. It uses:
inflows 流入 — money coming in (sales, loans),
outflows 流出 — money going out (wages, rent, materials),
net cash flow 净现金流 — inflows minus outflows,
opening balance 期初余额 — the cash held at the start of the month,
closing balance 期末余额 — the cash held at the end of the month.
Worked example. A shop expects inflows of £12,000 and outflows of £9,000 next month, and starts the month with £2,000 in the bank. Find the net cash flow and the closing balance.
Working capital is the money available for day-to-day running. It is the current assets 流动资产 (cash and things soon turned into cash) minus the current liabilities 流动负债 (debts due within a year).
To overcome cash-flow problems, a business can arrange an overdraft, delay paying suppliers, ask customers to pay sooner, sell spare assets, or cut spending.
日本語
Cash-flow forecast
Cash is not the same as profit
Cash 现金 is the money a business can use right now. Profit 利润 is revenue 收入 minus costs over a period. A business can be making a profit yet still run out of cash — for example, if customers have not paid yet. Running out of cash can force even a profitable business to close.
A credit sale earns profit on paper now - the cash arrives much later
The cash-flow forecast
A cash-flow forecast 现金流预测 predicts the money coming in and going out each month. It uses:
inflows 流入 — money coming in (sales, loans),
outflows 流出 — money going out (wages, rent, materials),
net cash flow 净现金流 — inflows minus outflows,
opening balance 期初余额 — the cash held at the start of the month,
closing balance 期末余额 — the cash held at the end of the month.
Worked example. A shop expects inflows of £12,000 and outflows of £9,000 next month, and starts the month with £2,000 in the bank. Find the net cash flow and the closing balance.
A cash-flow forecast tracks the closing balance each month, warning of a shortage early
Working capital
Working capital is the money available for day-to-day running. It is the current assets 流动资产 (cash and things soon turned into cash) minus the current liabilities 流动负债 (debts due within a year).
To overcome cash-flow problems, a business can arrange an overdraft, delay paying suppliers, ask customers to pay sooner, sell spare assets, or cut spending.
Working capital: current assets minus current liabilities
Explore · 探索
Cash-flow forecasting
A forecast of cash in and out each month warns a business of a cash shortage before it strikes.
Explore · 探索
Cash-flow forecast lab
Drag the monthly cash in, cash out and the one-off oven purchase — does the bakery stay out of the red all six months?
identify the main features of an income statement: revenue, cost of sales, gross profit, expenses and profit for the year
explain how income statements are used by stakeholders
日本語
損益計算書の主要な特徴(売上高、売上原価、粗利、経費、当期純利益)を特定する
関係者が損益計算書如何利用するかについて説明する
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
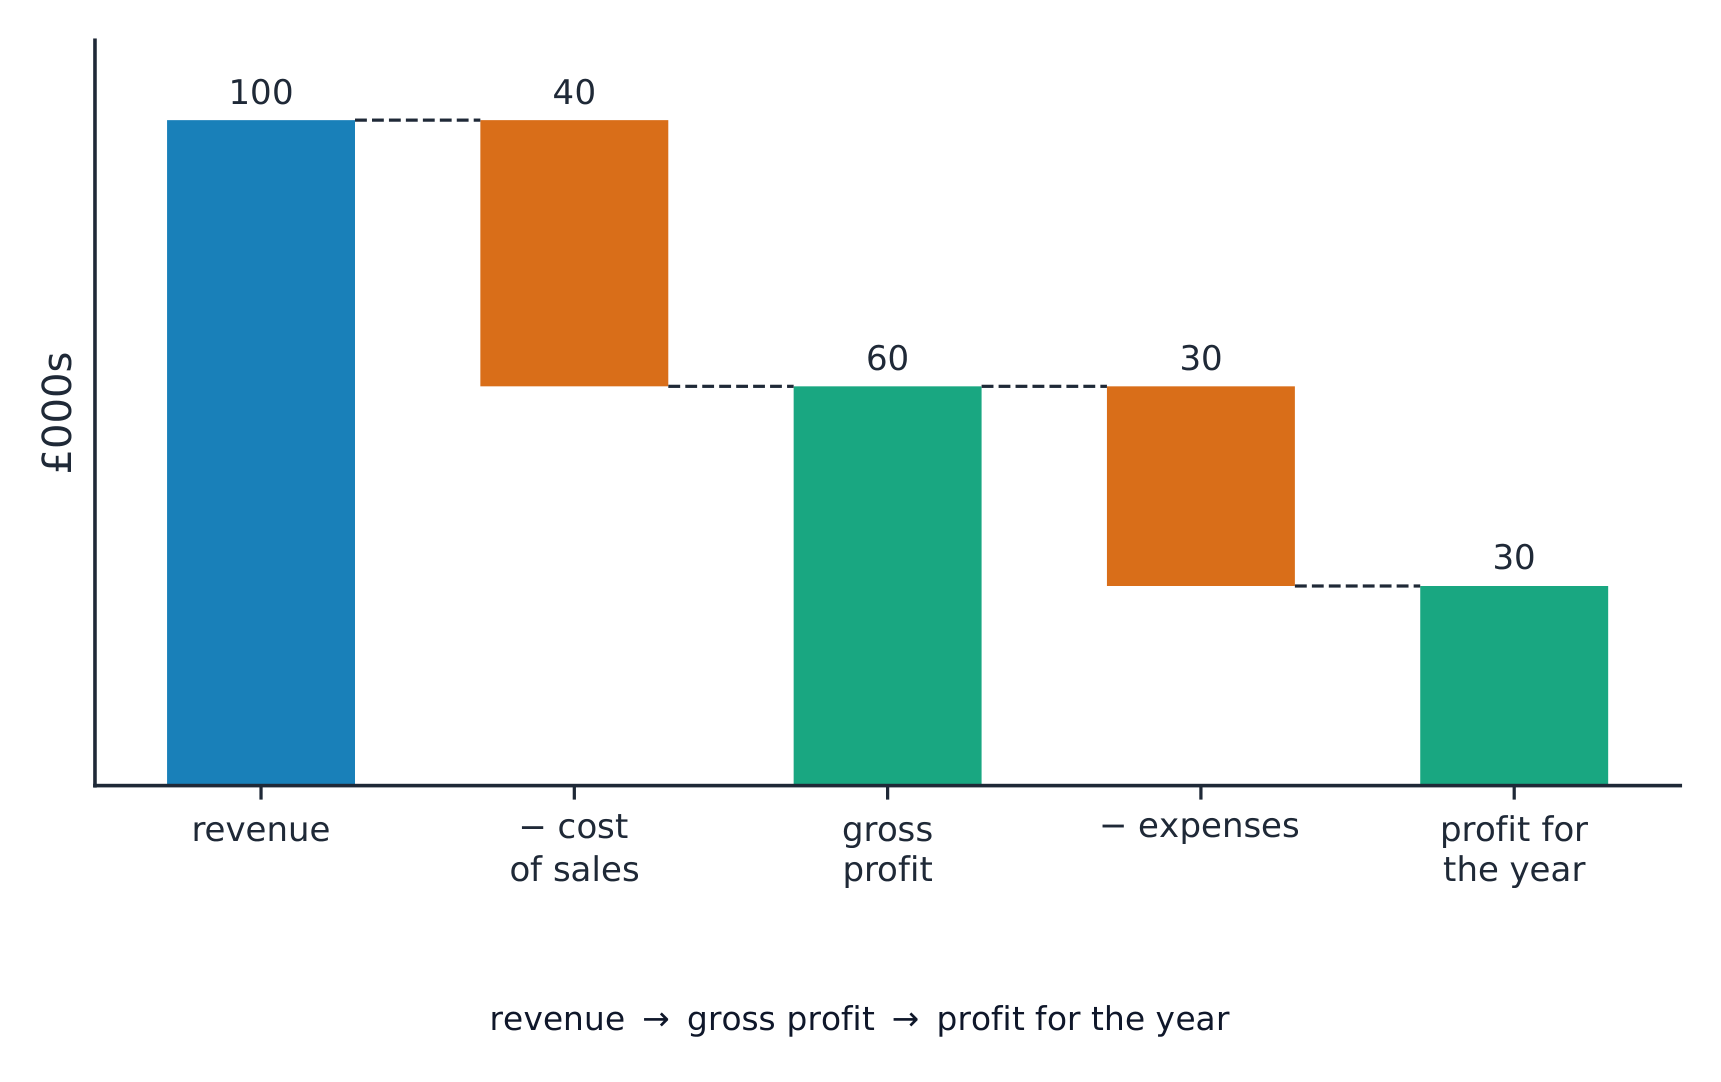
An income statement 损益表 shows how much profit a business made over a period, usually a year.
Line
Meaning
revenue
money from sales
cost of sales 销售成本
the cost of making or buying the goods that were sold
gross profit 毛利润
revenue minus cost of sales
expenses 费用
other running costs: rent, wages, advertising
profit for the year 年度利润
gross profit minus expenses
$$\text{gross profit} = \text{revenue} - \text{cost of sales}$$
$$\text{profit for the year} = \text{gross profit} - \text{expenses}$$
Worked example. A business has revenue of £200,000, cost of sales of £120,000 and expenses of £50,000. Find its gross profit and its profit for the year.
$$\text{profit for the year} = \text{\pounds} 80\,000 - \text{\pounds} 50\,000 = \text{\pounds} 30\,000$$
Income statements are used by stakeholders 利益相关者: owners check the profit, lenders check whether their loans are safe, and managers look for problems.
日本語
An income statement 损益表 shows how much profit a business made over a period, usually a year.
Line
Meaning
revenue
money from sales
cost of sales 销售成本
the cost of making or buying the goods that were sold
gross profit 毛利润
revenue minus cost of sales
expenses 费用
other running costs: rent, wages, advertising
profit for the year 年度利润
gross profit minus expenses
$$\text{gross profit} = \text{revenue} - \text{cost of sales}$$
$$\text{profit for the year} = \text{gross profit} - \text{expenses}$$
Worked example. A business has revenue of £200,000, cost of sales of £120,000 and expenses of £50,000. Find its gross profit and its profit for the year.
identify the main classifications in a statement of financial position: non-current and current assets, current and non-current liabilities, and owners' equity/capital
explain how the statement of financial position is used
gross profit margin 毛利率 — gross profit as a percentage of revenue.
profit margin 利润率 — profit for the year as a percentage of revenue.
return on capital employed 资本回报率 (ROCE) — profit as a percentage of the capital employed 所用资本 (money invested). It shows how well the investment is used.
A higher percentage is better for all three.
Worked example. The same business (revenue £200,000, gross profit £80,000, profit for the year £30,000) has capital employed of £150,000. Find its three profitability ratios.
$$\text{acid test ratio} = \frac{\text{current assets} - \text{inventory}}{\text{current liabilities}}$$
the current ratio 流动比率 compares current assets with current liabilities. Around 1.5 to 2 is healthy.
the acid test ratio 速动比率 is stricter: it leaves out inventory, because inventory is not yet sold.
Worked example. A business has current assets of £40,000 (including £10,000 of inventory) and current liabilities of £20,000. Find its current ratio and acid test ratio.
Cash is not profit: a profitable business can still run out of cash if customers pay late. Watch the closing balance on a cash-flow forecast.
Separate internal sources (retained profit, sale of assets, owners' savings) from external ones (bank loan, overdraft, shares, leasing, trade credit).
Key formulas: net cash flow = inflows − outflows; closing balance = opening balance + net cash flow; working capital = current assets − current liabilities.
Profitability ratios (gross margin, profit margin, ROCE) — higher is better. Liquidity: the current ratio (healthy ≈ 1.5–2) and the stricter acid test (which leaves out inventory).
Only limited companies can raise money by issuing shares; a sole trader or partnership cannot.
6
External influences on business activity · ビジネス活動への外部の影響
Every business is affected by external influences 外部影响 — things outside the business that it cannot control, such as the economy, the law and the environment. A good business watches these and plans for them.
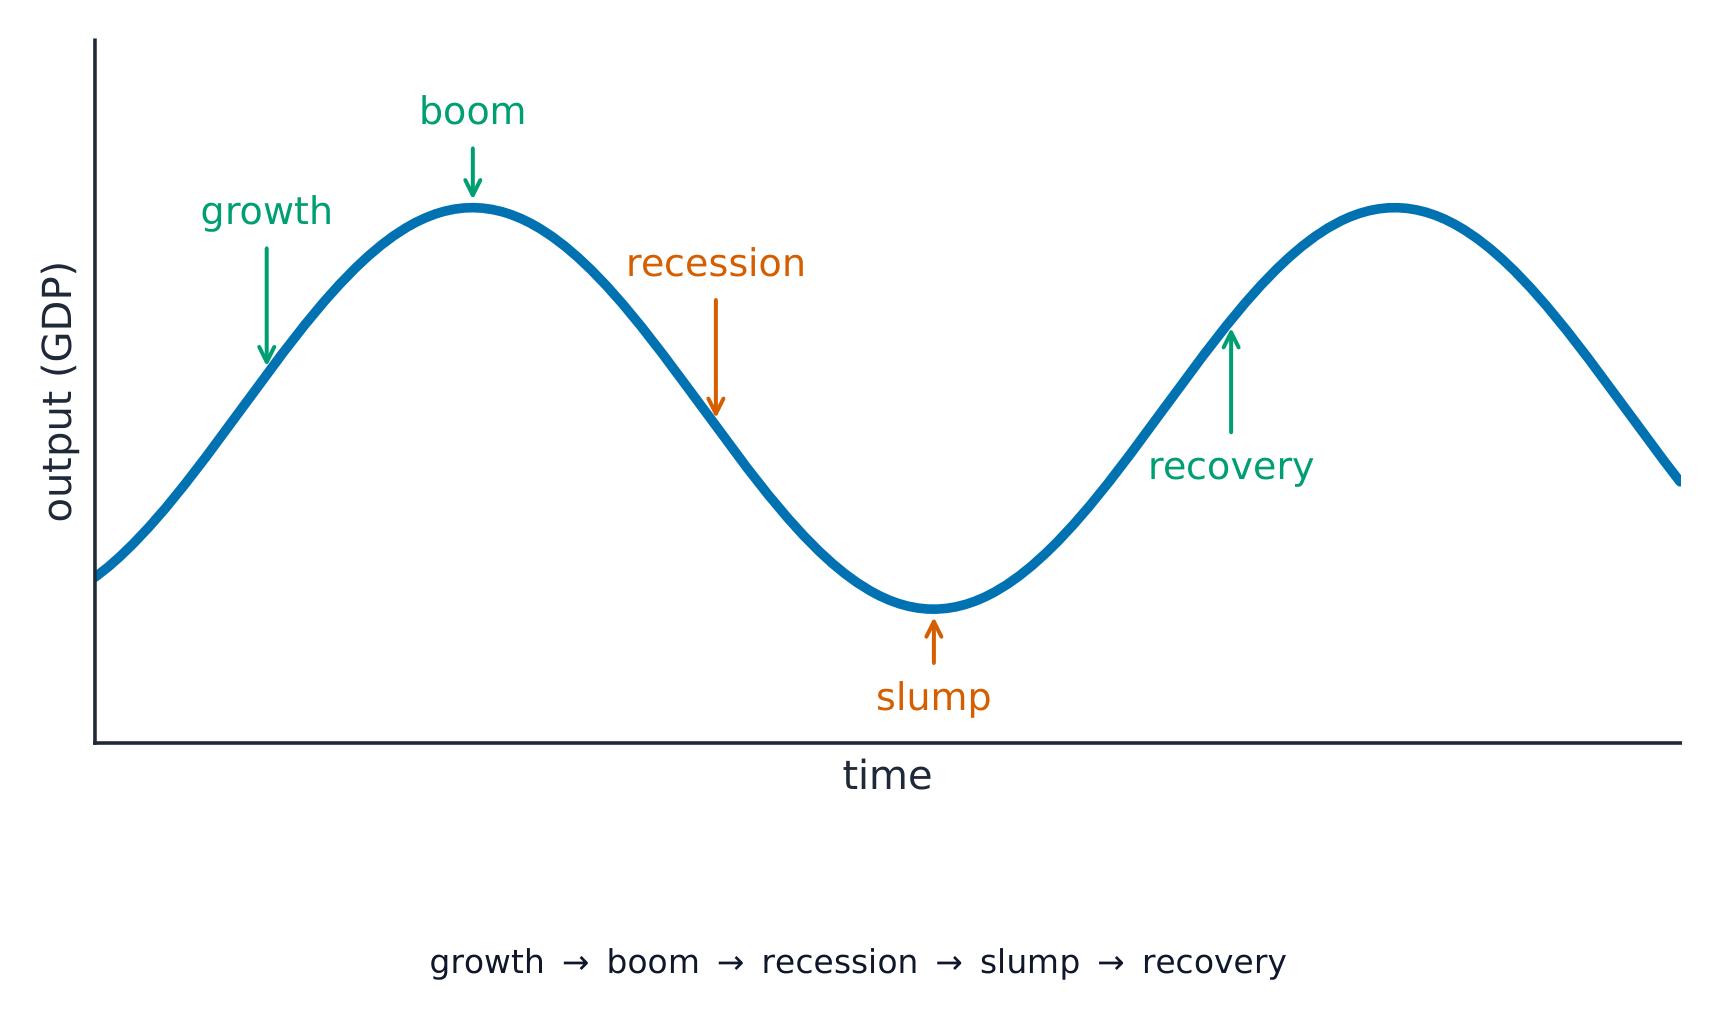
explain the business cycle (growth, boom, recession, slump/recovery) and its effects on business
explain government economic objectives and how taxation, interest rates, inflation, unemployment and exchange rates affect business
日本語
景気循環(成長、好況、不況、恐慌/回復)と、それが企業に与える影響を説明する
政府の経済目標を説明し、税制、金利、インフレ、失業、為替レートが企業にどう影響するかを説明する
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
The business cycle
The economy does not grow at a steady pace. It moves in a repeating pattern called the business cycle 经济周期, with these stages.
Stage
What happens
Effect on business
growth 增长
the economy is rising; people spend more
sales and profit rise; firms expand and hire
boom 繁荣
spending is very high
prices and wages rise; shortages appear
recession 衰退
spending falls; the economy shrinks
sales and profit fall; firms cut jobs
slump 萧条
a deep, long recession
many firms close; high unemployment 失业
recovery 复苏
spending starts to rise again
sales slowly improve
In hard times a business may cut costs, lower prices, or sell cheaper products.
Government economic aims and how they affect business
Governments try to keep the economy healthy. Their main aims are stable prices, plenty of jobs, steady growth, and a stable currency. To manage the economy, a government uses or watches several economic factors. Each one affects every business.
Economic factor
What it is
Effect on business
taxation 税收
money the government takes from incomes and sales
higher tax leaves people with less to spend, and cuts business profit
interest rates 利率
the cost of borrowing money
higher rates make loans dearer, so firms borrow and invest less, and customers spend less
inflation 通货膨胀
a general rise in prices
costs rise; if wages chase prices, the country's goods can become too dear
unemployment
the number of people without work
high unemployment lowers sales, but workers are easier to hire
exchange rates 汇率
the price of one currency in another
a change makes imports and exports cheaper or dearer (see below)
explain external costs and external benefits of business activity and the meaning of sustainable development
explain how business activity can damage or protect the environment and the role of pressure groups
explain ethical business behaviour and the possible conflict between ethics and profit
日本語
事業活動による外部コストと外部便益、および持続可能な開発の意味を説明する
事業活動が環境を損なったり保護したりする方法、および圧力集団の役割を説明する
倫理的な事業行動を説明し、倫理と利益との間の潜在的な対立を説明する
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
External costs and external benefits
When a business acts, other people can gain or lose.
external costs 外部成本 are costs paid by other people or by society, not by the business — for example pollution 污染, noise and heavy traffic.
external benefits 外部收益 are gains for others — for example new jobs and better roads.
Sustainable development
Sustainable development 可持续发展 means meeting today's needs without harming the ability of future people to meet their own needs. A business can harm the environment 环境 — through waste, pollution, and using up resources — or protect it, through recycling, clean energy and less packaging.
Pressure groups
A pressure group 压力团体 is a group that tries to influence businesses and governments, for example to cut pollution. Pressure groups use the media, protests and boycotts. A business may change its behaviour to avoid bad publicity.
Ethics and profit
Ethical behaviour 道德行为 means doing what is morally right, even when no law forces it — for example fair pay, safe products, and no child labour. Acting ethically can cost more in the short term, so it may conflict 冲突 with profit. But it can also win loyal customers and a good name, which raise profit in the long term.
Business and the international economy · 企業と国際経済
Syllabus · シラバス
English
explain globalisation, its importance to business and the reasons for it
explain the role of multinational companies and their benefits and drawbacks to a country
explain how changes in exchange rates affect businesses that import and export
日本語
グローバリゼーション、それがビジネスにとって重要な理由、およびその背景にある要因を説明する
多国籍企業の役割と、それらが一国にもたらすメリットとデメリットを説明する
為替レートの変化が輸入・輸出企業にどう影響するかを説明する
Source: Cambridge International syllabus · 出典: Cambridge International シラバス
English
Globalisation
Globalisation 全球化 is the growing trade and movement of goods, money and people between countries, so the world acts more and more like one single market. It has grown because of cheaper transport, better communication, the internet, and fewer trade barriers such as tariffs 关税 (taxes on imports).
Multinational companies
A multinational company 跨国公司 has operations — factories, branches, or offices — in more than one country. (Simply exporting to other countries is not enough; the firm must actually operate there.)
Benefits to a country
Drawbacks to a country
new jobs and training
profits may be sent out of the country
investment and new technology
local firms may be forced out of business
more choice and lower prices
resources may be used up, or the area polluted
more tax paid to the government
a large firm can have too much power
Exchange rates and trade
An exchange rate is the price of one currency in another. A change affects businesses that import 进口 (buy from abroad) and those that export 出口 (sell abroad).
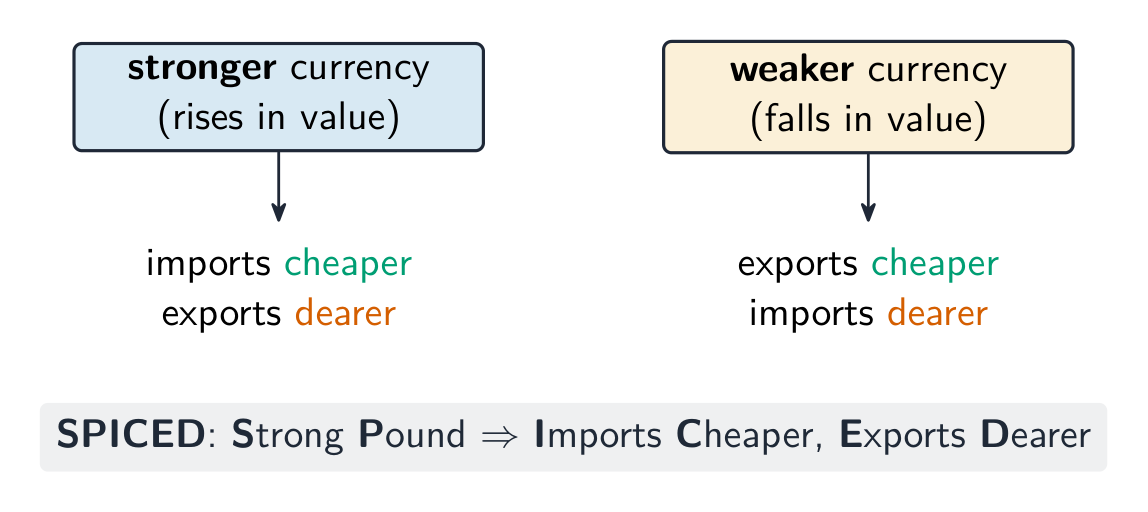
If the currency gets stronger (rises), exports become dearer for foreign buyers, so they sell less, while imports become cheaper.
If the currency gets weaker (falls), exports become cheaper and sell more, while imports become dearer.
A useful memory aid is SPICED: Strong Pound → Imports Cheaper, Exports Dearer.
Worked example. A UK firm exports a machine priced at £20,000. The exchange rate moves from £1 = 1.50 USD to £1 = 1.20 USD. What happens to the price a US buyer pays, and is that good for the exporter? Convert the UK price at each rate: at the old rate 20,000 × 1.50 = 30,000 USD; at the new rate 20,000 × 1.20 = 24,000 USD. The pound has weakened, so the machine is 6,000 USD cheaper abroad and the firm should sell more - good for an exporter. Check it against SPICED: a weak pound is the reverse of it, so exports are cheaper. Convert the actual figures rather than only reciting the mnemonic, and notice that the UK price never changed at £20,000 - it is the foreign price that moves.
Learn the business cycle (growth, boom, recession, slump, recovery) and how each stage changes sales, profit and jobs.
Trace each economic factor to the business: higher interest rates → dearer loans, so less borrowing and spending; higher tax → people have less to spend; inflation → higher costs.
External costs (pollution, noise) fall on other people, not the business; external benefits (new jobs, better roads) help others.
Use SPICED for exchange rates: Strong Pound → Imports Cheaper, Exports Dearer.
Ethical behaviour can cost more in the short term (so it may conflict with profit), but it can win loyal customers and a good name that raise profit later.
Type to search notes, lessons, code, vocabulary and past-paper questions across every subject. · すべての科目でノートImplemented、Implemented、コード、語彙、過去問問題を検索するために入力してください。