Costs of Inflation
Introduit| English | Sens |
|---|---|
| anticipated/ænˈtɪsɪpeɪtɪd/ | anticipé |
| unanticipated/ʌnænˈtɪsɪpeɪtɪd/ | non anticipé |
| lenders/ˈlendəz/ | prêteurs |
| interest/ˈɪntrest/ | intérêt |
| redistributes purchasing power/ˌriːˈdɪstrɪbjuːts ˈpɜːtʃɪsɪŋ ˈpaʊə/ | redistribue le pouvoir d'achat |
| borrowers/ˈbɒrəʊəz/ | emprunteurs |
| shoe-leather costs/ʃuː ˈleðə kɒsts/ | coûts de chaussures |
| menu costs/ˈmenjuː kɒsts/ | coûts de menu |
| savings/ˈseɪvɪŋz/ | épargne |
| pension/ˈpenʃn/ | pension |
| hyperinflation/ˌhaɪpərɪnˈfleɪʃn/ | hyperinflation |
Inflation picks winners and losers
- Inflation doesn't hurt everyone equally — and some people even gain.
- The key is whether people saw it coming.
- A surprise inflation quietly moves wealth from one group to another.
- Understanding who wins and who loses is the heart of this topic.
Anticipated vs unanticipated
- Anticipated 预期到的 inflation is expected, so people plan — workers ask for raises, lenders charge higher interest 利息. The harm is small.
- Unanticipated 未预期到的 inflation is a surprise that cannot be planned for.
- A surprise redistributes purchasing power 重新分配购买力 between borrowers 借款人 and lenders 放款人.
- Borrowers gain (they repay with cheaper money); lenders lose (the dollars back buy less).
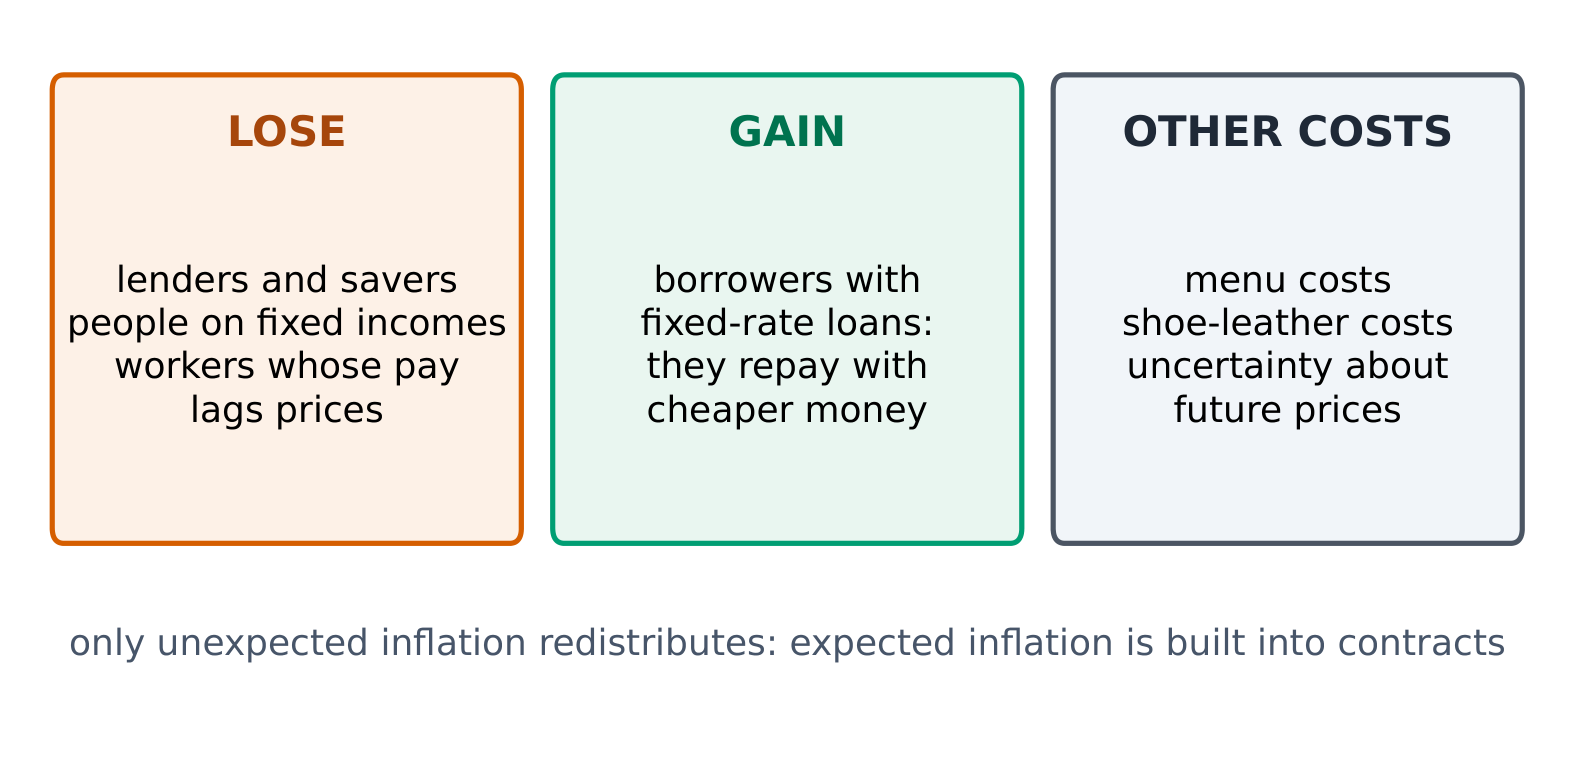
Unexpected inflation hurts lenders and fixed incomes and helps borrowers; it also brings menu and shoe-leather costs 皮鞋成本
Who gains, who loses?
Unanticipated inflation helps borrowers and hurts lenders and cash savers, and adds real costs like menu and shoe-leather costs.
Which kind of inflation does the least harm, because people can plan for it?
Difficulté 1/5 · 100 pièces + un petit bonus lors de la première réussite aujourd'hui
When inflation is expected, workers and lenders build it into wages and interest rates.
Unexpected inflation tends to:
Difficulté 1/5 · 100 pièces + un petit bonus lors de la première réussite aujourd'hui
Borrowers repay with money worth less; lenders get back dollars that buy less.
The running costs
- Menu costs 菜单成本 — the effort of changing prices: reprinting menus, tags, and catalogues.
- Shoe-leather costs — holding less cash and making more trips to the bank, because cash loses value.
- Inflation also erodes savings 储蓄 held as cash and fixed incomes like a pension 养老金.
The cost of reprinting menus, tags, and catalogues when prices change is called ______ costs.
Difficulté 1/5 · 100 pièces + un petit bonus lors de la première réussite aujourd'hui
Menu costs are the real effort of updating posted prices during inflation.
Select tout real costs that inflation imposes.
Difficulté 2/5 · 140 pièces + un petit bonus lors de la première réussite aujourd'hui
Menu costs, shoe-leather costs and eroded savings are real harms; inflation does not raise real output.
When inflation runs wild
- Worked idea. You lend 1,000 at 5%, expecting 1,050 back. But surprise inflation is 8%, so the 1,050 buys about $1{,}050 / 1.08 \approx 972$ — less than you lent.
- You (the lender) lost; your friend (the borrower) gained.
- At the extreme, hyperinflation 恶性通货膨胀 (often over 50% per month) makes money almost worthless.
- People rush to spend, savings vanish, and confidence in money collapses.
You expect 1,050 back on a loan, but inflation is 8%. In real terms the 1,050 buys about 1,050 ÷ 1.08 = how much? (round to the nearest dollar)
Difficulté 2/5 · 140 pièces + un petit bonus lors de la première réussite aujourd'hui
1,050 ÷ 1.08 ≈ 972 — less than the 1,000 you lent, so the lender loses.
Under hyperinflation, people tend to spend money quickly because it loses value fast.
Difficulté 1/5 · 100 pièces + un petit bonus lors de la première réussite aujourd'hui
Money loses value so fast that holding it is a loss — so people rush to spend it.
Worked example: the real interest rate
A bank lends at a nominal rate of 7%, expecting 3% inflation. Inflation turns out to be 9%. Who gains and who loses?
- Expected real rate = nominal − expected inflation = 7 − 3 = 4%. Actual real rate = 7 − 9 = −2%.
- The bank (lender) is repaid in dollars that buy less than it lent: it loses. The borrower gains, repaying with cheaper money. If the 9% had been anticipated, the bank would have charged about 13% instead.
The nominal interest rate is 6% and inflation is 2%. What is the real interest rate, in %?
Difficulté 2/5 · 140 pièces + un petit bonus lors de la première réussite aujourd'hui
Real ≈ nominal − inflation = 6 − 2 = 4%.
A retiree on a fixed pension is hurt by unanticipated inflation.
Difficulté 1/5 · 100 pièces + un petit bonus lors de la première réussite aujourd'hui
The pension buys less as prices rise.
Anticipated inflation does little harm; unanticipated inflation redistributes wealth — borrowers gain, lenders lose. It adds menu and shoe-leather costs and erodes cash savings. At the extreme, hyperinflation destroys the value of money.
Write from the data: find the real repayment
- A lender is repaid 900.
- Inflation over the loan was 20 percent.
A lender is repaid 900 after inflation of 20 percent. About how much buying power does that 900 have, in starting dollars, and who is hurt?
1.20 times 750 is 900.
What is the real value of the 900 repayment?
Difficulté 1/5 · 100 pièces + un petit bonus lors de la première réussite aujourd'hui
900 divided by 1.20 is 750 of starting buying power. Other options — 972 (the lesson real value); 900 (because the number of dollars did not change).