| English | 释义 | 拼音 |
|---|---|---|
| present value/ˈprezənt ˈvæljuː/ | 现值 | xiàn zhí |
| annuity/əˈnjuːɪti/ | 年金 | nián jīn |
| loan repayment/ləʊn rɪˈpeɪmənt/ | 贷款还款 | dài kuǎn hái kuǎn |
| effective rate/ɪˈfektɪv reɪt/ | 实际利率 | shí jì lì lǜ |
| nominal rate/ˈnɒmɪnl reɪt/ | 名义利率 | míng yì lì lǜ |
State what happens to the balance
- Compound growth without payments uses $A=P(1+r)^n$. A loan with repayments generally needs a changing-balance rule instead.
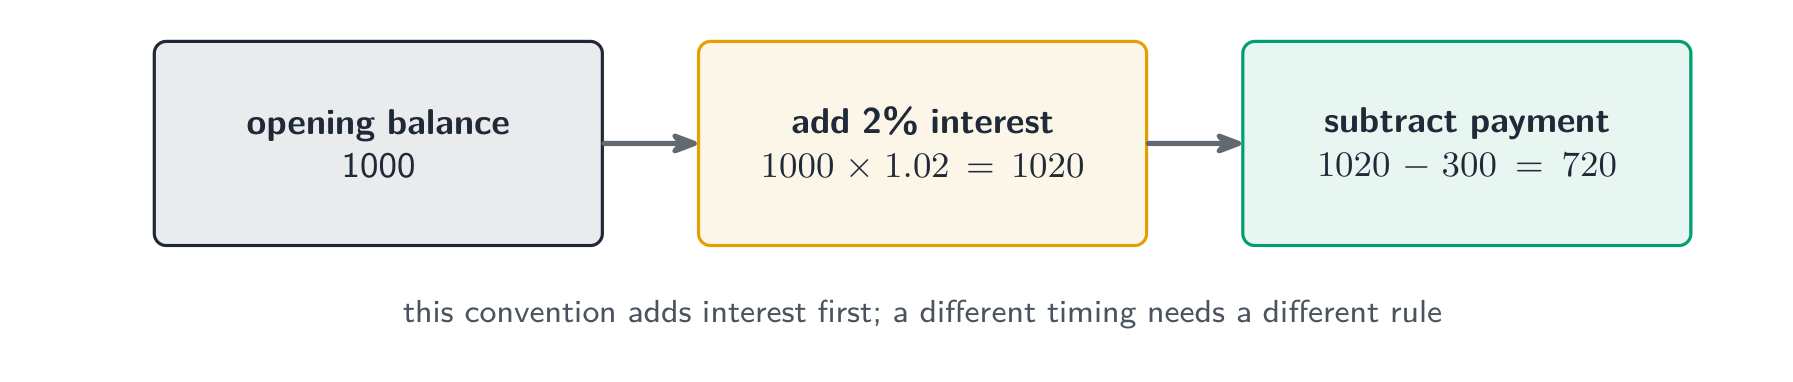
- For this practice convention, add period interest before subtracting the payment: $B_n=B_{n-1}(1+r)-M$. A different payment timing changes the calculation.
Discount a future amount under a stated model
- Present value 现值 uses $PV=FV/(1+r)^n$ for the specified discount rate and periods. It is a modelled equivalent, not an unconditional claim that all future money has one value today.
- With $FV=11000$, annual rate 5% and two years, $PV=11000/(1.05)^2\approx9977.32$. Round only as requested after calculating.
11000 在 2 年后的现值是多少(年利率 5%)?结果四舍五入取整。
难度 2/5 · 今日首次完成可获 140 金币及少量额外奖励
11000 ÷ 1.05² = 9977。这就是复利公式的变形。
Payment schedules need explicit conditions
- An annuity 年金 has specified payments at regular intervals. A loan repayment 贷款还款 may include interest and principal, with an adjusted final payment to clear the balance.
- Interest need not be most of an early payment. At opening balance 1000, period rate 2% and payment 300, interest is 20 and principal reduction is 280.
每期先计利息再还款
$B_n=B_{n-1}(1+r)-M$
还款先支付利息,剩余部分才减少本金。
对于任何生息贷款,早期还款的大部分必然用于支付利息而非偿还本金。
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
具体分配取决于余额、周期利率和还款额。若余额为1000,利率为2%,还款额为扣除利息后的300,则其中20用于支付利息,280用于减少本金。
Correct a rate comparison. Under a no-interim-payment model, 10000 at 9% annually for three years gives $A_A=10000(1.09)^3=12950.29$. A nominal 8.7% annual rate with monthly rate $0.087/12$ gives $A_B=10000(1+0.087/12)^{36}\approx12970.06$. B is higher by about 19.77 units under these terms. A regular-repayment loan needs its own schedule instead of this model.
在无分期付款模式下,比较本金10000按年利率9%复利计算3年与名义年利率8.7%按月复利计算3年的结果。哪个终值更高?
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
年复利得出12950.29;月复利约为12970.06。在所述无付款和无费用模型下,后者高出约19.77。
A nominal and effective rate describe different calculations. A nominal rate 名义利率 of 12% with monthly rate 1% gives effective rate 实际利率 $(1.01)^{12}-1\approx12.68\%$ annually. Sheet 2.3 specifies every period rate and payment rather than relying on a headline label or a real lending convention.
年名义利率 12%、按月计息,实际年利率约为……
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
1.01¹² = 1.1268。计息越频繁,实际利率就越高于名义利率。
With a stated nominal annual rate split into 12 monthly periods, divide that rate by 12 and multiply years by 12. Do not use this conversion for a rate already specified as effective annually without deriving its monthly equivalent.
按月计息、借 5 年,指数应该是多少?
难度 1/5 · 今日首次完成可获 100 金币及少量额外奖励
每年12个计息期,共5年。将年利率除以12但未相应调整指数是常见错误。