Policy: the multiplier and the clock
Đã giới thiệu| English | Ý nghĩa |
|---|---|
| marginal propensity to consume/ˈmɑːdʒɪnl prəˈpensɪti tə kənˈsjuːm/ | The proportion of an additional unit of disposable income that is spent on consumption. |
| multiplier/ˌmʌltɪˈplaɪə/ | A number by which another quantity is multiplied. |
| crowding out/ˈkraʊdɪŋ aʊt/ | A reduction in private spending or investment caused by increased government activity, often through higher interest rates. |
When the recession hits, somebody decides
- Aurora's output gap is −£60bn. The arithmetic of the response is one fraction. The judgement — what to buy, whose taxes to cut, and WHEN — is everything else.
- This lesson carries the marginal propensity to consume 边际消费倾向 from lesson 0401's loop into the policy room.
The multiplier fraction
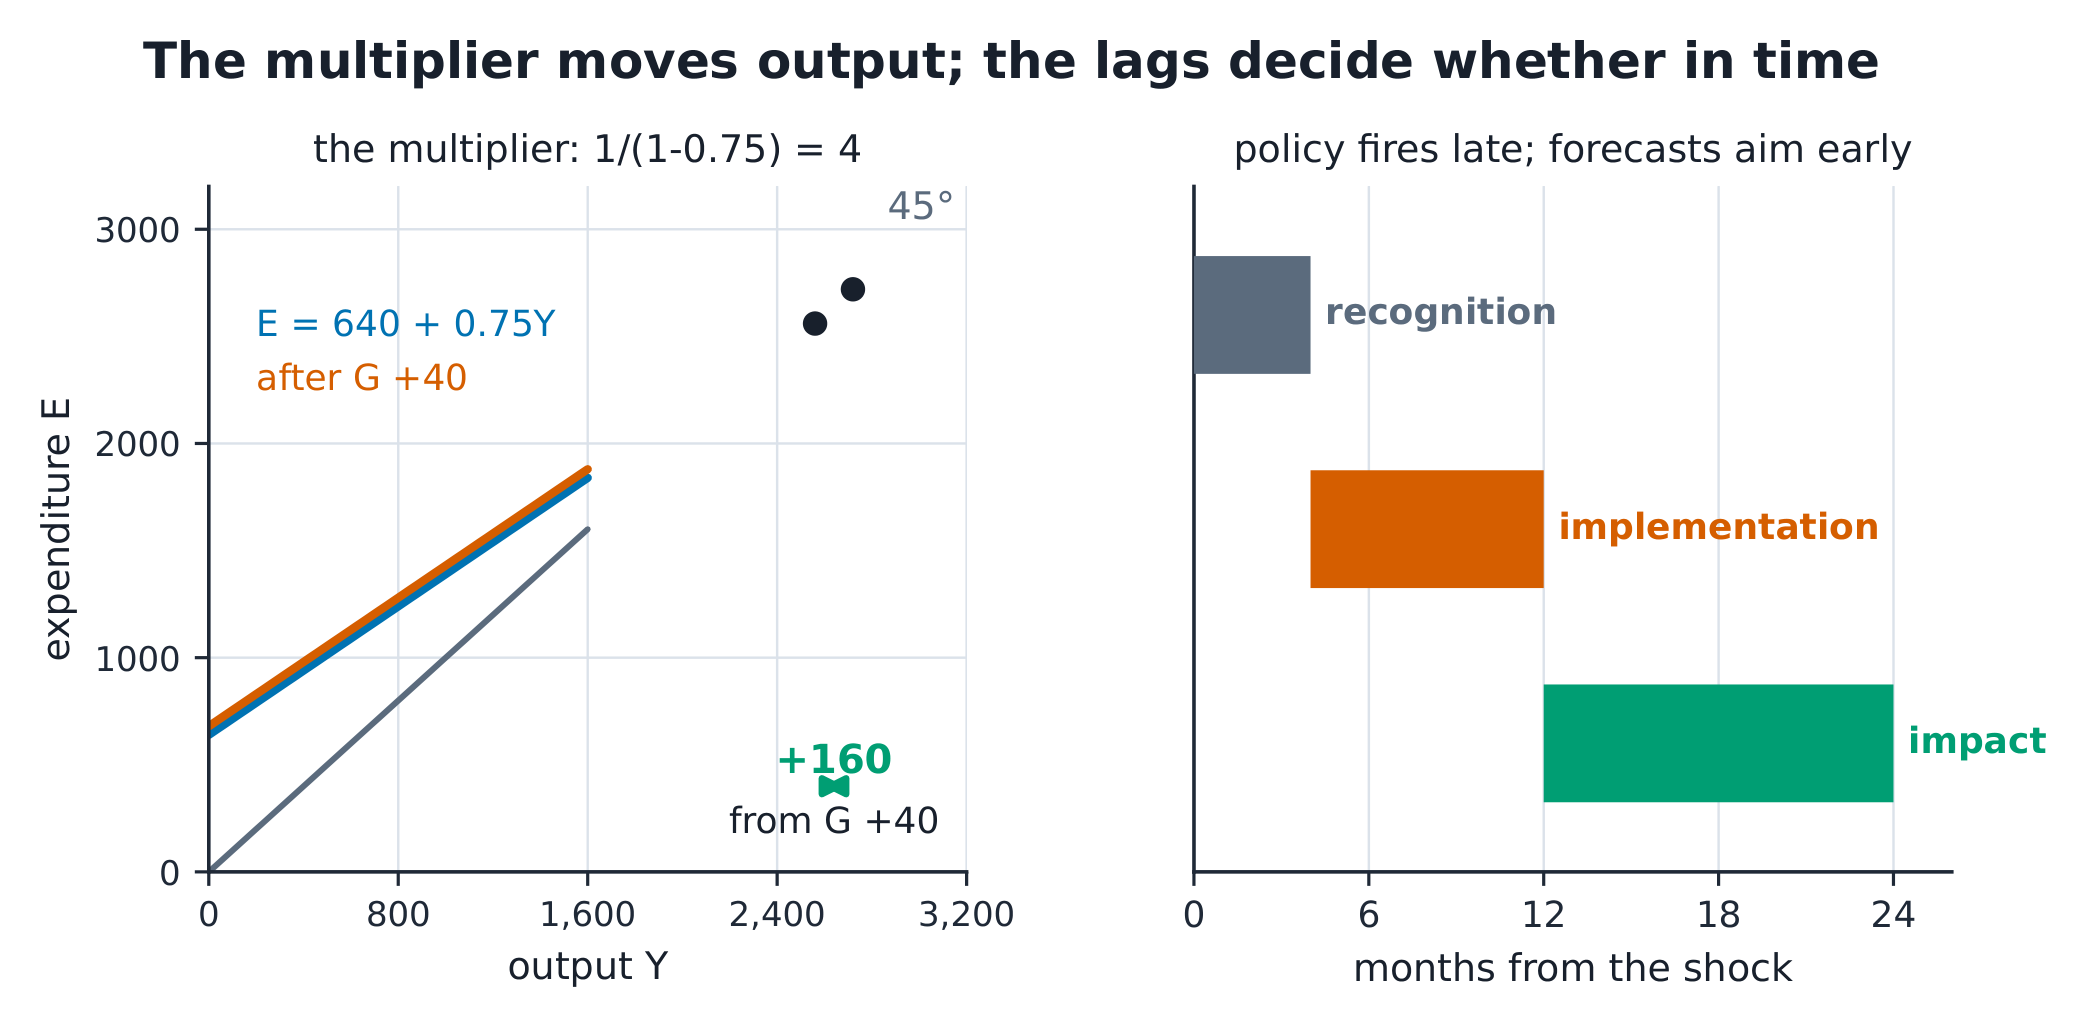
- With $MPC = 0.75$, the multiplier 乘数 is $1/(1-0.75) = 4$: a £40bn spending rise lifts income by £160bn ✓, because each round of spending becomes income and three quarters of it is spent again.
- The tax multiplier is $-MPC/(1-MPC) = -3$: a £40bn tax cut first round spends only $40 \times 0.75 = 30$, so output rises £120bn ✓.
MPC 0.75. The spending multiplier?
Độ khó 2/5 · 140 xu + phần thưởng nhỏ khi hoàn thành lần đầu tiên hôm nay
$1/(1-0.75) = 4$. A 40 rise in G lifts Y by 160.
MPC 0.75. A tax CUT of 40 raises output by how much?
Độ khó 2/5 · 140 xu + phần thưởng nhỏ khi hoàn thành lần đầu tiên hôm nay
First round only $40 \times 0.75 = 30$ is spent, then the multiplier: $30 \times 4 = 120$. The tax multiplier is -3.
The balanced-budget theorem
- Raise G by 50 AND taxes by 50: output rises $50 \times 4 - 50 \times 3 = \mathbf{+50}$ ✓.
- The balanced-budget multiplier is exactly 1 — a one-line theorem you can prove from the two fractions above.
G and T both rise by 50 (MPC 0.75). What happens to output?
Độ khó 2/5 · 140 xu + phần thưởng nhỏ khi hoàn thành lần đầu tiên hôm nay
$50 \times 4 - 50 \times 3 = +50$ - the balanced-budget multiplier of exactly 1.
The gap is -60. Which package closes it under the simple model?
Độ khó 1/5 · 100 xu + phần thưởng nhỏ khi hoàn thành lần đầu tiên hôm nay
$15 \times 4 = 60$ and $20 \times 3 = 60$. The arithmetic offers choices; the judgement is debt, composition and speed.
The fine print: crowding out and leakages
- Government borrowing can raise interest rates and displace private investment — crowding out 挤出效应. Imports and taxes leak rounds out of the chain.
- Real-world multipliers sit well below 4. The fraction is a model result, and the model's limits belong IN the answer.
Crowding out means the fiscal multiplier is exactly zero in practice.
Độ khó 1/5 · 100 xu + phần thưởng nhỏ khi hoàn thành lần đầu tiên hôm nay
It means borrowing-fuelled spending raises rates and displaces some private investment, so the multiplier falls BELOW the simple 4 - not to zero. State the direction and the model.
The lags
- Recognition (is this a shock or noise?), implementation (budgets are not written overnight), impact (the multiplier takes quarters to round out).
- Monetary policy fires quickly and lands slowly; fiscal is the reverse. A policy that arrives after the patient recovers is not neutral — it is pro-cyclical.
Which clock does each delay belong to?
Sort the policy room's delays into recognition, implementation and impact lags, and match instruments to speed.
Match each lag to its question.
Độ khó 2/5 · 140 xu + phần thưởng nhỏ khi hoàn thành lần đầu tiên hôm nay
Three delays, one risk - late policy amplifies the cycle it meant to smooth.
Monetary policy is slower to announce than fiscal policy but lands sooner.
Độ khó 1/5 · 100 xu + phần thưởng nhỏ khi hoàn thành lần đầu tiên hôm nay
The reverse: a rate decision is announced in weeks (fast fire) but transmits over quarters (slow landing); fiscal takes calendars to pass but its spending lands as it is spent.
The dated episode: 2021–23
- Supply shocks (energy, shipping) met stimulus-fortified demand; UK CPI peaked at 11.1% in October 2022 (ONS), unemployment sat near historic lows, and policy rates went from near zero to 4–5% through 2023.
- Read it with this course: a negative supply shock moves inflation and output the WRONG way together (the Phillips trade-off fails), the tightening landed a year later (lags, exactly as above), and energy-bill support worked through prices, not around them.
In 2022 the UK faced 11.1% CPI inflation with low unemployment. What does the Phillips framework say about that combination?
Độ khó 1/5 · 100 xu + phần thưởng nhỏ khi hoàn thành lần đầu tiên hôm nay
A negative supply shock raises inflation while lowering output - both move the wrong way for the simple curve. The 2023 tightening then landed with the usual lags.
Three policy slips
- Quoting "the multiplier" as a fact. It is $1/(1-MPC)$ under leakages, borrowing costs and supply slack — state the model.
- Comparing a tax cut and spending pound-for-pound. The first round differs: 0.75 of the tax cut is spent, all of the spending is.
- Grading policy by announcement, not arrival. The question is always when the effect landed.
Recap
- Spending multiplier $1/(1-MPC)$; tax multiplier $-MPC/(1-MPC)$; balanced budget exactly 1.
- Lags are why policy targets forecasts; crowding out and leakages are why the arithmetic is a ceiling.