Statements: one profit, one cash, zero new numbers
Introduit| English | Sens |
|---|---|
| income statement/ˈɪŋkʌm ˈsteɪtmənt/ | A financial statement reporting income, expenses and profit or loss over a period. |
| gross profit/ɡrəʊs ˈprɒfɪt/ | gross profit |
| statement of financial position/ˈsteɪtmənt ɒv faɪˈnænʃl pəˈzɪʃn/ | A financial statement showing an organisation's assets, liabilities and equity at a particular date. |
| retained profit/rɪˈteɪnd ˈprɒfɪt/ | Profit kept in a business after distributions to its owners. |
Two questions about Nimbus's first year
- The owner asks two different questions on 31 December: "Did we earn anything this year?" and "What do we have now, and who has a claim on it?"
- Each question has its own statement. This lesson builds both from the numbers already in the ledger, and shows the one number that joins them.
The income statement: the year in motion
- The income statement 利润表 covers a period: revenue earned minus the expenses matched to it. Its last line is the profit for the year.
- Gross profit 毛利 comes first: revenue minus the cost of the goods sold. Then the running costs, depreciation and accrued items come off to leave profit.
The income statement shows what Nimbus owns on 31 December.
Difficulté 1/5 · 100 pièces + un petit bonus lors de la première réussite aujourd'hui
The income statement covers a period and ends in the profit for the year. What Nimbus owns on one date is in the statement of financial position.
Nimbus's income statement, year 1
- Every line is an adjusted figure from the accruals lesson: rent for three months, one year's depreciation, accrued electricity and interest.
| Year 1 | £ |
|---|---|
| Revenue | 156,000 |
| Cost of sales | (62,400) |
| Gross profit | 93,600 |
| Wages | (52,000) |
| Rent (3 of 12 months) | (3,000) |
| Other running costs | (8,000) |
| Depreciation | (1,080) |
| Electricity accrued | (250) |
| Interest accrued | (900) |
| Profit for the year | 28,370 |
Nimbus's revenue is £156,000 and its gross profit is £93,600. What is the gross profit as a percentage of revenue?
Difficulté 2/5 · 140 pièces + un petit bonus lors de la première réussite aujourd'hui
$\dfrac{93\,600}{156\,000} = 0.60$, so 60%. Sixty pence of every pound of sales is left after the cost of the bread.
The statement of financial position: one date
- The statement of financial position 财务状况表 (the balance sheet) is the accounting equation on one day: what the business holds, and who claims it.
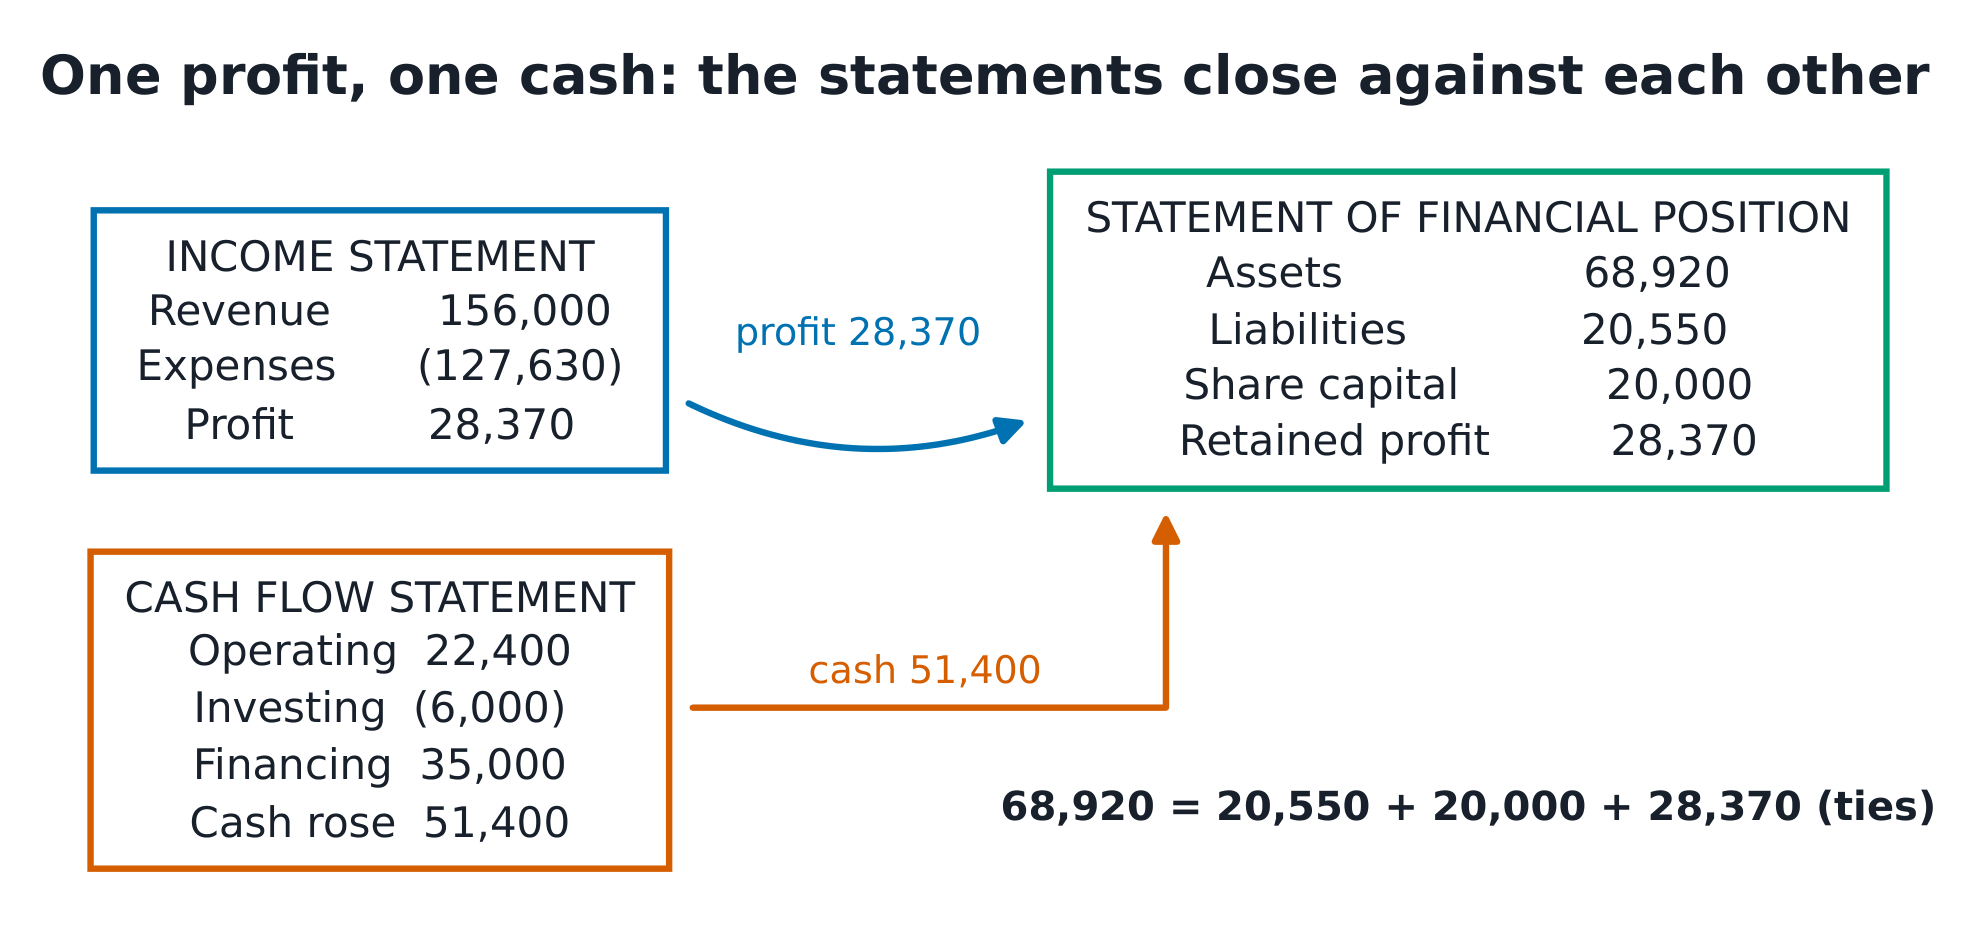
- Cash comes from the year's real payments: in 20,000 + 15,000 + 156,000 = 191,000; out 6,000 + 62,000 + 51,600 + 12,000 + 8,000 = 139,600; left 51,400.
Which statement shows it?
Sort each Nimbus figure. Amounts that build up over the year belong in the income statement; amounts that stand on 31 December belong in the statement of financial position.
Nimbus bought £66,000 of ingredients in the year and still owes £4,000 at the year end. How much cash did it pay suppliers, in £?
Difficulté 2/5 · 140 pièces + un petit bonus lors de la première réussite aujourd'hui
$66\,000 - 4\,000 = 62\,000$ paid. The £4,000 still owed is the payables line.
Nimbus at 31 December
| Assets | £ |
|---|---|
| Cash | 51,400 |
| Inventory | 3,600 |
| Prepaid rent | 9,000 |
| Equipment (6,000 − 1,080) | 4,920 |
| Total assets | 68,920 |
| Liabilities and equity | £ |
|---|---|
| Loan | 15,000 |
| Payables | 4,000 |
| Accrued wages, electricity, interest | 1,550 |
| Share capital | 20,000 |
| Retained profit | 28,370 |
| Total | 68,920 |
- Liabilities are £20,550 and equity £48,370; together they equal the assets.
The oven cost £6,000 and one year's depreciation is £1,080. At what amount does it appear in the statement of financial position?
Difficulté 1/5 · 100 pièces + un petit bonus lors de la première réussite aujourd'hui
Carrying amount = cost − accumulated depreciation = £4,920. The £1,080 is also an expense in the income statement.
Assets are £68,920, liabilities £20,550 and share capital £20,000. Retained profit must be
Difficulté 1/5 · 100 pièces + un petit bonus lors de la première réussite aujourd'hui
Equity is $68\,920 - 20\,550 = 48\,370$. Take away the share capital to leave £28,370: the year's profit.
One number joins them
- The year's profit, £28,370, closes the income statement and appears again as retained profit 留存利润 inside equity. That is why the balance sheet still balances after a year of trading.
- Each adjustment shows in both statements: depreciation is an expense of £1,080 and also lowers equipment to £4,920. No new numbers are made up at statement stage.
Match each item to where it appears.
Difficulté 2/5 · 140 pièces + un petit bonus lors de la première réussite aujourd'hui
Each adjustment from the year end has a home. Depreciation also lowers the equipment line, so it shows in both statements.
Which number links the income statement to the statement of financial position?
Difficulté 1/5 · 100 pièces + un petit bonus lors de la première réussite aujourd'hui
Profit closes the income statement and becomes part of equity: £20,000 of share capital plus £28,370 retained = £48,370.
When the balance sheet will not balance
- Depreciation in one statement only. Charging the £1,080 as an expense but leaving the oven at £6,000 overstates assets by £1,080.
- The prepayment under liabilities. Rent paid in advance is a right Nimbus owns, so it is an asset.
- Dividends. Profit paid out to owners reduces equity directly; it is not an expense in the income statement.
A student's balance sheet does not balance. Which mistakes could cause that? Select all that apply.
Difficulté 2/5 · 140 pièces + un petit bonus lors de la première réussite aujourd'hui
The first overstates assets; the second moves £9,000 from assets to liabilities. Merging two expense lines or renaming one leaves every total unchanged.
Recap
- Income statement: revenue minus matched expenses over a period.
- Statement of financial position: assets = liabilities + equity on one date.
- Profit links them as retained profit; every adjustment appears in both.