Inversión y endeudamiento
Introducido| English | Significado |
|---|---|
| present value/ˈprezənt ˈvæljuː/ | valor presente |
| annuity/əˈnjuːɪti/ | anualidad |
| loan repayment/ləʊn rɪˈpeɪmənt/ | amortización de préstamo |
| effective rate/ɪˈfektɪv reɪt/ | tasa efectiva |
| nominal rate/ˈnɒmɪnl reɪt/ | tasa nominal |
State what happens to the balance
- Compound growth without payments uses $A=P(1+r)^n$. A loan with repayments generally needs a changing-balance rule instead.
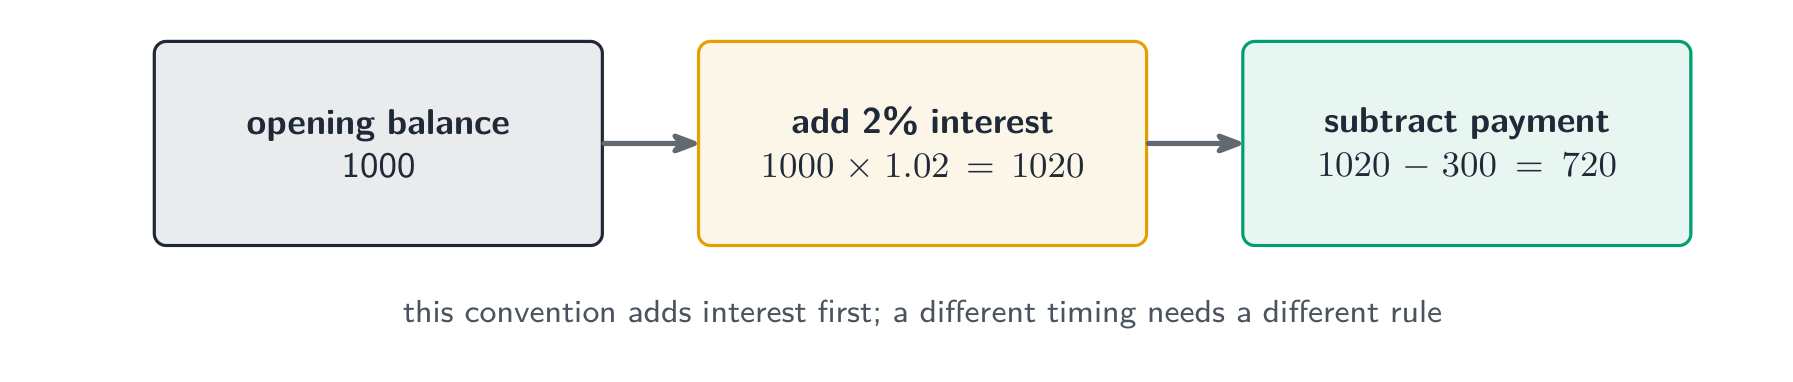
- For this practice convention, add period interest before subtracting the payment: $B_n=B_{n-1}(1+r)-M$. A different payment timing changes the calculation.
Discount a future amount under a stated model
- Present value 现值 uses $PV=FV/(1+r)^n$ for the specified discount rate and periods. It is a modelled equivalent, not an unconditional claim that all future money has one value today.
- With $FV=11000$, annual rate 5% and two years, $PV=11000/(1.05)^2\approx9977.32$. Round only as requested after calculating.
¿Cuál es el valor presente de 11000 recibidos en 2 años, al 5% anual? Redondee al número entero más cercano.
Dificultad 2/5 · 140 monedas + un pequeño bono en el primer intento de hoy
11000 ÷ 1.05² = 9977. Es la fórmula de interés compuesto despejada.
Payment schedules need explicit conditions
- An annuity 年金 has specified payments at regular intervals. A loan repayment 贷款还款 may include interest and principal, with an adjusted final payment to clear the balance.
- Interest need not be most of an early payment. At opening balance 1000, period rate 2% and payment 300, interest is 20 and principal reduction is 280.
Interest before each loan payment
$B_n=B_{n-1}(1+r)-M$
A payment covers interest first; only the remainder reduces the loan.
Por cada préstamo con rendimiento de intereses, la mayor parte de cada pago anticipado necesariamente va a intereses en lugar del capital.
Dificultad 1/5 · 100 monedas + un pequeño bono en el primer intento de hoy
La partición depende del saldo, la tasa del periodo y el pago. Con saldo 1000, tasa 2% y pago 300 tras intereses, solo 20 van a intereses y 280 reducen el capital.
Correct a rate comparison. Under a no-interim-payment model, 10000 at 9% annually for three years gives $A_A=10000(1.09)^3=12950.29$. A nominal 8.7% annual rate with monthly rate $0.087/12$ gives $A_B=10000(1+0.087/12)^{36}\approx12970.06$. B is higher by about 19.77 units under these terms. A regular-repayment loan needs its own schedule instead of this model.
Bajo un modelo sin pagos intermedios, compara 10000 al 9% capitalizado anualmente durante 3 años con una tasa nominal del 8.7% anual capitalizable mensualmente durante 3 años. ¿Cuál monto final es mayor?
Dificultad 1/5 · 100 monedas + un pequeño bono en el primer intento de hoy
La capitalización anual da 12950.29; la capitalización mensual da aproximadamente 12970.06. El segundo es mayor por aproximadamente 19.77 bajo el modelo declarado de sin pago y sin tarifa.
A nominal and effective rate describe different calculations. A nominal rate 名义利率 of 12% with monthly rate 1% gives effective rate 实际利率 $(1.01)^{12}-1\approx12.68\%$ annually. Sheet 2.3 specifies every period rate and payment rather than relying on a headline label or a real lending convention.
Un 12% anual capitalizable mensualmente tiene una tasa efectiva anual de aproximadamente...
Dificultad 1/5 · 100 monedas + un pequeño bono en el primer intento de hoy
1.01¹² = 1.1268. Capitalizar con mayor frecuencia hace que la tasa efectiva supere a la nominal.
With a stated nominal annual rate split into 12 monthly periods, divide that rate by 12 and multiply years by 12. Do not use this conversion for a rate already specified as effective annually without deriving its monthly equivalent.
Para 5 años a una tasa capitalizable mensualmente, ¿cuál debería ser el exponente?
Dificultad 1/5 · 100 monedas + un pequeño bono en el primer intento de hoy
12 períodos al año durante 5 años. Dividir la tasa entre 12 sin multiplicar el exponente es el error estándar.