Financial plan
Introduced| English | Meaning |
|---|---|
| financial plan/faɪˈnænʃl plæn/ | financial plan |
| variable cost/ˈveərɪəbl kɒst/ | A cost whose total changes with the level of output or activity. |
| fixed cost/fɪkst kɒst/ | A cost that does not change with output within a specified period and relevant range of activity. |
| revenue/ˈrevənjuː/ | Income received by a business from selling goods or services before costs are deducted. |
| cash-flow forecast/kæʃ fləʊ ˈfɔːkæst/ | An estimate of future cash inflows, outflows and balances over a specified period. |
| sensitivity analysis/ˌsensɪˈtɪvɪti əˈnæləsɪs/ | sensitivity analysis |
Can the numbers carry the idea?
- A financial plan 财务计划 estimates the money a venture needs, earns, spends, and keeps over time.
- It connects the business idea to numbers: start-up capital, price, expected sales, variable costs, fixed costs, cash timing, and break-even.
- A neat spreadsheet is not a plan unless its assumptions are visible and can be challenged.
A spreadsheet can be neat and still contain a very messy assumption.
Separate the costs
- A fixed cost 固定成本 does not usually change with the number of units sold in the short term, such as a monthly permit or rent.
- A variable cost 可变成本 changes with each unit, such as a replacement inner tube for each repair.
- Revenue 收入总额 is price multiplied by quantity sold. Profit is revenue minus all costs, not just the cost of materials.
Match the item to its usual cost type.
Difficulty 2/5 · 140 coins + a small bonus on first completion today
One stays similar over the month; the other rises with each repair.
Test the weak assumptions
- A cash-flow forecast 现金流预测 asks when money arrives and leaves, not only whether the year ends profitably.
- Sensitivity analysis 敏感性分析 changes one important assumption—such as sales volume or cost—to see how fragile the plan is.
- A contingency is a prepared response to a realistic risk, such as holding a small cash reserve or arranging a second supplier.
Sensitivity analysis tests what happens when an important assumption changes.
Difficulty 1/5 · 100 coins + a small bonus on first completion today
It reveals whether the plan is fragile under a lower-sales or higher-cost case.
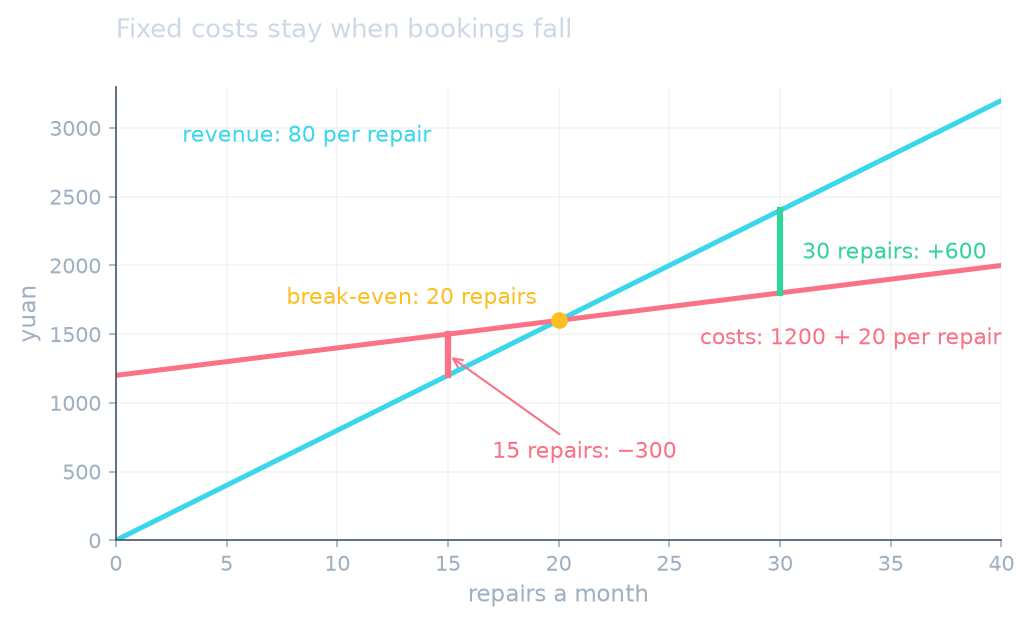
The repair service charges 80 yuan per puncture repair. Each repair uses 20 yuan of materials. Its monthly fixed costs are 1,200 yuan. If it completes 30 repairs, revenue is 2,400 yuan, variable costs are 600 yuan, and profit before any other costs is 600 yuan.
If only 15 repairs are booked, the same fixed costs remain. Testing that lower-sales case shows whether the venture has enough cash to continue.
Test the assumptions behind break-even
$Q_{BE}=\frac{F}{p-v};\quad \pi=(p-v)Q-F$
Changing sales volume changes profit while fixed costs remain. The starting values match the lesson example.
At 80 yuan per repair, what revenue comes from 30 repairs?
Difficulty 2/5 · 140 coins + a small bonus on first completion today
80 × 30 = 2400 yuan revenue.
Revenue is 2400 yuan, variable costs are 600 yuan, and fixed costs are 1200 yuan. What is profit in yuan?
Difficulty 2/5 · 140 coins + a small bonus on first completion today
2400 − 600 − 1200 = 600 yuan.
Write one English sentence explaining why 15 repairs can be riskier than 30 repairs for the venture.
Difficulty 3/5 · 200 coins + a small bonus on first completion today
Example: “With only 15 repairs, revenue falls but the 1200-yuan fixed costs still have to be paid.”
Revenue − variable costs − fixed costs = profit. Show each category. Do not call revenue “profit” before costs have been removed.
Do not hide an uncertain number inside one total. Label it as an assumption and test what happens if it is wrong.